
BitFrog
93 Posts
BitFrog
Report
Block User
BitFrog 是专业级加密货币交易服务平台,提供自营交易资金支持、交易返现、CEX 跟单、Hyperliquid、实盘追踪及行情资讯等服务,连接全球交易者与优质交易资源。
0 Following
3 Followers
19 Liked
Posts
All
Quotes
·
--
Article
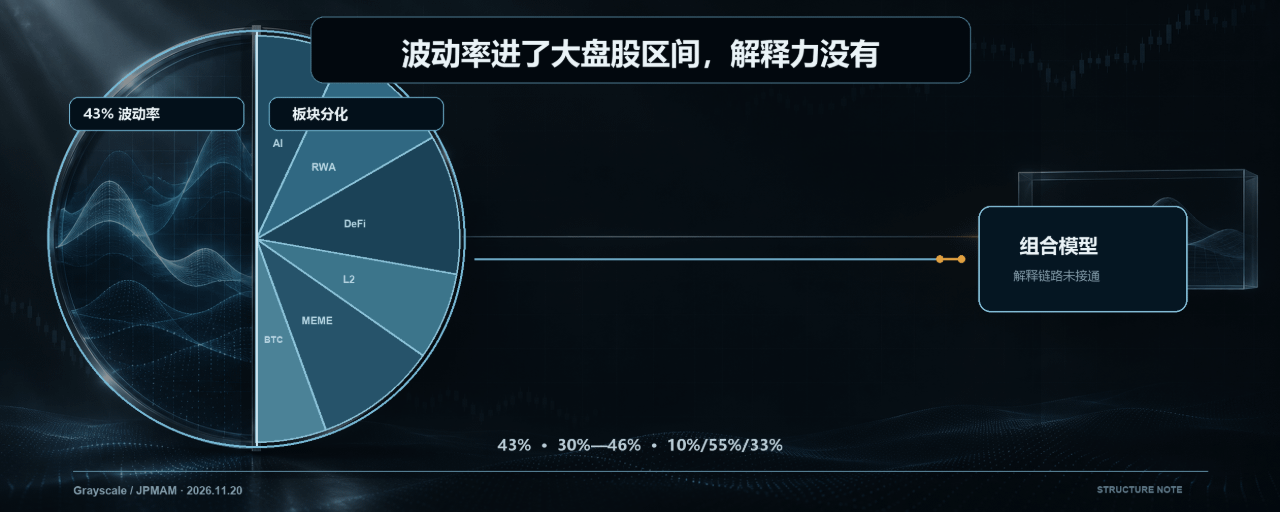
43% volatility, 30% to 46% explanatory powerSummary: Grayscale Research says Bitcoin’s realized volatility has fallen to around 43%, putting it in the range of U.S. large-cap stocks, but it explains only 30%–46% of the variation in returns across the crypto sector. J.P. Morgan Asset Management offers long-term assumptions of 10% returns, 55% volatility, and 33% correlation, but leaves Bitcoin out of its core portfolio because of its excessive volatility.
In the same month, Grayscale and J.P. Morgan Asset Management offered two sets of figures on Bitcoin risk. They point in the same direction, but diverge at a crucial step.
43%: A figure that has entered the “large-cap range”
A report released by Grayscale on November 19 (Beyond Volatility: Rethinking Crypto Risk) offers a clear reading: Bitcoin’s one-year realized volatility has fallen to around 43%, in the mid-40% range—well below the nearly 100% to 200% levels seen in earlier cycles, and also below the decade average of 64% and the 81% recorded five years ago.
43% volatility, 30% to 46% explanatory power
Summary: Grayscale Research says Bitcoin’s realized volatility has fallen to around 43%, putting it in the range of U.S. large-cap stocks, but it explains only 30%–46% of the variation in returns across the crypto sector. J.P. Morgan Asset Management offers long-term assumptions of 10% returns, 55% volatility, and 33% correlation, but leaves Bitcoin out of its core portfolio because of its excessive volatility.
In the same month, Grayscale and J.P. Morgan Asset Management offered two sets of figures on Bitcoin risk. They point in the same direction, but diverge at a crucial step.
43%: A figure that has entered the “large-cap range”
A report released by Grayscale on November 19 (Beyond Volatility: Rethinking Crypto Risk) offers a clear reading: Bitcoin’s one-year realized volatility has fallen to around 43%, in the mid-40% range—well below the nearly 100% to 200% levels seen in earlier cycles, and also below the decade average of 64% and the 81% recorded five years ago.
In the same month, Grayscale and J.P. Morgan Asset Management offered two sets of figures on Bitcoin risk. They point in the same direction, but diverge at a crucial step.
43%: A figure that has entered the “large-cap range”
A report released by Grayscale on November 19 (Beyond Volatility: Rethinking Crypto Risk) offers a clear reading: Bitcoin’s one-year realized volatility has fallen to around 43%, in the mid-40% range—well below the nearly 100% to 200% levels seen in earlier cycles, and also below the decade average of 64% and the 81% recorded five years ago.
45
·
--
ETH whale 0x4AB7 sells another 5,000 to stop losses: entered at $2,256, current price $1,745, cumulative losses exceed $8.5 million.
According to monitoring, whale address 0x4AB7 has again sold 5,000 $ETH (about $8.65 million) to stop losses. The address still holds 11,000 ETH (about $19.12 million), and cumulative losses have exceeded $8.5 million.
This is not a one-time operation. The address accumulated a position of 17,077 #ETH between November 1 and 10 at an average price of about $2,256. Since November 10, it has deposited a total of 6,077 ETH (about $10.878 million) to Binance, with an average deposit price of $1,790.11. This 5,000 is the latest step on this continuous stop-loss path.
ETH is currently trading at about $1,745, leaving a significant gap from its entry cost. The remaining 11,000 ETH is currently showing an unrealized loss of about $5.605 million. Unless the price can effectively regain the area above $2,000, the address's passive reduction pressure will not be relieved.
ETH whale 0x4AB7 sells another 5,000 to stop losses: entered at $2,256, current price $1,745, cumulative losses exceed $8.5 million.
According to monitoring, whale address 0x4AB7 has again sold 5,000 $ETH (about $8.65 million) to stop losses. The address still holds 11,000 ETH (about $19.12 million), and cumulative losses have exceeded $8.5 million.
This is not a one-time operation. The address accumulated a position of 17,077 #ETH between November 1 and 10 at an average price of about $2,256. Since November 10, it has deposited a total of 6,077 ETH (about $10.878 million) to Binance, with an average deposit price of $1,790.11. This 5,000 is the latest step on this continuous stop-loss path.
ETH is currently trading at about $1,745, leaving a significant gap from its entry cost. The remaining 11,000 ETH is currently showing an unrealized loss of about $5.605 million. Unless the price can effectively regain the area above $2,000, the address's passive reduction pressure will not be relieved.
According to monitoring, whale address 0x4AB7 has again sold 5,000 $ETH (about $8.65 million) to stop losses. The address still holds 11,000 ETH (about $19.12 million), and cumulative losses have exceeded $8.5 million.
This is not a one-time operation. The address accumulated a position of 17,077 #ETH between November 1 and 10 at an average price of about $2,256. Since November 10, it has deposited a total of 6,077 ETH (about $10.878 million) to Binance, with an average deposit price of $1,790.11. This 5,000 is the latest step on this continuous stop-loss path.
ETH is currently trading at about $1,745, leaving a significant gap from its entry cost. The remaining 11,000 ETH is currently showing an unrealized loss of about $5.605 million. Unless the price can effectively regain the area above $2,000, the address's passive reduction pressure will not be relieved.
52
·
--
#Anthropic (ANT) closed at $97 on its first day of trading, then fell a further 5% to around $92 in after-hours trading.
The largest short seller, who previously opened a $97 million ANT short position, made the right call and is currently up about $10 million overall. The address began closing its short position to take profits after the market closed. It has now closed about $30 million worth of shorts and still holds about $67 million worth.
#Anthropic (ANT) closed at $97 on its first day of trading, then fell a further 5% to around $92 in after-hours trading.
The largest short seller, who previously opened a $97 million ANT short position, made the right call and is currently up about $10 million overall. The address began closing its short position to take profits after the market closed. It has now closed about $30 million worth of shorts and still holds about $67 million worth.
The largest short seller, who previously opened a $97 million ANT short position, made the right call and is currently up about $10 million overall. The address began closing its short position to take profits after the market closed. It has now closed about $30 million worth of shorts and still holds about $67 million worth.
70
·
--
After predicting that ETH, ETH, ZEC, NEAR, NEAR, and VVV would rise, on-chain funds associated with Arthur Hayes showed the following activity:
November 12: Arthur Hayes transferred 3 million USDC to OTC platforms Flowdesk and Galaxy Digital.
November 17: Arthur Hayes posted a prediction that $ETH , $ZEC , $NEAR , and VVV (the “Four Horsemen”) would rise, with target prices of $2,800, $1,800, $6, and $40, respectively, and said he had established small- to medium-sized positions.
November 17–18: An address flagged by Arkham as associated with Arthur Hayes deposited a cumulative 4,700 ETH (about $8.5 million) to exchanges starting on the 17th, at an average deposit price of $1,808.87.
Earlier (around November 14): The aforementioned associated address had transferred 5 million USDC to Arthur Hayes.
After predicting that ETH, ETH, ZEC, NEAR, NEAR, and VVV would rise, on-chain funds associated with Arthur Hayes showed the following activity:
November 12: Arthur Hayes transferred 3 million USDC to OTC platforms Flowdesk and Galaxy Digital.
November 17: Arthur Hayes posted a prediction that $ETH , $ZEC , $NEAR , and VVV (the “Four Horsemen”) would rise, with target prices of $2,800, $1,800, $6, and $40, respectively, and said he had established small- to medium-sized positions.
November 17–18: An address flagged by Arkham as associated with Arthur Hayes deposited a cumulative 4,700 ETH (about $8.5 million) to exchanges starting on the 17th, at an average deposit price of $1,808.87.
Earlier (around November 14): The aforementioned associated address had transferred 5 million USDC to Arthur Hayes.
November 12: Arthur Hayes transferred 3 million USDC to OTC platforms Flowdesk and Galaxy Digital.
November 17: Arthur Hayes posted a prediction that $ETH , $ZEC , $NEAR , and VVV (the “Four Horsemen”) would rise, with target prices of $2,800, $1,800, $6, and $40, respectively, and said he had established small- to medium-sized positions.
November 17–18: An address flagged by Arkham as associated with Arthur Hayes deposited a cumulative 4,700 ETH (about $8.5 million) to exchanges starting on the 17th, at an average deposit price of $1,808.87.
Earlier (around November 14): The aforementioned associated address had transferred 5 million USDC to Arthur Hayes.
314
·
--
The attacker’s ongoing “ETH→BTC” migration: 14,895 $ETH swapped across chains in 24 hours, with the money-laundering trail continuing to grow.
According to monitoring, the address linked to the Binance hot wallet attacker (0x2763...af81) spread 12,000 ETH across 11 addresses through 94 transactions between November 18 and 19. Approximately 11,773.6 ETH has been swapped for BTC via Thorchain, while the remaining approximately 226.3 ETH has been scattered across multiple new addresses.
Over the past 24 hours, the attacker has swapped a total of 14,895.59 ETH via Thorchain. Cumulative swap volume on Thorchain has climbed to 11,578 transactions, worth approximately $338 million. The funds continue to be split among new addresses, with no confirmed transfers to exchanges so far.
The attacker still holds approximately 17,228 BTC and 464,000 ETH (with a combined value of approximately $1.95 billion). The current cross-chain swaps represent only part of the holdings. With BTC trading weakly around $64,000, the main purpose of this activity is to change the form of the assets and make them harder to trace, rather than to cash out quickly.
The attacker’s ongoing “ETH→BTC” migration: 14,895 $ETH swapped across chains in 24 hours, with the money-laundering trail continuing to grow.
According to monitoring, the address linked to the Binance hot wallet attacker (0x2763...af81) spread 12,000 ETH across 11 addresses through 94 transactions between November 18 and 19. Approximately 11,773.6 ETH has been swapped for BTC via Thorchain, while the remaining approximately 226.3 ETH has been scattered across multiple new addresses.
Over the past 24 hours, the attacker has swapped a total of 14,895.59 ETH via Thorchain. Cumulative swap volume on Thorchain has climbed to 11,578 transactions, worth approximately $338 million. The funds continue to be split among new addresses, with no confirmed transfers to exchanges so far.
The attacker still holds approximately 17,228 BTC and 464,000 ETH (with a combined value of approximately $1.95 billion). The current cross-chain swaps represent only part of the holdings. With BTC trading weakly around $64,000, the main purpose of this activity is to change the form of the assets and make them harder to trace, rather than to cash out quickly.
According to monitoring, the address linked to the Binance hot wallet attacker (0x2763...af81) spread 12,000 ETH across 11 addresses through 94 transactions between November 18 and 19. Approximately 11,773.6 ETH has been swapped for BTC via Thorchain, while the remaining approximately 226.3 ETH has been scattered across multiple new addresses.
Over the past 24 hours, the attacker has swapped a total of 14,895.59 ETH via Thorchain. Cumulative swap volume on Thorchain has climbed to 11,578 transactions, worth approximately $338 million. The funds continue to be split among new addresses, with no confirmed transfers to exchanges so far.
The attacker still holds approximately 17,228 BTC and 464,000 ETH (with a combined value of approximately $1.95 billion). The current cross-chain swaps represent only part of the holdings. With BTC trading weakly around $64,000, the main purpose of this activity is to change the form of the assets and make them harder to trace, rather than to cash out quickly.
234
·
--
According to monitoring data, the address 0x5CBC, which some trackers have labeled as “associated with the Ethereum Foundation,” once again sold 1,200 $ETH through CoWSwap today, worth approximately $2.14 million. It converted the proceeds to USDS and deposited them into an interest-bearing contract in the Sky protocol, receiving approximately 1.59 million sUSDS.
On-chain analyst Specter noted that the attribution of this address to the Ethereum Foundation is clearly flawed. Tracing suggests it was more likely the largest single buyer in the 2017 BAT ICO, contributing 20,522 ETH to the crowdfunding campaign and receiving 131.3 million BAT—not an address controlled by the Ethereum Foundation itself.
Since October 26, the address has sold a total of 7,785 ETH, worth approximately $16.35 million, at an average price of $2,100. ETH is currently trading in the $1,750–$1,800 range, down approximately 28% over two weeks. The sales were executed as prices continued to weaken, rather than as a high-price cash-out.
According to monitoring data, the address 0x5CBC, which some trackers have labeled as “associated with the Ethereum Foundation,” once again sold 1,200 $ETH through CoWSwap today, worth approximately $2.14 million. It converted the proceeds to USDS and deposited them into an interest-bearing contract in the Sky protocol, receiving approximately 1.59 million sUSDS.
On-chain analyst Specter noted that the attribution of this address to the Ethereum Foundation is clearly flawed. Tracing suggests it was more likely the largest single buyer in the 2017 BAT ICO, contributing 20,522 ETH to the crowdfunding campaign and receiving 131.3 million BAT—not an address controlled by the Ethereum Foundation itself.
Since October 26, the address has sold a total of 7,785 ETH, worth approximately $16.35 million, at an average price of $2,100. ETH is currently trading in the $1,750–$1,800 range, down approximately 28% over two weeks. The sales were executed as prices continued to weaken, rather than as a high-price cash-out.
On-chain analyst Specter noted that the attribution of this address to the Ethereum Foundation is clearly flawed. Tracing suggests it was more likely the largest single buyer in the 2017 BAT ICO, contributing 20,522 ETH to the crowdfunding campaign and receiving 131.3 million BAT—not an address controlled by the Ethereum Foundation itself.
Since October 26, the address has sold a total of 7,785 ETH, worth approximately $16.35 million, at an average price of $2,100. ETH is currently trading in the $1,750–$1,800 range, down approximately 28% over two weeks. The sales were executed as prices continued to weaken, rather than as a high-price cash-out.
146
·
--
November 17 Bitcoin ETF: a brief “stoppage of the bleeding” lasted only one day, with IBIT accounting for nearly 90% of the outflows
At 11:00 PM ET on November 17, U.S. spot Bitcoin ETFs posted a total net outflow of $240 million. Just one trading day earlier, they had recorded a net inflow of $7.9 million (ending a 7-day streak of outflows), but capital turned to exit again after only one day.
The outflows were highly concentrated: BlackRock’s IBIT saw a single-day net outflow of $209.5 million, accounting for about 87% of the entire market. The inflow side was almost negligible — MSBT had net inflows of $2.9263 million, and Grayscale BTC had net inflows of $1.1299 million, totaling less than $4.1 million, far from enough to offset IBIT’s redemptions.
The bigger picture: IBIT’s cumulative loss in November is about $2.12 billion, accounting for roughly 90% of the ETF outflows across the market during the same period; Bitcoin ETF net inflows for 2026 have already turned negative, recording about -$1.98 billion.
BTC is currently fluctuating weakly in the $64,000–$65,000 range, and the Fear and Greed Index is in the extreme fear zone. There are still no signs of any slowdown in ETF fund flows.
November 17 Bitcoin ETF: a brief “stoppage of the bleeding” lasted only one day, with IBIT accounting for nearly 90% of the outflows
At 11:00 PM ET on November 17, U.S. spot Bitcoin ETFs posted a total net outflow of $240 million. Just one trading day earlier, they had recorded a net inflow of $7.9 million (ending a 7-day streak of outflows), but capital turned to exit again after only one day.
The outflows were highly concentrated: BlackRock’s IBIT saw a single-day net outflow of $209.5 million, accounting for about 87% of the entire market. The inflow side was almost negligible — MSBT had net inflows of $2.9263 million, and Grayscale BTC had net inflows of $1.1299 million, totaling less than $4.1 million, far from enough to offset IBIT’s redemptions.
The bigger picture: IBIT’s cumulative loss in November is about $2.12 billion, accounting for roughly 90% of the ETF outflows across the market during the same period; Bitcoin ETF net inflows for 2026 have already turned negative, recording about -$1.98 billion.
BTC is currently fluctuating weakly in the $64,000–$65,000 range, and the Fear and Greed Index is in the extreme fear zone. There are still no signs of any slowdown in ETF fund flows.
At 11:00 PM ET on November 17, U.S. spot Bitcoin ETFs posted a total net outflow of $240 million. Just one trading day earlier, they had recorded a net inflow of $7.9 million (ending a 7-day streak of outflows), but capital turned to exit again after only one day.
The outflows were highly concentrated: BlackRock’s IBIT saw a single-day net outflow of $209.5 million, accounting for about 87% of the entire market. The inflow side was almost negligible — MSBT had net inflows of $2.9263 million, and Grayscale BTC had net inflows of $1.1299 million, totaling less than $4.1 million, far from enough to offset IBIT’s redemptions.
The bigger picture: IBIT’s cumulative loss in November is about $2.12 billion, accounting for roughly 90% of the ETF outflows across the market during the same period; Bitcoin ETF net inflows for 2026 have already turned negative, recording about -$1.98 billion.
BTC is currently fluctuating weakly in the $64,000–$65,000 range, and the Fear and Greed Index is in the extreme fear zone. There are still no signs of any slowdown in ETF fund flows.
59
·
--
Verified
Bitcoin fell 12.6% last week, closing above $65,000 but below its 200-week moving average, currently around $68,000. This is the fourth time since 2013 that it has experienced a “weekly drop of over 12% and a break below the 200-week moving average.”
Historical pattern: In the first three instances (August 2015, March 2020, and June 2022), prices fell a further 10%–17% after breaking below the average before rebounding. By this estimate, the corresponding support range is $54,000–$59,000, in line with Wintermute’s forecast of prices in the $50,000s. Gains three months later were 40.3%, 82.5%, and 6.3%, respectively (the 2022 rally did not last amid the FTX collapse). This combination is more common near the end of a bear market.
Current factors: Historical patterns are facing macroeconomic headwinds. US spot #BTC ETF net outflows totaled about $2.1 billion in November, the probability of a rate hike in December rose to 92%, and the 10-year US Treasury yield stood at 5.15%.
History is for reference only. In the short term, watch the $62,000 level and the $60,000 options support flagged by Wintermute. Whether a rebound materializes will depend on when funding conditions and interest rate expectations turn.
Bitcoin fell 12.6% last week, closing above $65,000 but below its 200-week moving average, currently around $68,000. This is the fourth time since 2013 that it has experienced a “weekly drop of over 12% and a break below the 200-week moving average.”
Historical pattern: In the first three instances (August 2015, March 2020, and June 2022), prices fell a further 10%–17% after breaking below the average before rebounding. By this estimate, the corresponding support range is $54,000–$59,000, in line with Wintermute’s forecast of prices in the $50,000s. Gains three months later were 40.3%, 82.5%, and 6.3%, respectively (the 2022 rally did not last amid the FTX collapse). This combination is more common near the end of a bear market.
Current factors: Historical patterns are facing macroeconomic headwinds. US spot #BTC ETF net outflows totaled about $2.1 billion in November, the probability of a rate hike in December rose to 92%, and the 10-year US Treasury yield stood at 5.15%.
History is for reference only. In the short term, watch the $62,000 level and the $60,000 options support flagged by Wintermute. Whether a rebound materializes will depend on when funding conditions and interest rate expectations turn.
Historical pattern: In the first three instances (August 2015, March 2020, and June 2022), prices fell a further 10%–17% after breaking below the average before rebounding. By this estimate, the corresponding support range is $54,000–$59,000, in line with Wintermute’s forecast of prices in the $50,000s. Gains three months later were 40.3%, 82.5%, and 6.3%, respectively (the 2022 rally did not last amid the FTX collapse). This combination is more common near the end of a bear market.
Current factors: Historical patterns are facing macroeconomic headwinds. US spot #BTC ETF net outflows totaled about $2.1 billion in November, the probability of a rate hike in December rose to 92%, and the 10-year US Treasury yield stood at 5.15%.
History is for reference only. In the short term, watch the $62,000 level and the $60,000 options support flagged by Wintermute. Whether a rebound materializes will depend on when funding conditions and interest rate expectations turn.
7
·
--
November’s biggest on-chain dip buyer “fires its last bullet”: $181 million spent, average price $1,906, current price now below cost
According to monitoring data, the biggest on-chain force buying the dip after ETH’s November decline used up all of its funds for this round of purchases 8 hours ago, officially bringing its dip-buying campaign to an end.
Over the past 6 days, this cluster of addresses spent a total of about $181 million to buy 95,020 ETH at an average price of $1,906. Its total ETH holdings rose to 649,649, valued at approximately $1.18 billion at the time of purchase.
But this “biggest spot buyer” did not get the price action it was hoping for. As of publication on November 18, ETH was trading at around $1,812–$1,825, below the whale’s average purchase price of $1,906, leaving the dip-buying position at an unrealized loss of about 4%–5%.
The pace of buying tells the same story: by November 17, the whale had bought a cumulative 82,277 ETH at an average price of $1,921, with only about 11 million USDT left in its addresses. A day later, its final funds were spent, bringing the average price down to $1,906—buying more as the price kept falling, until it could buy no more. The biggest marginal buyer has now disappeared, while ETH continues to trade below its cost basis. Where future spot-market demand will come from is a more important question to watch than whether “it will buy again.”
November’s biggest on-chain dip buyer “fires its last bullet”: $181 million spent, average price $1,906, current price now below cost
According to monitoring data, the biggest on-chain force buying the dip after ETH’s November decline used up all of its funds for this round of purchases 8 hours ago, officially bringing its dip-buying campaign to an end.
Over the past 6 days, this cluster of addresses spent a total of about $181 million to buy 95,020 ETH at an average price of $1,906. Its total ETH holdings rose to 649,649, valued at approximately $1.18 billion at the time of purchase.
But this “biggest spot buyer” did not get the price action it was hoping for. As of publication on November 18, ETH was trading at around $1,812–$1,825, below the whale’s average purchase price of $1,906, leaving the dip-buying position at an unrealized loss of about 4%–5%.
The pace of buying tells the same story: by November 17, the whale had bought a cumulative 82,277 ETH at an average price of $1,921, with only about 11 million USDT left in its addresses. A day later, its final funds were spent, bringing the average price down to $1,906—buying more as the price kept falling, until it could buy no more. The biggest marginal buyer has now disappeared, while ETH continues to trade below its cost basis. Where future spot-market demand will come from is a more important question to watch than whether “it will buy again.”
According to monitoring data, the biggest on-chain force buying the dip after ETH’s November decline used up all of its funds for this round of purchases 8 hours ago, officially bringing its dip-buying campaign to an end.
Over the past 6 days, this cluster of addresses spent a total of about $181 million to buy 95,020 ETH at an average price of $1,906. Its total ETH holdings rose to 649,649, valued at approximately $1.18 billion at the time of purchase.
But this “biggest spot buyer” did not get the price action it was hoping for. As of publication on November 18, ETH was trading at around $1,812–$1,825, below the whale’s average purchase price of $1,906, leaving the dip-buying position at an unrealized loss of about 4%–5%.
The pace of buying tells the same story: by November 17, the whale had bought a cumulative 82,277 ETH at an average price of $1,921, with only about 11 million USDT left in its addresses. A day later, its final funds were spent, bringing the average price down to $1,906—buying more as the price kept falling, until it could buy no more. The biggest marginal buyer has now disappeared, while ETH continues to trade below its cost basis. Where future spot-market demand will come from is a more important question to watch than whether “it will buy again.”
197
·
--
Bull and bear cycles come and go, but hackers are here to drain you before the shady market makers do! 🚨
Binance just weathered an epic attack, teamed up to recover $1.2 billion, and fully backstopped the losses. Then Kava Lend got hit because of an abandoned, unmonitored BUSD pool—hackers used it like an ATM and drained $3.7 million in $KAVA!
Stop using your hard-earned money as a tester for “high-risk, sketchy on-chain projects.” The crypto survival rule is brutal: a top-tier exchange might have your back, but an on-chain hack can wipe you out completely.
Want to protect your principal? Check these 3 survival rules right now:
1️⃣ Stay away from zombie pools: Old lending protocols with shrinking TVL and delisted tokens are prime targets for hackers.
2️⃣ Revoke old approvals: If a sketchy project you interacted with six months ago blows up, the U in your wallet could be swiped in seconds.
3️⃣ Keep wallets strictly separated: Never connect your main wallet holding $BTC / $BNB to any DApp. Use a separate burner wallet for risky projects and airdrops!
💬 Honestly, how long has it been since you cleaned up your wallet approvals? Tell us in the comments! 👇
#DeFi安全 #钱包安全 $KAVA
Bull and bear cycles come and go, but hackers are here to drain you before the shady market makers do! 🚨
Binance just weathered an epic attack, teamed up to recover $1.2 billion, and fully backstopped the losses. Then Kava Lend got hit because of an abandoned, unmonitored BUSD pool—hackers used it like an ATM and drained $3.7 million in $KAVA !
Stop using your hard-earned money as a tester for “high-risk, sketchy on-chain projects.” The crypto survival rule is brutal: a top-tier exchange might have your back, but an on-chain hack can wipe you out completely.
Want to protect your principal? Check these 3 survival rules right now:
1️⃣ Stay away from zombie pools: Old lending protocols with shrinking TVL and delisted tokens are prime targets for hackers.
2️⃣ Revoke old approvals: If a sketchy project you interacted with six months ago blows up, the U in your wallet could be swiped in seconds.
3️⃣ Keep wallets strictly separated: Never connect your main wallet holding $BTC / $BNB to any DApp. Use a separate burner wallet for risky projects and airdrops!
💬 Honestly, how long has it been since you cleaned up your wallet approvals? Tell us in the comments! 👇
#DeFi安全 #钱包安全 $KAVA
Binance just weathered an epic attack, teamed up to recover $1.2 billion, and fully backstopped the losses. Then Kava Lend got hit because of an abandoned, unmonitored BUSD pool—hackers used it like an ATM and drained $3.7 million in $KAVA !
Stop using your hard-earned money as a tester for “high-risk, sketchy on-chain projects.” The crypto survival rule is brutal: a top-tier exchange might have your back, but an on-chain hack can wipe you out completely.
Want to protect your principal? Check these 3 survival rules right now:
1️⃣ Stay away from zombie pools: Old lending protocols with shrinking TVL and delisted tokens are prime targets for hackers.
2️⃣ Revoke old approvals: If a sketchy project you interacted with six months ago blows up, the U in your wallet could be swiped in seconds.
3️⃣ Keep wallets strictly separated: Never connect your main wallet holding $BTC / $BNB to any DApp. Use a separate burner wallet for risky projects and airdrops!
💬 Honestly, how long has it been since you cleaned up your wallet approvals? Tell us in the comments! 👇
#DeFi安全 #钱包安全 $KAVA
296
·
--
LINK falls below $9.2 as whale withdraws nearly 240,000 tokens from Binance in three days, accelerating accumulation
According to monitoring data, a whale address withdrew a total of 238,380 LINK from Binance over the past two days, worth approximately $2.2 million. The latest withdrawal was 12,140 LINK (about $111,880), with all withdrawals coming from the exchange.
This was not an isolated move. On November 15, the same whale had already withdrawn 145,580 LINK from Binance within 24 hours (worth about $1.34 million at the time), which on-chain analysts characterized as “accumulation.” Two days later, the total had risen to 238,000 LINK, indicating that the pace of withdrawals had not slowed—instead, it accelerated as LINK’s price slid further from around $9.2 to $9.1.
LINK is currently trading at around $9.18, down more than 11% for the week. Its price is below the EMA50 and EMA200, pointing to a bearish trend structure. However, the 4-hour RSI is in neutral territory, the MACD has formed a golden cross, and the daily price is tracking close to the lower Bollinger Band. At this “weak but near technical support” level, the whale has continued moving tokens off the exchange into self-custody, going against the short-term price trend. Withdrawals alone do not constitute a commitment to buy, but three consecutive days of countertrend accumulation at least suggest that this holder has not been shaken by the market’s short-term weakness.
LINK falls below $9.2 as whale withdraws nearly 240,000 tokens from Binance in three days, accelerating accumulation
According to monitoring data, a whale address withdrew a total of 238,380 LINK from Binance over the past two days, worth approximately $2.2 million. The latest withdrawal was 12,140 LINK (about $111,880), with all withdrawals coming from the exchange.
This was not an isolated move. On November 15, the same whale had already withdrawn 145,580 LINK from Binance within 24 hours (worth about $1.34 million at the time), which on-chain analysts characterized as “accumulation.” Two days later, the total had risen to 238,000 LINK, indicating that the pace of withdrawals had not slowed—instead, it accelerated as LINK’s price slid further from around $9.2 to $9.1.
LINK is currently trading at around $9.18, down more than 11% for the week. Its price is below the EMA50 and EMA200, pointing to a bearish trend structure. However, the 4-hour RSI is in neutral territory, the MACD has formed a golden cross, and the daily price is tracking close to the lower Bollinger Band. At this “weak but near technical support” level, the whale has continued moving tokens off the exchange into self-custody, going against the short-term price trend. Withdrawals alone do not constitute a commitment to buy, but three consecutive days of countertrend accumulation at least suggest that this holder has not been shaken by the market’s short-term weakness.
According to monitoring data, a whale address withdrew a total of 238,380 LINK from Binance over the past two days, worth approximately $2.2 million. The latest withdrawal was 12,140 LINK (about $111,880), with all withdrawals coming from the exchange.
This was not an isolated move. On November 15, the same whale had already withdrawn 145,580 LINK from Binance within 24 hours (worth about $1.34 million at the time), which on-chain analysts characterized as “accumulation.” Two days later, the total had risen to 238,000 LINK, indicating that the pace of withdrawals had not slowed—instead, it accelerated as LINK’s price slid further from around $9.2 to $9.1.
LINK is currently trading at around $9.18, down more than 11% for the week. Its price is below the EMA50 and EMA200, pointing to a bearish trend structure. However, the 4-hour RSI is in neutral territory, the MACD has formed a golden cross, and the daily price is tracking close to the lower Bollinger Band. At this “weak but near technical support” level, the whale has continued moving tokens off the exchange into self-custody, going against the short-term price trend. Withdrawals alone do not constitute a commitment to buy, but three consecutive days of countertrend accumulation at least suggest that this holder has not been shaken by the market’s short-term weakness.
11
·
--
Article
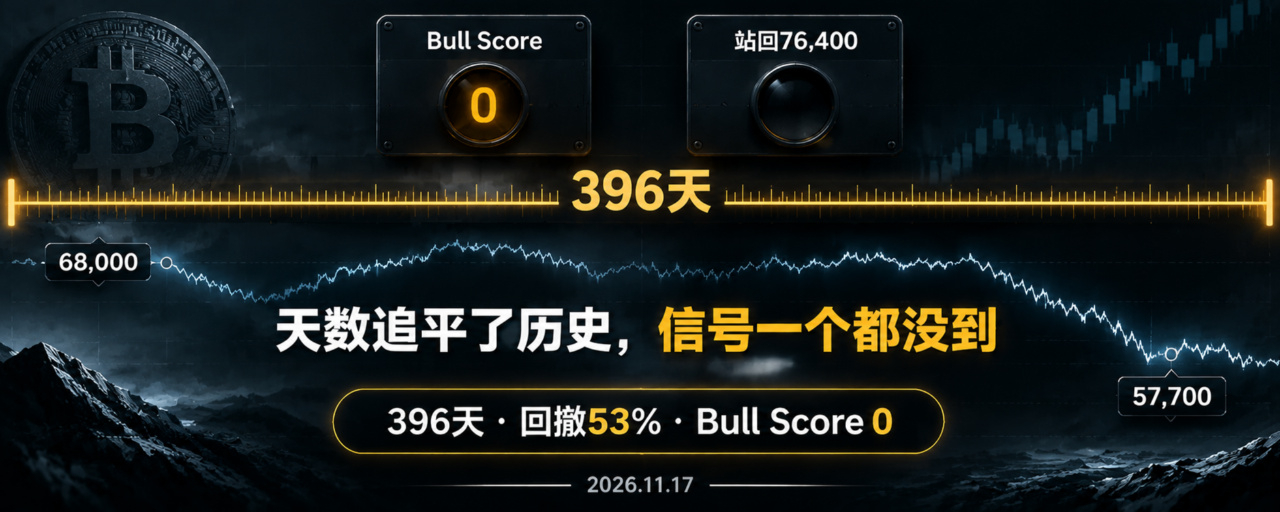
396 days have passed, but the timer isn’t governed by the number of daysIn early November, the founder of CryptoBoost shared a widely cited figure: as of the time of writing, the current bear market had lasted 396 days since the all-time high on October 6, 2025—slightly longer than the average 391 days it has taken bear markets to bottom since 2014. The drawdown is about 53%, while the maximum declines in the 2014, 2018, and 2022 bear markets were 86%, 84%, and 77%, respectively.
The time dimension gives us one coordinate: the window has opened. But a coordinate is not the answer. The number of days only tells us that “enough time has passed,” not that “the bottom is in.”
What makes this bear market unusual: it hasn’t fallen far enough
396 days have passed, but the timer isn’t governed by the number of days
In early November, the founder of CryptoBoost shared a widely cited figure: as of the time of writing, the current bear market had lasted 396 days since the all-time high on October 6, 2025—slightly longer than the average 391 days it has taken bear markets to bottom since 2014. The drawdown is about 53%, while the maximum declines in the 2014, 2018, and 2022 bear markets were 86%, 84%, and 77%, respectively.
The time dimension gives us one coordinate: the window has opened. But a coordinate is not the answer. The number of days only tells us that “enough time has passed,” not that “the bottom is in.”
What makes this bear market unusual: it hasn’t fallen far enough
The time dimension gives us one coordinate: the window has opened. But a coordinate is not the answer. The number of days only tells us that “enough time has passed,” not that “the bottom is in.”
What makes this bear market unusual: it hasn’t fallen far enough
45
·
--
Bloomberg: Bitcoin’s “slow bleed” shatters confidence, briefly hitting $62,022 for its lowest level since July
Bitcoin’s weekend performance made “exhaustion” and “despair” the key words for market sentiment.
Unlike previous sharp crashes marked by sudden plunges, this downturn built gradually amid relatively calm trading at first. It was only after large-scale forced liquidations emerged recently that the decline accelerated noticeably. Bitcoin fell 5.7% during U.S. trading hours on Saturday, then slid further during Asian trading on Sunday, briefly hitting $62,022—its lowest level since July 14—before stabilizing near $65,000 early Monday in Asia. Over the past month, #比特币 has fallen by more than 20% in total.
Macroeconomic pressures have not eased. The yield on 10-year U.S. Treasury bonds has risen above 5%, the dollar has strengthened, and persistent inflation data have reinforced expectations that the Federal Reserve will maintain its restrictive stance. Rising interest rates directly increase the opportunity cost of holding non-yielding assets such as Bitcoin.
More noteworthy is that U.S. spot Bitcoin ETFs, previously seen as a “pillar of buying support,” recorded nearly $3 billion in net outflows from October 30 to November 13. In the framing of Bloomberg’s original article, they have shifted from a source of demand to part of the source of selling pressure.
Market analysts believe that the near-term direction depends largely on whether institutional demand can stabilize and whether the macroeconomic environment allows risk appetite to recover. Until both conditions are met, any rebound may be fragile, and volatility is expected to remain elevated.
All financial markets are currently in a risk-off environment, and Bitcoin’s latest decline has erased most of its previous gains, when it rebounded from below $65,000 to above $87,000. The market’s next concern is whether it will fall further below this year’s low of around $58,000. As of publication, sentiment indicators remain in the extreme fear zone, and confidence may take longer to recover than prices take to stabilize.
Bloomberg: Bitcoin’s “slow bleed” shatters confidence, briefly hitting $62,022 for its lowest level since July
Bitcoin’s weekend performance made “exhaustion” and “despair” the key words for market sentiment.
Unlike previous sharp crashes marked by sudden plunges, this downturn built gradually amid relatively calm trading at first. It was only after large-scale forced liquidations emerged recently that the decline accelerated noticeably. Bitcoin fell 5.7% during U.S. trading hours on Saturday, then slid further during Asian trading on Sunday, briefly hitting $62,022—its lowest level since July 14—before stabilizing near $65,000 early Monday in Asia. Over the past month, #比特币 has fallen by more than 20% in total.
Macroeconomic pressures have not eased. The yield on 10-year U.S. Treasury bonds has risen above 5%, the dollar has strengthened, and persistent inflation data have reinforced expectations that the Federal Reserve will maintain its restrictive stance. Rising interest rates directly increase the opportunity cost of holding non-yielding assets such as Bitcoin.
More noteworthy is that U.S. spot Bitcoin ETFs, previously seen as a “pillar of buying support,” recorded nearly $3 billion in net outflows from October 30 to November 13. In the framing of Bloomberg’s original article, they have shifted from a source of demand to part of the source of selling pressure.
Market analysts believe that the near-term direction depends largely on whether institutional demand can stabilize and whether the macroeconomic environment allows risk appetite to recover. Until both conditions are met, any rebound may be fragile, and volatility is expected to remain elevated.
All financial markets are currently in a risk-off environment, and Bitcoin’s latest decline has erased most of its previous gains, when it rebounded from below $65,000 to above $87,000. The market’s next concern is whether it will fall further below this year’s low of around $58,000. As of publication, sentiment indicators remain in the extreme fear zone, and confidence may take longer to recover than prices take to stabilize.
Bitcoin’s weekend performance made “exhaustion” and “despair” the key words for market sentiment.
Unlike previous sharp crashes marked by sudden plunges, this downturn built gradually amid relatively calm trading at first. It was only after large-scale forced liquidations emerged recently that the decline accelerated noticeably. Bitcoin fell 5.7% during U.S. trading hours on Saturday, then slid further during Asian trading on Sunday, briefly hitting $62,022—its lowest level since July 14—before stabilizing near $65,000 early Monday in Asia. Over the past month, #比特币 has fallen by more than 20% in total.
Macroeconomic pressures have not eased. The yield on 10-year U.S. Treasury bonds has risen above 5%, the dollar has strengthened, and persistent inflation data have reinforced expectations that the Federal Reserve will maintain its restrictive stance. Rising interest rates directly increase the opportunity cost of holding non-yielding assets such as Bitcoin.
More noteworthy is that U.S. spot Bitcoin ETFs, previously seen as a “pillar of buying support,” recorded nearly $3 billion in net outflows from October 30 to November 13. In the framing of Bloomberg’s original article, they have shifted from a source of demand to part of the source of selling pressure.
Market analysts believe that the near-term direction depends largely on whether institutional demand can stabilize and whether the macroeconomic environment allows risk appetite to recover. Until both conditions are met, any rebound may be fragile, and volatility is expected to remain elevated.
All financial markets are currently in a risk-off environment, and Bitcoin’s latest decline has erased most of its previous gains, when it rebounded from below $65,000 to above $87,000. The market’s next concern is whether it will fall further below this year’s low of around $58,000. As of publication, sentiment indicators remain in the extreme fear zone, and confidence may take longer to recover than prices take to stabilize.
41
·
--
Whale splits funds after withdrawing 415 BTC from exchanges: 8.38 million USD sent to Binance, 240 BTC moved to an old wallet for safekeeping
Against a backdrop of BTC fluctuating around $65,000 and market sentiment sinking into “extreme fear,” on-chain monitors detected a large whale transaction.
Over the past three days, a whale withdrew a total of 415 BTC (approximately $28.78 million) from exchanges. The address then split the funds into two paths: 130 BTC (approximately $8.38 million) was sent directly to Binance, a move that typically signals potential selling intent in on-chain activity; another 240 BTC (approximately $15.48 million) was transferred to a new wallet.
Notably, the new wallet that received the 240 BTC now holds 868.73 BTC (approximately $56.36 million). This balance suggests that the wallet is not a temporary intermediary, but rather an address with an existing position that is receiving consolidated funds. Overall, the transaction moved a total of 370 BTC (approximately $23.86 million), reflecting a split pattern in which some holdings flowed to an exchange while others were stored in a cold wallet, rather than a one-off, full liquidation-style transfer.
Whale splits funds after withdrawing 415 BTC from exchanges: 8.38 million USD sent to Binance, 240 BTC moved to an old wallet for safekeeping
Against a backdrop of BTC fluctuating around $65,000 and market sentiment sinking into “extreme fear,” on-chain monitors detected a large whale transaction.
Over the past three days, a whale withdrew a total of 415 BTC (approximately $28.78 million) from exchanges. The address then split the funds into two paths: 130 BTC (approximately $8.38 million) was sent directly to Binance, a move that typically signals potential selling intent in on-chain activity; another 240 BTC (approximately $15.48 million) was transferred to a new wallet.
Notably, the new wallet that received the 240 BTC now holds 868.73 BTC (approximately $56.36 million). This balance suggests that the wallet is not a temporary intermediary, but rather an address with an existing position that is receiving consolidated funds. Overall, the transaction moved a total of 370 BTC (approximately $23.86 million), reflecting a split pattern in which some holdings flowed to an exchange while others were stored in a cold wallet, rather than a one-off, full liquidation-style transfer.
Against a backdrop of BTC fluctuating around $65,000 and market sentiment sinking into “extreme fear,” on-chain monitors detected a large whale transaction.
Over the past three days, a whale withdrew a total of 415 BTC (approximately $28.78 million) from exchanges. The address then split the funds into two paths: 130 BTC (approximately $8.38 million) was sent directly to Binance, a move that typically signals potential selling intent in on-chain activity; another 240 BTC (approximately $15.48 million) was transferred to a new wallet.
Notably, the new wallet that received the 240 BTC now holds 868.73 BTC (approximately $56.36 million). This balance suggests that the wallet is not a temporary intermediary, but rather an address with an existing position that is receiving consolidated funds. Overall, the transaction moved a total of 370 BTC (approximately $23.86 million), reflecting a split pattern in which some holdings flowed to an exchange while others were stored in a cold wallet, rather than a one-off, full liquidation-style transfer.
60
·
--
Article
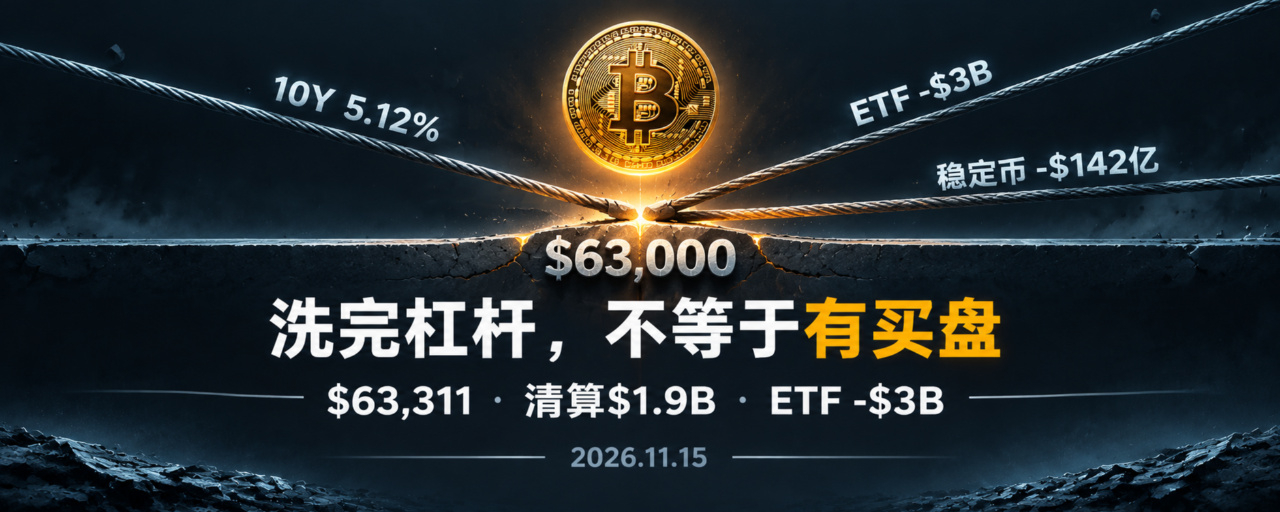
$63,000: Three Lines Tightened at OnceSummary: BTC has fallen about 25% since October 21, briefly touching $63,311 over the weekend; the 10-year U.S. Treasury yield rose to 5.12%, nearly $3 billion flowed out of ETFs over two weeks, and stablecoin supply shrank by $14.2 billion over 30 days—all three tightened within the same window.
On November 15, Bitcoin fell further during weekend trading, hitting a low of $63,311, its weakest level since August 17; Ethereum dropped to $1,731, its lowest since July 9. Bitcoin has fallen about 25% since October 21. Liquidations across the crypto market totaled about $1.9 billion over 24 hours, including $684 million in Bitcoin and $466 million in Ethereum, with the vast majority involving long positions.
$63,000: Three Lines Tightened at Once
Summary: BTC has fallen about 25% since October 21, briefly touching $63,311 over the weekend; the 10-year U.S. Treasury yield rose to 5.12%, nearly $3 billion flowed out of ETFs over two weeks, and stablecoin supply shrank by $14.2 billion over 30 days—all three tightened within the same window.
On November 15, Bitcoin fell further during weekend trading, hitting a low of $63,311, its weakest level since August 17; Ethereum dropped to $1,731, its lowest since July 9. Bitcoin has fallen about 25% since October 21. Liquidations across the crypto market totaled about $1.9 billion over 24 hours, including $684 million in Bitcoin and $466 million in Ethereum, with the vast majority involving long positions.
On November 15, Bitcoin fell further during weekend trading, hitting a low of $63,311, its weakest level since August 17; Ethereum dropped to $1,731, its lowest since July 9. Bitcoin has fallen about 25% since October 21. Liquidations across the crypto market totaled about $1.9 billion over 24 hours, including $684 million in Bitcoin and $466 million in Ethereum, with the vast majority involving long positions.
66
·
--
Article
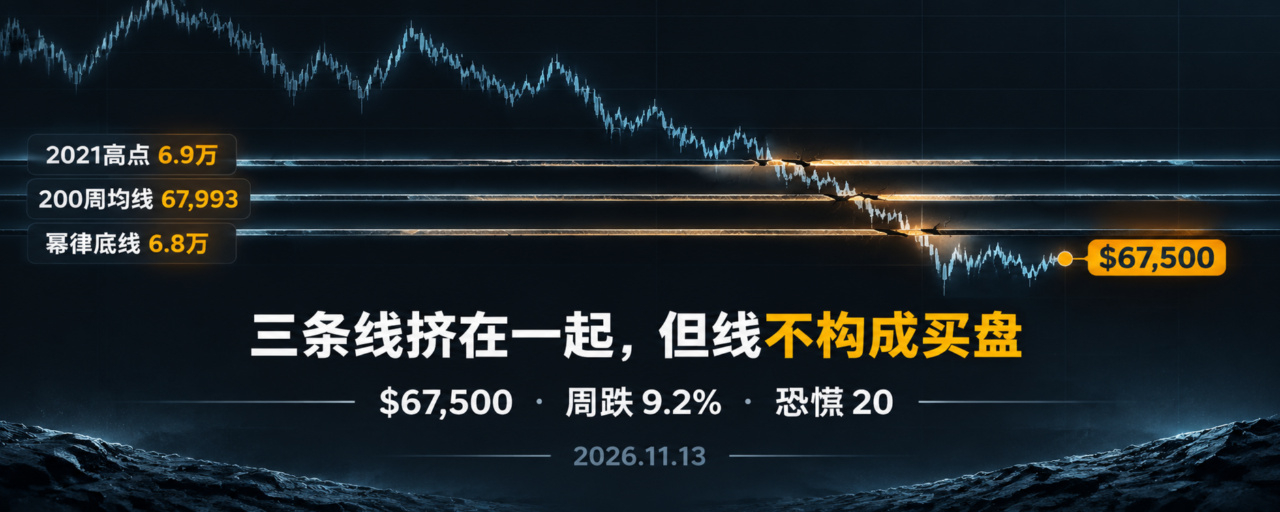
Three lines of defense, each thinner than the lastOn November 13, Bitcoin lost the $72,000 and $70,000 levels one after the other within 48 hours, hitting an intraday low of $67,500. Its weekly loss widened to 9.2%, wiping nearly $200 billion off the crypto market’s total value. The Fear and Greed Index plunged to 20, entering “Extreme Fear” territory and hitting its lowest level in more than four months.
This is no ordinary pullback. The price has fallen into an area that has been repeatedly marked on the charts but never seriously tested.
$67,000–$69,000: Three lines converge at the same point
The most critical area right now is $67,000–$69,000. Three lines of different kinds converge here, but they all point to the same question: are buyers still willing to step in at this level?
Three lines of defense, each thinner than the last
On November 13, Bitcoin lost the $72,000 and $70,000 levels one after the other within 48 hours, hitting an intraday low of $67,500. Its weekly loss widened to 9.2%, wiping nearly $200 billion off the crypto market’s total value. The Fear and Greed Index plunged to 20, entering “Extreme Fear” territory and hitting its lowest level in more than four months.
This is no ordinary pullback. The price has fallen into an area that has been repeatedly marked on the charts but never seriously tested.
$67,000–$69,000: Three lines converge at the same point
The most critical area right now is $67,000–$69,000. Three lines of different kinds converge here, but they all point to the same question: are buyers still willing to step in at this level?
This is no ordinary pullback. The price has fallen into an area that has been repeatedly marked on the charts but never seriously tested.
$67,000–$69,000: Three lines converge at the same point
The most critical area right now is $67,000–$69,000. Three lines of different kinds converge here, but they all point to the same question: are buyers still willing to step in at this level?
59
·
--
Article
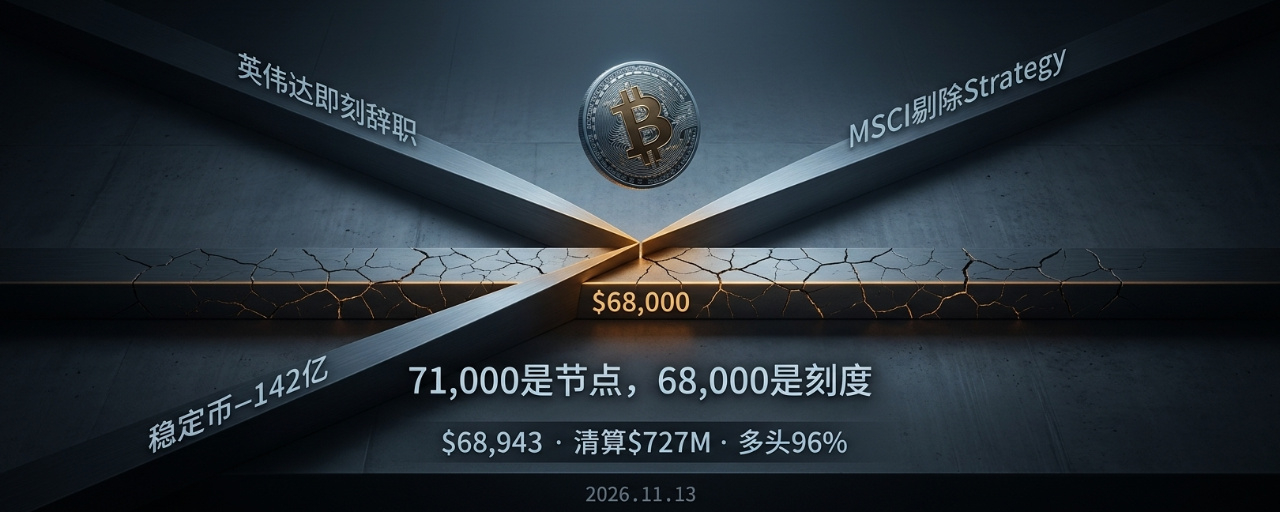
$71,000 Is Not the Bottom; $68,000 Is the BenchmarkSummary: BTC fell below $70,000 in early Asian trading, touching $68,943; 24-hour liquidations exceeded $620 million, with longs accounting for 96%. Nvidia’s immediate resignation, MSCI’s removal of Strategy, and a $14.2 billion decline in stablecoins over 30 days all converged on the same day.
On November 13, Bitcoin fell below the key $70,000 level in early Asian trading, hitting an intraday low of $68,943, down about 6% from 24 hours earlier and marking its lowest level since August. Ethereum also fell below $2,000, trading near $1,961.
The 24-hour liquidation volume across the market was approximately $622 million to $727 million, with longs accounting for as much as 96%–97%. The largest single liquidation was a $31 million BTC long on Hyperliquid, with the liquidation price near $72,250—well before the price reached the $70,000 level.
$71,000 Is Not the Bottom; $68,000 Is the Benchmark
Summary: BTC fell below $70,000 in early Asian trading, touching $68,943; 24-hour liquidations exceeded $620 million, with longs accounting for 96%. Nvidia’s immediate resignation, MSCI’s removal of Strategy, and a $14.2 billion decline in stablecoins over 30 days all converged on the same day.
On November 13, Bitcoin fell below the key $70,000 level in early Asian trading, hitting an intraday low of $68,943, down about 6% from 24 hours earlier and marking its lowest level since August. Ethereum also fell below $2,000, trading near $1,961.
The 24-hour liquidation volume across the market was approximately $622 million to $727 million, with longs accounting for as much as 96%–97%. The largest single liquidation was a $31 million BTC long on Hyperliquid, with the liquidation price near $72,250—well before the price reached the $70,000 level.
On November 13, Bitcoin fell below the key $70,000 level in early Asian trading, hitting an intraday low of $68,943, down about 6% from 24 hours earlier and marking its lowest level since August. Ethereum also fell below $2,000, trading near $1,961.
The 24-hour liquidation volume across the market was approximately $622 million to $727 million, with longs accounting for as much as 96%–97%. The largest single liquidation was a $31 million BTC long on Hyperliquid, with the liquidation price near $72,250—well before the price reached the $70,000 level.
408
·
--
Article
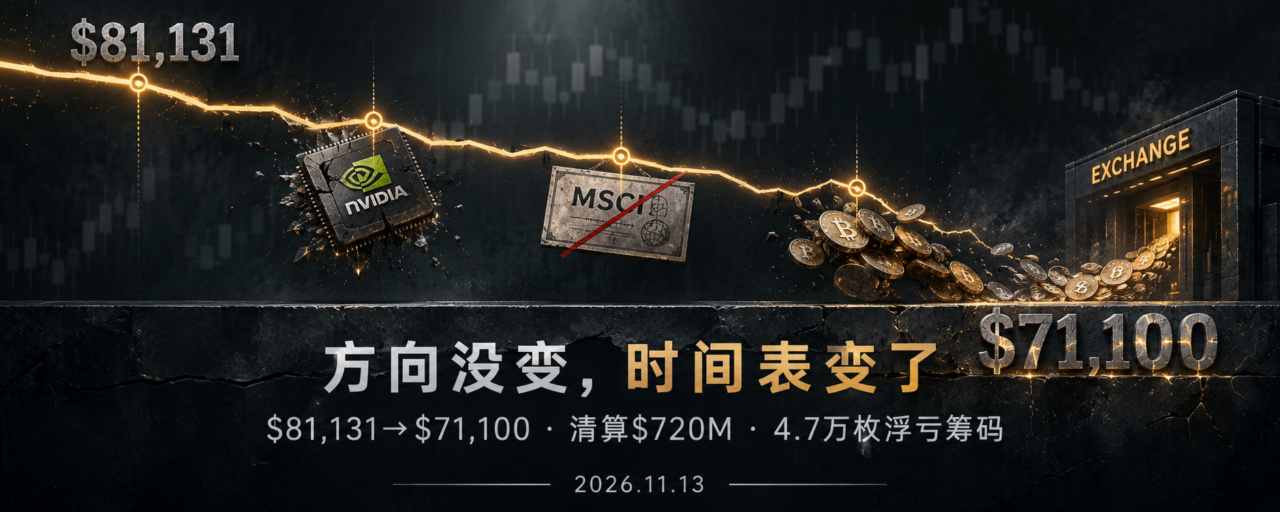
$71,100: Three New Factors This WeekSummary: BTC fell from $81,131 to $71,100 this week. CPI, leverage unwinding, and ETF outflows were part of the existing backdrop; Nvidia’s CEO resignation becoming official, Strategy’s removal from MSCI, and 47,000 coins held at a loss moving to exchanges were new developments this week.
On November 13, Bitcoin briefly fell to $71,100 intraday, its lowest level in about 12 weeks. Just a week earlier, it was still above $81,000.
From 81,131 to 71,100, a drop of about 12%. The factors driving yields to 5%—CPI, leverage unwinding, and continued ETF redemptions—had already been repeatedly priced in. They form the underlying backdrop to this downturn and need no further discussion. What was truly new this week were three factors that hadn’t been present before.
$71,100: Three New Factors This Week
Summary: BTC fell from $81,131 to $71,100 this week. CPI, leverage unwinding, and ETF outflows were part of the existing backdrop; Nvidia’s CEO resignation becoming official, Strategy’s removal from MSCI, and 47,000 coins held at a loss moving to exchanges were new developments this week.
On November 13, Bitcoin briefly fell to $71,100 intraday, its lowest level in about 12 weeks. Just a week earlier, it was still above $81,000.
From 81,131 to 71,100, a drop of about 12%. The factors driving yields to 5%—CPI, leverage unwinding, and continued ETF redemptions—had already been repeatedly priced in. They form the underlying backdrop to this downturn and need no further discussion. What was truly new this week were three factors that hadn’t been present before.
On November 13, Bitcoin briefly fell to $71,100 intraday, its lowest level in about 12 weeks. Just a week earlier, it was still above $81,000.
From 81,131 to 71,100, a drop of about 12%. The factors driving yields to 5%—CPI, leverage unwinding, and continued ETF redemptions—had already been repeatedly priced in. They form the underlying backdrop to this downturn and need no further discussion. What was truly new this week were three factors that hadn’t been present before.
323
·
--
F2Pool co-founder Wang Chun sells high and buys back low: sold near the peak, bought back about two-thirds at lower prices
On-chain records show that F2Pool co-founder Wang Chun (@satofishi) recently completed a swing trade.
A week ago, when ETH was around $2,390, he sold 6,200 wstETH (equivalent to 7,740 ETH), cashing out $18.5 million.
The market then declined. Over the past two days, he bought back 5,246 ETH at an average price of $2,054, spending about $10.78 million. He did not fully replenish his position, buying back about two-thirds of it. His net holdings decreased by about 2,494 ETH equivalent, leaving him with roughly $7.72 million in cash.
Additionally, on November 11, he staked 3,996 ETH (about $8.23 million) with Lido and deposited it into the Spark protocol, earning yield in parallel.
ETH is currently trading at around $2,049, slightly below his $2,054 average buyback price. The portion he bought back is showing a small unrealized loss, but his cost basis remains significantly better than the price at which he sold near the peak a week ago.
F2Pool co-founder Wang Chun sells high and buys back low: sold near the peak, bought back about two-thirds at lower prices
On-chain records show that F2Pool co-founder Wang Chun (@satofishi) recently completed a swing trade.
A week ago, when ETH was around $2,390, he sold 6,200 wstETH (equivalent to 7,740 ETH), cashing out $18.5 million.
The market then declined. Over the past two days, he bought back 5,246 ETH at an average price of $2,054, spending about $10.78 million. He did not fully replenish his position, buying back about two-thirds of it. His net holdings decreased by about 2,494 ETH equivalent, leaving him with roughly $7.72 million in cash.
Additionally, on November 11, he staked 3,996 ETH (about $8.23 million) with Lido and deposited it into the Spark protocol, earning yield in parallel.
ETH is currently trading at around $2,049, slightly below his $2,054 average buyback price. The portion he bought back is showing a small unrealized loss, but his cost basis remains significantly better than the price at which he sold near the peak a week ago.
On-chain records show that F2Pool co-founder Wang Chun (@satofishi) recently completed a swing trade.
A week ago, when ETH was around $2,390, he sold 6,200 wstETH (equivalent to 7,740 ETH), cashing out $18.5 million.
The market then declined. Over the past two days, he bought back 5,246 ETH at an average price of $2,054, spending about $10.78 million. He did not fully replenish his position, buying back about two-thirds of it. His net holdings decreased by about 2,494 ETH equivalent, leaving him with roughly $7.72 million in cash.
Additionally, on November 11, he staked 3,996 ETH (about $8.23 million) with Lido and deposited it into the Spark protocol, earning yield in parallel.
ETH is currently trading at around $2,049, slightly below his $2,054 average buyback price. The portion he bought back is showing a small unrealized loss, but his cost basis remains significantly better than the price at which he sold near the peak a week ago.
144
·
--
Article
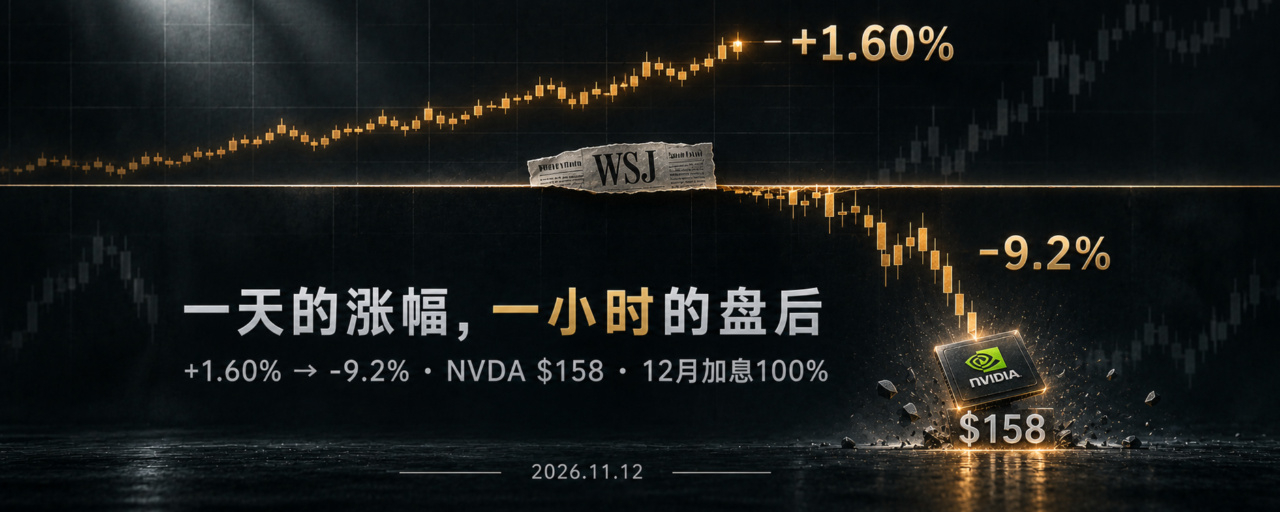
An hour after the close wiped out a day’s gainsDuring Wednesday’s regular trading session, AI trading seemed to be back on track. CoreWeave ignited the entire computing-power chain with an earnings report that beat expectations. The Philadelphia Semiconductor Index rose 5.66%, with all 30 constituents advancing; the Nasdaq closed up 1.60% at 25,466.19, recovering all the ground it had lost since the midterm elections. Nvidia itself also rose 2.87%, closing at $173.73.
About an hour after the close, everything reversed.
The Wall Street Journal, citing people familiar with the matter, reported that Nvidia’s board is preparing to remove CEO Jensen Huang. It could meet as early as Wednesday to decide his fate, but as of the time of the report, no decision had been announced, nor had an interim CEO or successor been named. Nvidia shares plunged after hours, at one point falling 9.2% and touching a range of $157.75 to $159.59, down about 8% to 9% from the closing price. Nasdaq 100 futures fell about 1% in tandem, while the Philadelphia Semiconductor ETF dropped nearly 2% after hours.
An hour after the close wiped out a day’s gains
During Wednesday’s regular trading session, AI trading seemed to be back on track. CoreWeave ignited the entire computing-power chain with an earnings report that beat expectations. The Philadelphia Semiconductor Index rose 5.66%, with all 30 constituents advancing; the Nasdaq closed up 1.60% at 25,466.19, recovering all the ground it had lost since the midterm elections. Nvidia itself also rose 2.87%, closing at $173.73.
About an hour after the close, everything reversed.
The Wall Street Journal, citing people familiar with the matter, reported that Nvidia’s board is preparing to remove CEO Jensen Huang. It could meet as early as Wednesday to decide his fate, but as of the time of the report, no decision had been announced, nor had an interim CEO or successor been named. Nvidia shares plunged after hours, at one point falling 9.2% and touching a range of $157.75 to $159.59, down about 8% to 9% from the closing price. Nasdaq 100 futures fell about 1% in tandem, while the Philadelphia Semiconductor ETF dropped nearly 2% after hours.
About an hour after the close, everything reversed.
The Wall Street Journal, citing people familiar with the matter, reported that Nvidia’s board is preparing to remove CEO Jensen Huang. It could meet as early as Wednesday to decide his fate, but as of the time of the report, no decision had been announced, nor had an interim CEO or successor been named. Nvidia shares plunged after hours, at one point falling 9.2% and touching a range of $157.75 to $159.59, down about 8% to 9% from the closing price. Nasdaq 100 futures fell about 1% in tandem, while the Philadelphia Semiconductor ETF dropped nearly 2% after hours.
2
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BTCReboundsAbove$60KAmidWhaleDipBuying
51,259 views
271 Discussing
Abraxas Capital, Other Whales Buy the BTC Dip as Bitcoin Briefly Reclaims $60,000
Binance News
·31 Likes
·59.9k views
SolanaSets2027RoadmapToDoubleComputeCapacity
34,631 views
694 Discussing
CaliforniaNvidiaProbeExaminesPotentialCriminalViolations
9,397 views
98 Discussing