
StockLite_247
1.7k Posts
StockLite_247
Report
Block User
Free Stock Market News ACCURATE, CONSISTENT, & RELIABLE || https://x.com/Yusty121 || Crypto first commentary with Marco Market Context
Open Trade
Frequent Trader
5.6 Years
7 Following
979 Followers
3.5K+ Liked
Posts
Portfolio
All
Quotes
Videos
PINNED
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
39
11
192
199.1k
PINNED
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
25
15
137
128.2k
·
--
Bullish
$ETH
Back at the big support level that has been tested multiple times over the past 3 years.
- October 2023 before the big rally
- April 2025 after the tariff crash right before Tom Lee & Bitmine pumped it up to $5K
- This summer 2026 before the big bounce
- Here we are
This is a key area and one I would want to see the bulls defend at all costs. Next support up would be that tariff low at ~$1350. Above, $1750 generally is the level where if price accepts back above it, we see a bigger move up.
$ETH
Back at the big support level that has been tested multiple times over the past 3 years.
- October 2023 before the big rally
- April 2025 after the tariff crash right before Tom Lee & Bitmine pumped it up to $5K
- This summer 2026 before the big bounce
- Here we are
This is a key area and one I would want to see the bulls defend at all costs. Next support up would be that tariff low at ~$1350. Above, $1750 generally is the level where if price accepts back above it, we see a bigger move up.
Back at the big support level that has been tested multiple times over the past 3 years.
- October 2023 before the big rally
- April 2025 after the tariff crash right before Tom Lee & Bitmine pumped it up to $5K
- This summer 2026 before the big bounce
- Here we are
This is a key area and one I would want to see the bulls defend at all costs. Next support up would be that tariff low at ~$1350. Above, $1750 generally is the level where if price accepts back above it, we see a bigger move up.
1
128
·
--
Bullish
Elon Musk raises a valid concern about the financing challenges facing the AI infrastructure industry.
However, I believe $NBIS is considerably better positioned to navigate these challenges.
Here is why:
1. Customer prepayments: In Q3, customer prepayments covered more than 100% of the associated CapEx on qualifying deals of at least one year, compared with 50–60% in Q2.
2. GPU pricing power: Rising GPU demand and limited availability have allowed Nebius to increase average GPU-hour pricing by over 20% QoQ. Higher selling prices improve revenue per unit of capacity, accelerate investment payback and strengthen cash generation.
3. Barriers to entry: Power availability, cooling, construction, permitting and GPU supply make it extremely difficult for new competitors to bring meaningful capacity online quickly. Existing operators like Nebius are better positioned to capture the supply shortage and growing demand.
4. Multiple revenue streams and capital-efficient expansion: Its Token Factory inference platform is approaching a multi-hundred-million-dollar run rate, with contract value growing 17x QoQ. Its asset-light expansion model also allows infrastructure partners to finance and own data centres while Nebius provides the technology, software and customer distribution.
5. Funding visibility: Management expects customer prepayments and asset-backed financing against existing investment-grade contracts to cover 75–85% of its projected $40–45B CapEx in 2027. Customer prepayments alone are expected to rise from $10B in 2026 to $17–20B in 2027.
Additionally, Nebius ended Q3 with $7.4B in cash and expects to reach pre-tax breakeven by the end of 2027.
There is a significant difference between companies struggling to finance AI infrastructure and companies whose customers are helping finance their expansion.
Elon Musk raises a valid concern about the financing challenges facing the AI infrastructure industry.
However, I believe $NBIS is considerably better positioned to navigate these challenges.
Here is why:
1. Customer prepayments: In Q3, customer prepayments covered more than 100% of the associated CapEx on qualifying deals of at least one year, compared with 50–60% in Q2.
2. GPU pricing power: Rising GPU demand and limited availability have allowed Nebius to increase average GPU-hour pricing by over 20% QoQ. Higher selling prices improve revenue per unit of capacity, accelerate investment payback and strengthen cash generation.
3. Barriers to entry: Power availability, cooling, construction, permitting and GPU supply make it extremely difficult for new competitors to bring meaningful capacity online quickly. Existing operators like Nebius are better positioned to capture the supply shortage and growing demand.
4. Multiple revenue streams and capital-efficient expansion: Its Token Factory inference platform is approaching a multi-hundred-million-dollar run rate, with contract value growing 17x QoQ. Its asset-light expansion model also allows infrastructure partners to finance and own data centres while Nebius provides the technology, software and customer distribution.
5. Funding visibility: Management expects customer prepayments and asset-backed financing against existing investment-grade contracts to cover 75–85% of its projected $40–45B CapEx in 2027. Customer prepayments alone are expected to rise from $10B in 2026 to $17–20B in 2027.
Additionally, Nebius ended Q3 with $7.4B in cash and expects to reach pre-tax breakeven by the end of 2027.
There is a significant difference between companies struggling to finance AI infrastructure and companies whose customers are helping finance their expansion.
However, I believe $NBIS is considerably better positioned to navigate these challenges.
Here is why:
1. Customer prepayments: In Q3, customer prepayments covered more than 100% of the associated CapEx on qualifying deals of at least one year, compared with 50–60% in Q2.
2. GPU pricing power: Rising GPU demand and limited availability have allowed Nebius to increase average GPU-hour pricing by over 20% QoQ. Higher selling prices improve revenue per unit of capacity, accelerate investment payback and strengthen cash generation.
3. Barriers to entry: Power availability, cooling, construction, permitting and GPU supply make it extremely difficult for new competitors to bring meaningful capacity online quickly. Existing operators like Nebius are better positioned to capture the supply shortage and growing demand.
4. Multiple revenue streams and capital-efficient expansion: Its Token Factory inference platform is approaching a multi-hundred-million-dollar run rate, with contract value growing 17x QoQ. Its asset-light expansion model also allows infrastructure partners to finance and own data centres while Nebius provides the technology, software and customer distribution.
5. Funding visibility: Management expects customer prepayments and asset-backed financing against existing investment-grade contracts to cover 75–85% of its projected $40–45B CapEx in 2027. Customer prepayments alone are expected to rise from $10B in 2026 to $17–20B in 2027.
Additionally, Nebius ended Q3 with $7.4B in cash and expects to reach pre-tax breakeven by the end of 2027.
There is a significant difference between companies struggling to finance AI infrastructure and companies whose customers are helping finance their expansion.
1
55
·
--
Bullish
If you have witnessed crypto drawdowns, stock market drawdowns will mean absolutely nothing to you.
$SOL crashed over 97% before going on a 36x run.
$DOGE dropped over 90% before delivering an incredible 591x rally.
That's the nature of investing. Sometimes the biggest opportunities emerge from the deepest drawdowns.
A 70% drop in $NBIS doesn't mean it still cannot deliver a 20x return for patient investors.
Price action tests conviction. Time rewards patience.
If you have witnessed crypto drawdowns, stock market drawdowns will mean absolutely nothing to you.
$SOL crashed over 97% before going on a 36x run.
$DOGE dropped over 90% before delivering an incredible 591x rally.
That's the nature of investing. Sometimes the biggest opportunities emerge from the deepest drawdowns.
A 70% drop in $NBIS doesn't mean it still cannot deliver a 20x return for patient investors.
Price action tests conviction. Time rewards patience.
$SOL crashed over 97% before going on a 36x run.
$DOGE dropped over 90% before delivering an incredible 591x rally.
That's the nature of investing. Sometimes the biggest opportunities emerge from the deepest drawdowns.
A 70% drop in $NBIS doesn't mean it still cannot deliver a 20x return for patient investors.
Price action tests conviction. Time rewards patience.
1
221
·
--
Bullish
As long as Arkady is the one piloting the affairs of $NBIS , I have zero doubts about what this company can become over the next couple of years.
Not even an Elon Musk gig will shake me out.
He has built something extraordinary from nothing before, and he can do it again. Many of you don't even know this man well enough. Go study his history and you'll understand what he's made of.
He is a winner.
As long as Arkady is the one piloting the affairs of $NBIS , I have zero doubts about what this company can become over the next couple of years.
Not even an Elon Musk gig will shake me out.
He has built something extraordinary from nothing before, and he can do it again. Many of you don't even know this man well enough. Go study his history and you'll understand what he's made of.
He is a winner.
Not even an Elon Musk gig will shake me out.
He has built something extraordinary from nothing before, and he can do it again. Many of you don't even know this man well enough. Go study his history and you'll understand what he's made of.
He is a winner.
2
285
·
--
Bullish
Taiwan's stock market just suffered its worst week in 35 years with $TSM alone down 17%.
The selloff was so severe that Taiwan is now imposing its first blanket short selling restrictions since 2015 banning short sales below the previous close starting Monday.
Taiwan's stock market just suffered its worst week in 35 years with $TSM alone down 17%.
The selloff was so severe that Taiwan is now imposing its first blanket short selling restrictions since 2015 banning short sales below the previous close starting Monday.
The selloff was so severe that Taiwan is now imposing its first blanket short selling restrictions since 2015 banning short sales below the previous close starting Monday.
512
·
--
Bullish
Oppenheimer sees $ONDS revenue growing from $561M in 2026 to $2.6B by 2029 but bigger inflection is profitability with $184M in operating income and $245M in FCF even after acquisitions.
And there's already some visibility into that growth with $835M in backlog and management targeting at least $1.1B in 2027 revenue before additional acquisitions.
Also as the business scales you can see how gross margins are expected to reach 50% while operating costs fall from 69% to 30% of revenue potentially taking Ondas from relying on outside capital to fund growth to having the business finally fund itself.
There's obviously still plenty of execution risk between now and 2029 but with cash representing ~30% of its market cap the question is how much of that risk is already priced in.
Oppenheimer sees $ONDS revenue growing from $561M in 2026 to $2.6B by 2029 but bigger inflection is profitability with $184M in operating income and $245M in FCF even after acquisitions.
And there's already some visibility into that growth with $835M in backlog and management targeting at least $1.1B in 2027 revenue before additional acquisitions.
Also as the business scales you can see how gross margins are expected to reach 50% while operating costs fall from 69% to 30% of revenue potentially taking Ondas from relying on outside capital to fund growth to having the business finally fund itself.
There's obviously still plenty of execution risk between now and 2029 but with cash representing ~30% of its market cap the question is how much of that risk is already priced in.
And there's already some visibility into that growth with $835M in backlog and management targeting at least $1.1B in 2027 revenue before additional acquisitions.
Also as the business scales you can see how gross margins are expected to reach 50% while operating costs fall from 69% to 30% of revenue potentially taking Ondas from relying on outside capital to fund growth to having the business finally fund itself.
There's obviously still plenty of execution risk between now and 2029 but with cash representing ~30% of its market cap the question is how much of that risk is already priced in.
1
257
·
--
Bullish
$IREN is back to trading at roughly 1x book which is same valuation it carried as a Bitcoin miner with the market essentially saying its GPUs and data centers won't earn more than they cost despite its $MSFT contract.
Hard to reconcile that with $NVDA reporting Hopper GPUs recontracting ~2x their original rates and B300 rentals rising 60%+ especially when IREN's grid-connected power is still carried at historical cost despite becoming one of AI's scarcest assets.
$IREN is back to trading at roughly 1x book which is same valuation it carried as a Bitcoin miner with the market essentially saying its GPUs and data centers won't earn more than they cost despite its $MSFT contract.
Hard to reconcile that with $NVDA reporting Hopper GPUs recontracting ~2x their original rates and B300 rentals rising 60%+ especially when IREN's grid-connected power is still carried at historical cost despite becoming one of AI's scarcest assets.
Hard to reconcile that with $NVDA reporting Hopper GPUs recontracting ~2x their original rates and B300 rentals rising 60%+ especially when IREN's grid-connected power is still carried at historical cost despite becoming one of AI's scarcest assets.
1
448
·
--
Bullish
Tech just suffered its worst drawdown relative to the S&P 500 since 2003.
This is leverage getting unwound.
Tech just suffered its worst drawdown relative to the S&P 500 since 2003.
This is leverage getting unwound.
This is leverage getting unwound.
1
435
Verified
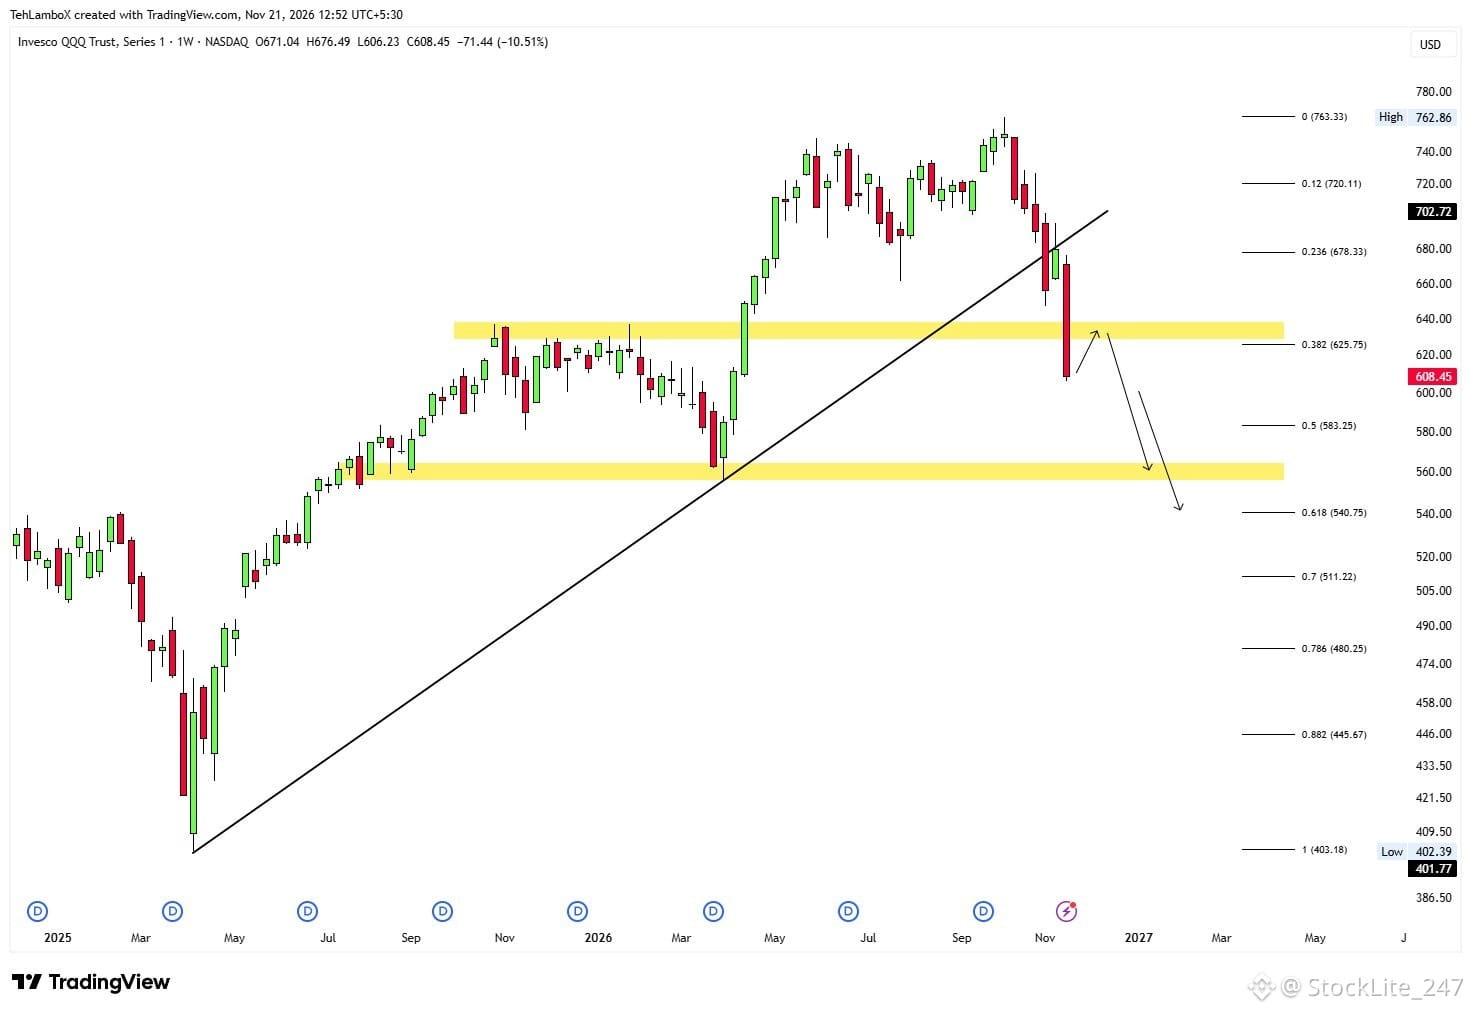
$QQQ THE MOST IMPORTANT UPDATE:
Earlier I thought a bounce from 625 would come.. It didnt and weekly closed below this massive zone without hesitation..
Now a bounce towards 625 should get a sell off and the next logical levels as support should be 583 and 540.. Looking at this chart, we are NOWHERE CLOSE TO THE BOTTOM YET!!
$QQQ THE MOST IMPORTANT UPDATE:
Earlier I thought a bounce from 625 would come.. It didnt and weekly closed below this massive zone without hesitation..
Now a bounce towards 625 should get a sell off and the next logical levels as support should be 583 and 540.. Looking at this chart, we are NOWHERE CLOSE TO THE BOTTOM YET!!
Earlier I thought a bounce from 625 would come.. It didnt and weekly closed below this massive zone without hesitation..
Now a bounce towards 625 should get a sell off and the next logical levels as support should be 583 and 540.. Looking at this chart, we are NOWHERE CLOSE TO THE BOTTOM YET!!
1
629
Disputed
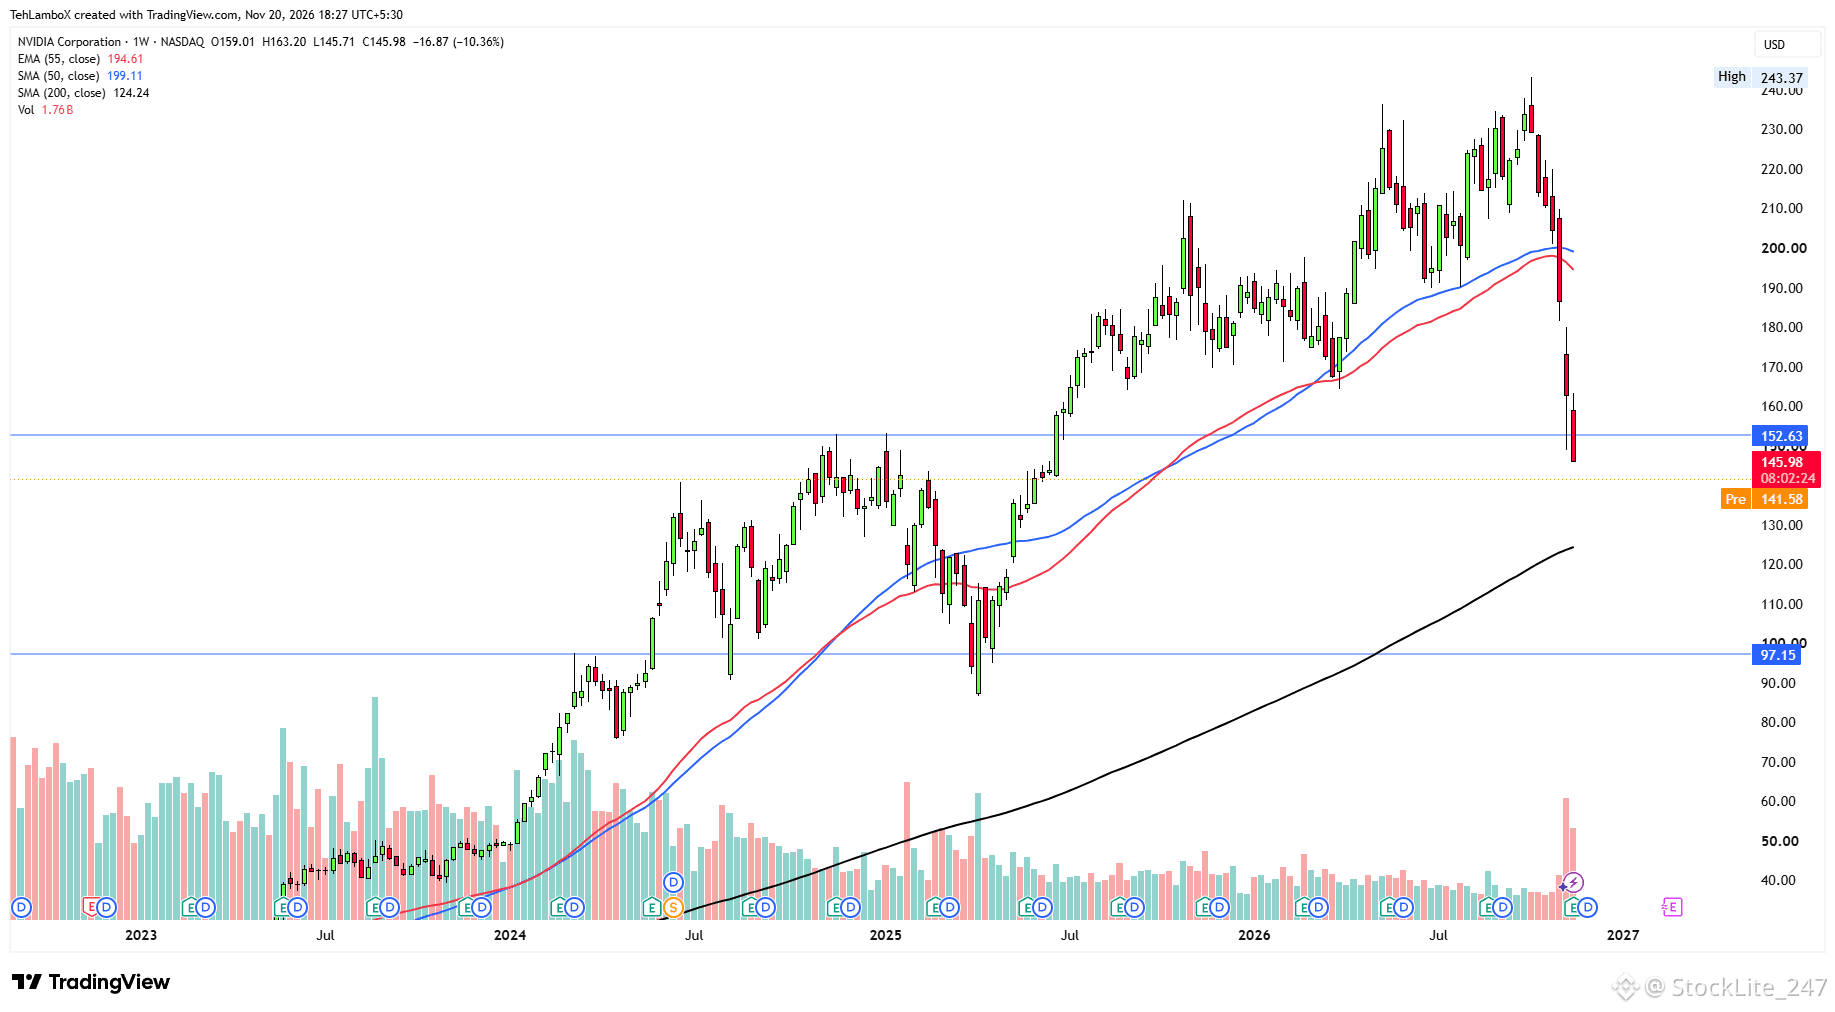
One more step closer to that SMA200 on weekly..
$NVDA is at 141 pre market.. This can try to close the weekly back above 150 here in all honesty.. so i would avoid shorting here..
One more step closer to that SMA200 on weekly..
$NVDA is at 141 pre market.. This can try to close the weekly back above 150 here in all honesty.. so i would avoid shorting here..
$NVDA is at 141 pre market.. This can try to close the weekly back above 150 here in all honesty.. so i would avoid shorting here..
2
792
·
--
Bullish
Disputed
1
4
1.1k
·
--
Bullish
Verified
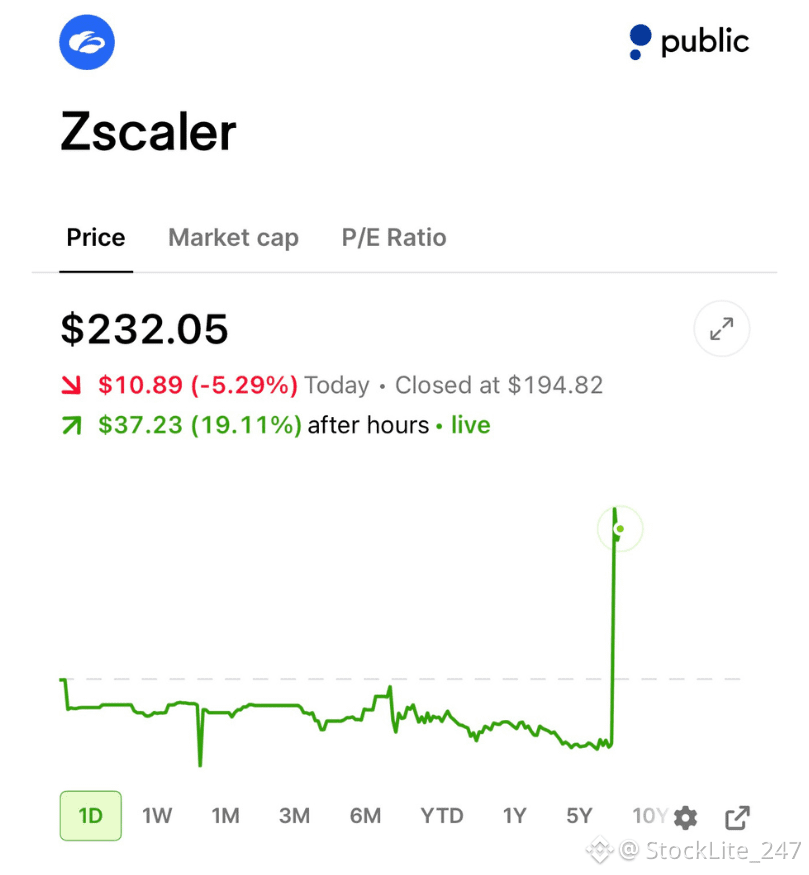
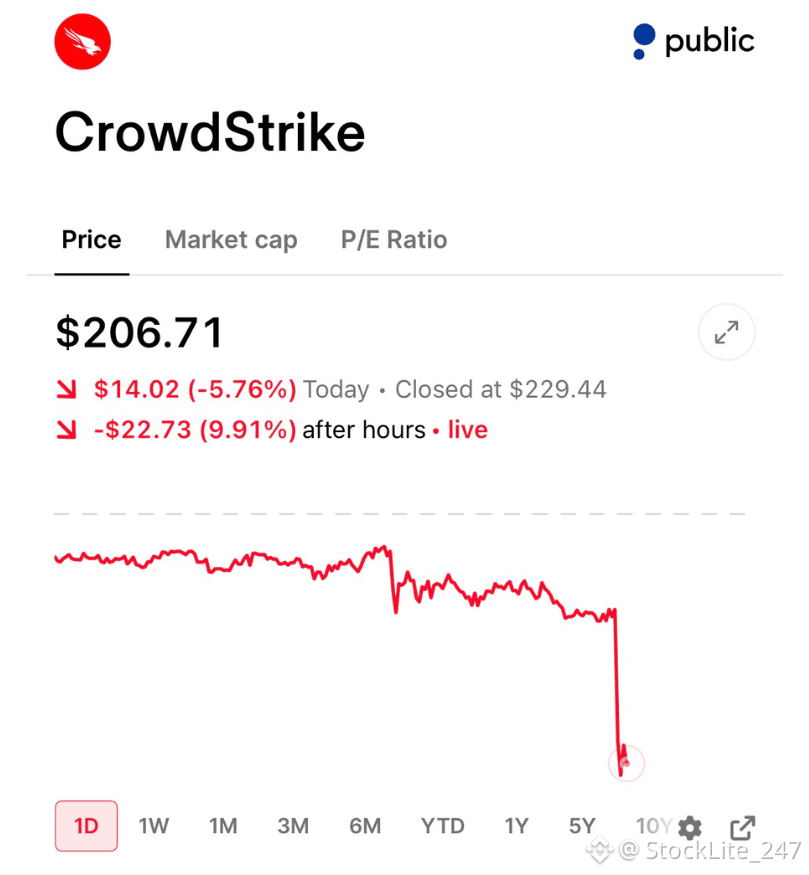
The timing of a potential $CRWD acquisition of $ZS couldn't be worse but it's truly hard to imagine a better fit between two cybersecurity companies.
CrowdStrike secures endpoint while Zscaler secures everything between device and cloud bringing endpoint, identity, browser, network and AI agent security under one roof and creating the world's largest pure-play cybersecurity company.
The timing of a potential $CRWD acquisition of $ZS couldn't be worse but it's truly hard to imagine a better fit between two cybersecurity companies.
CrowdStrike secures endpoint while Zscaler secures everything between device and cloud bringing endpoint, identity, browser, network and AI agent security under one roof and creating the world's largest pure-play cybersecurity company.
CrowdStrike secures endpoint while Zscaler secures everything between device and cloud bringing endpoint, identity, browser, network and AI agent security under one roof and creating the world's largest pure-play cybersecurity company.
2
698
·
--
Bullish
Verified
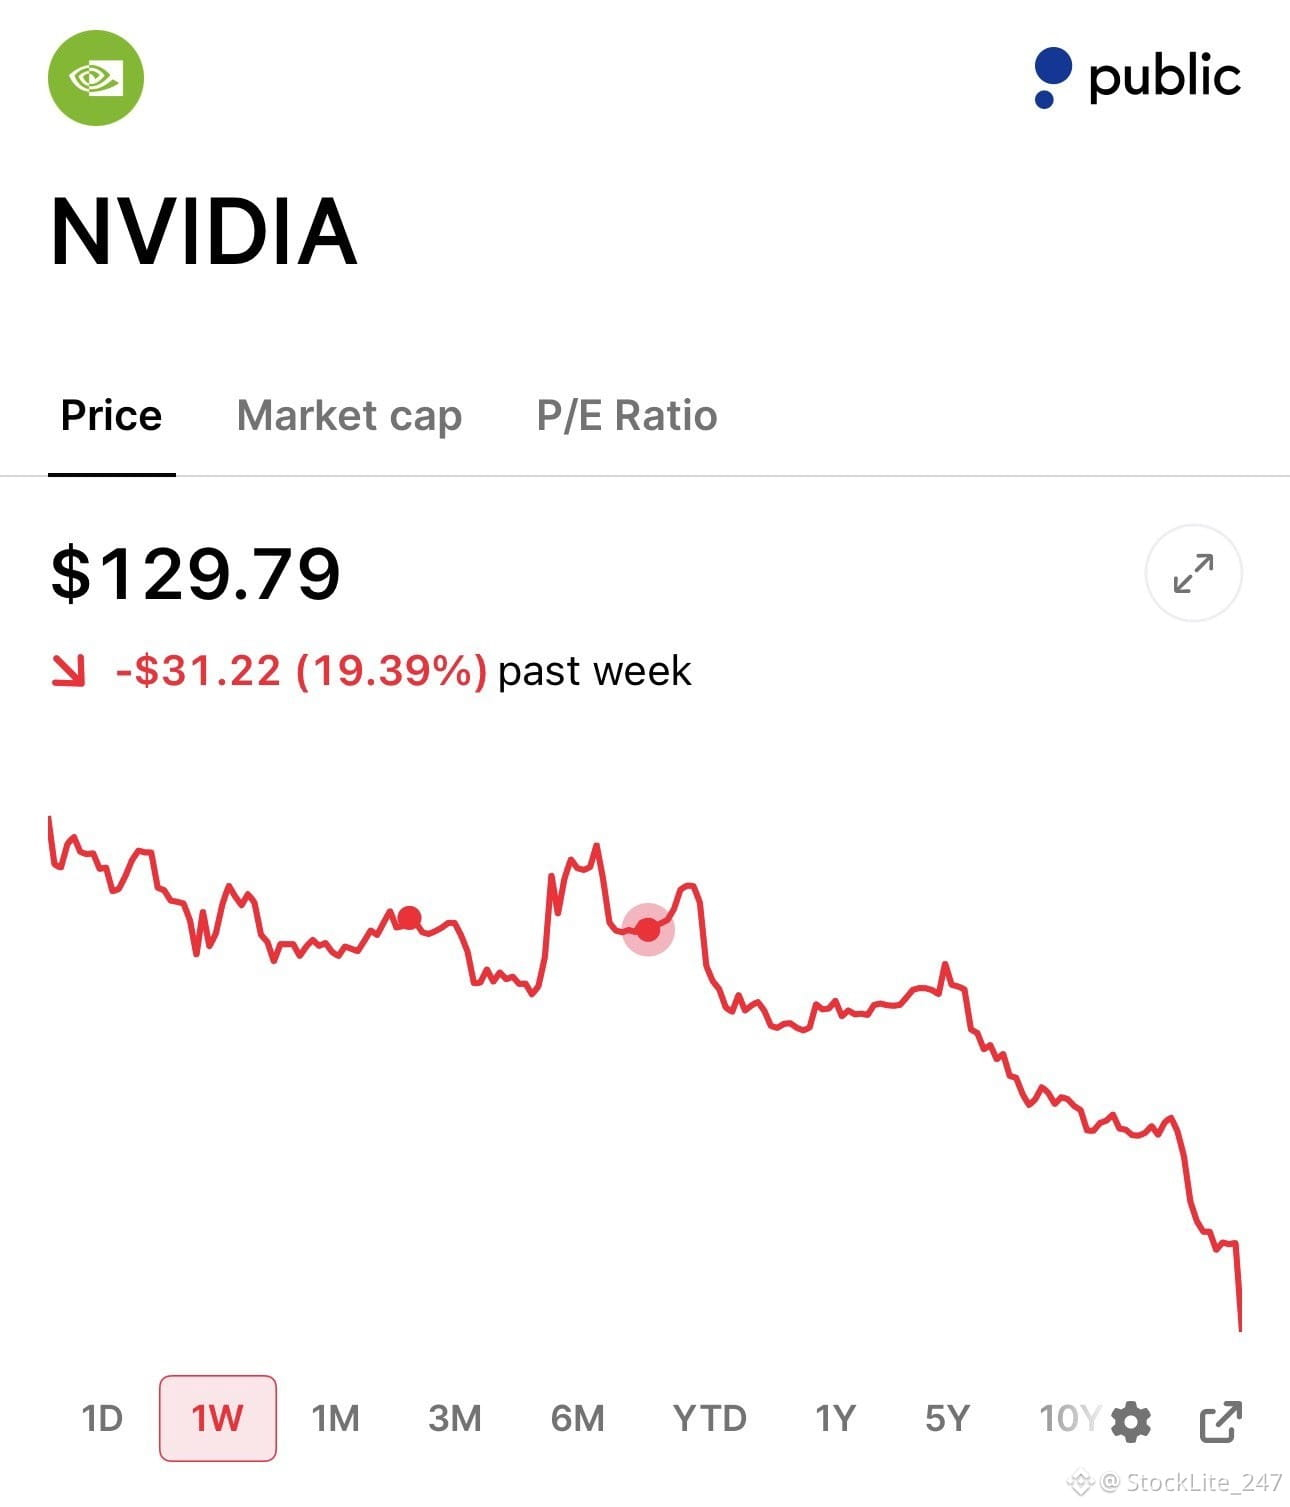
The SEC is reportedly investigating $NVDA over “potential accounting issues.”
When it rains, it pours.
The SEC is reportedly investigating $NVDA over “potential accounting issues.”
When it rains, it pours.
When it rains, it pours.
3
1.6k
·
--
Bullish
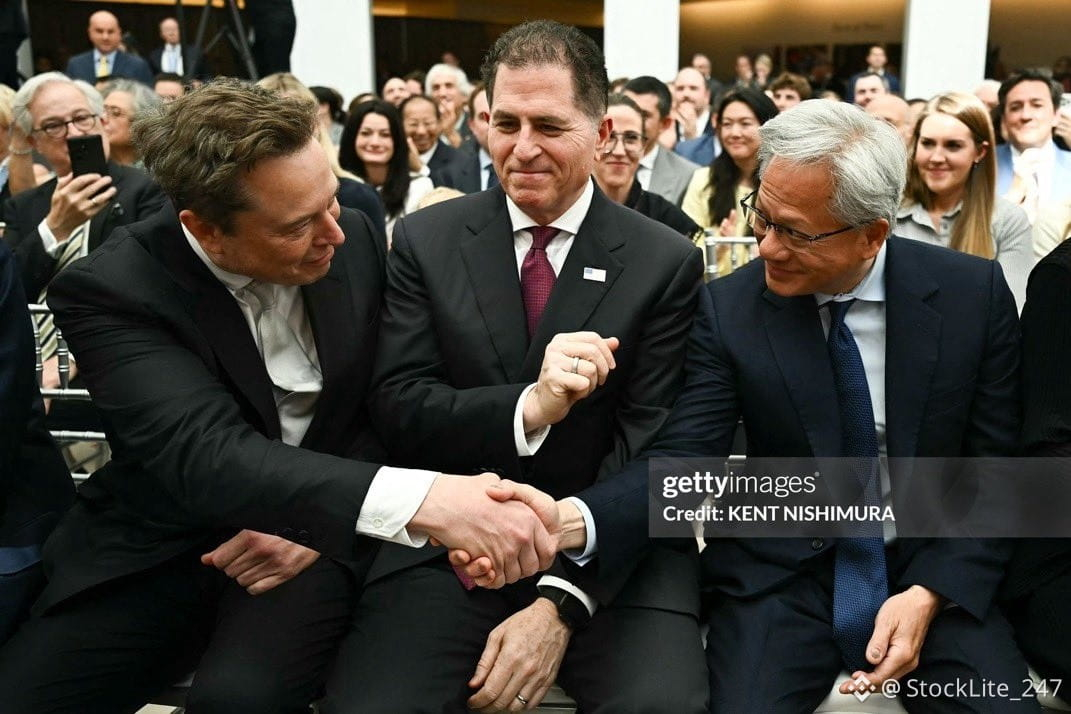
President Trump is calling for Jensen Huang to return as $NVDA CEO saying he deserves a second chance.
“If they were smart, they’d take that brilliant man, accept an apology, and let him go back to work.”
President Trump is calling for Jensen Huang to return as $NVDA CEO saying he deserves a second chance.
“If they were smart, they’d take that brilliant man, accept an apology, and let him go back to work.”
“If they were smart, they’d take that brilliant man, accept an apology, and let him go back to work.”
2
5
6.5k
·
--
Bullish
Partly True
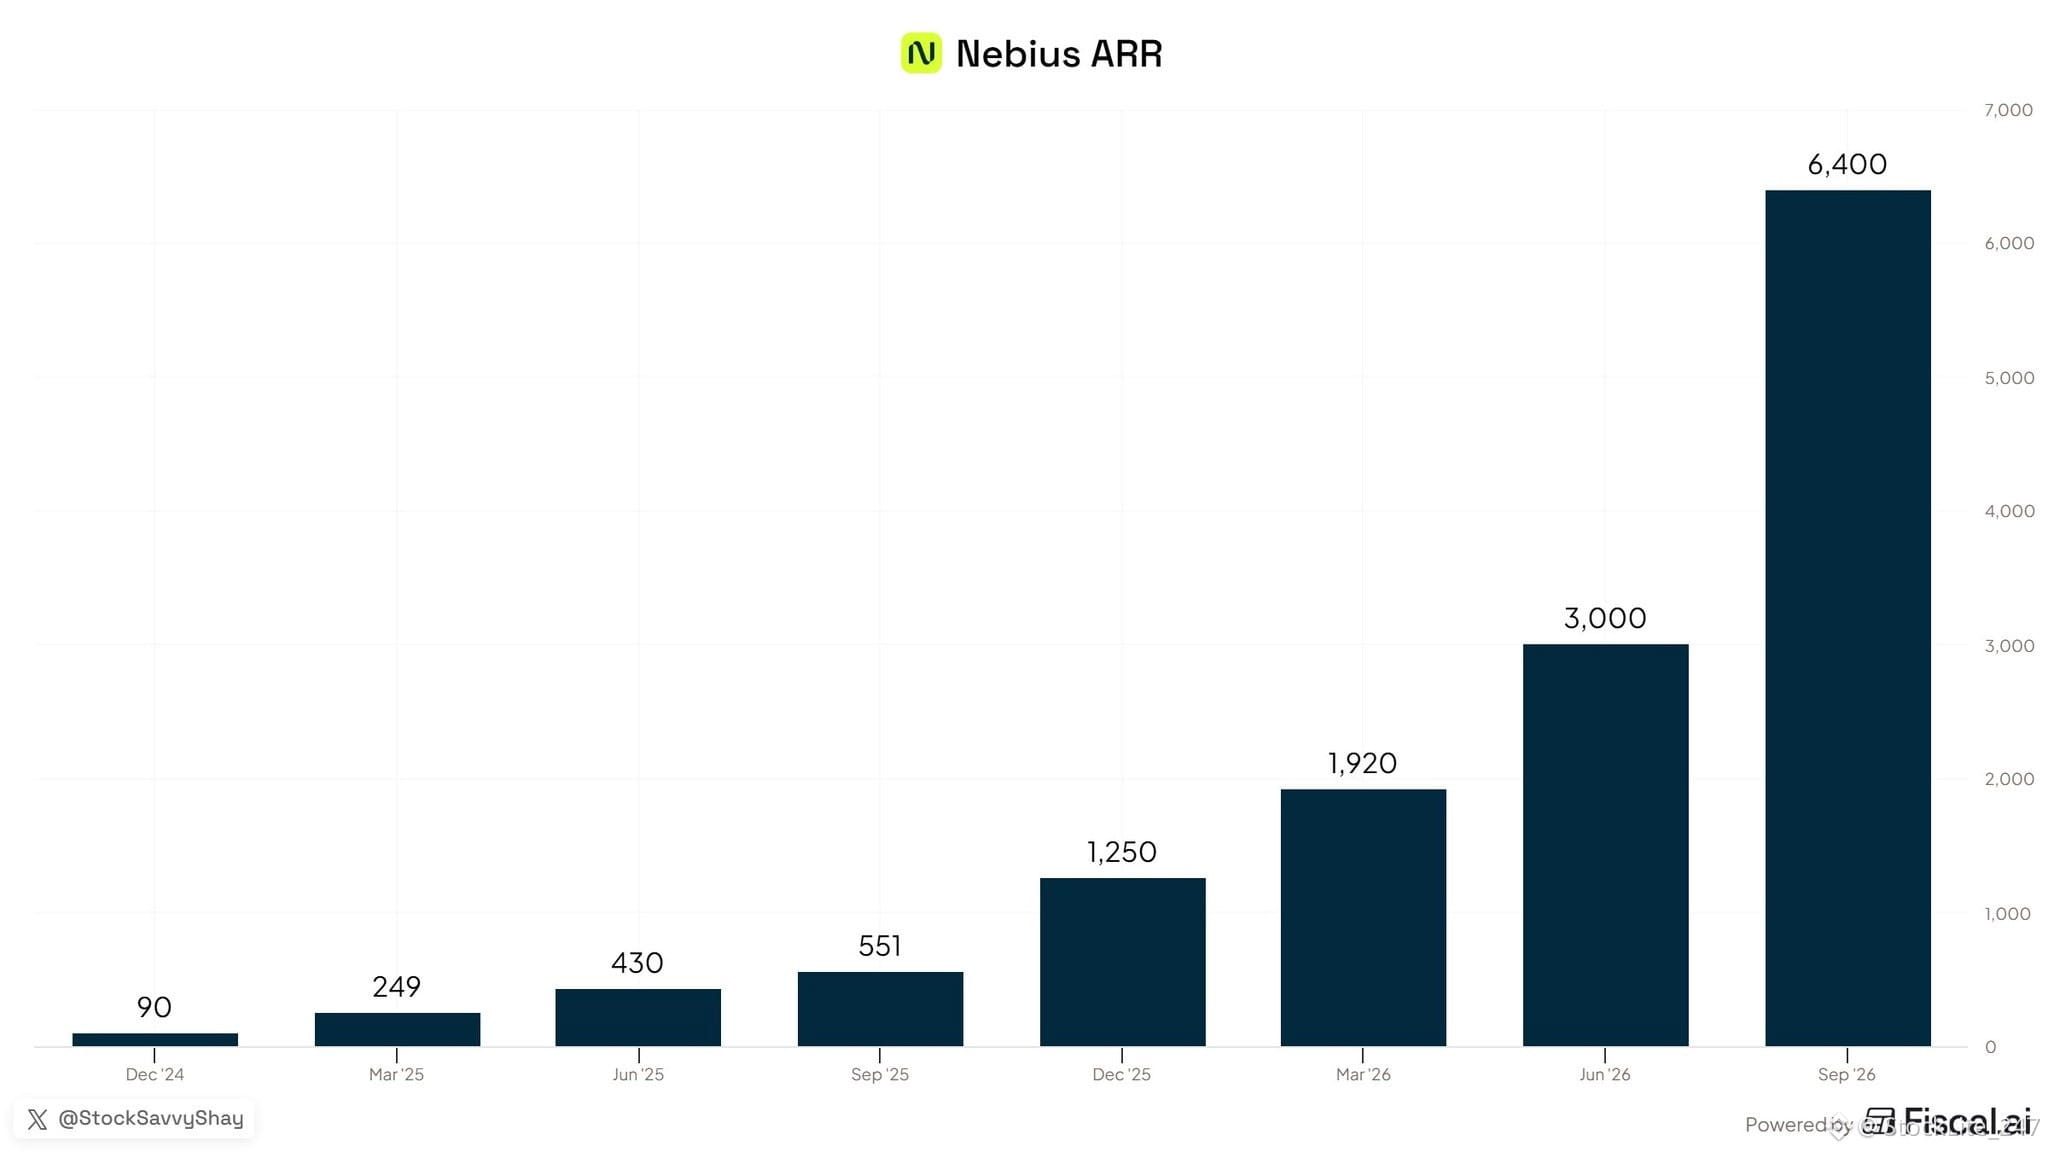
$NBIS now trading at ~4x ARR despite more than doubling ARR last quarter with its Token Factory expanding the business into inference and managed AI services.
All while Hopper GPUs are recontracting at ~2x their original rates and $NVDA has named Nebius an early Rubin customer.
$NBIS now trading at ~4x ARR despite more than doubling ARR last quarter with its Token Factory expanding the business into inference and managed AI services.
All while Hopper GPUs are recontracting at ~2x their original rates and $NVDA has named Nebius an early Rubin customer.
All while Hopper GPUs are recontracting at ~2x their original rates and $NVDA has named Nebius an early Rubin customer.
1
790
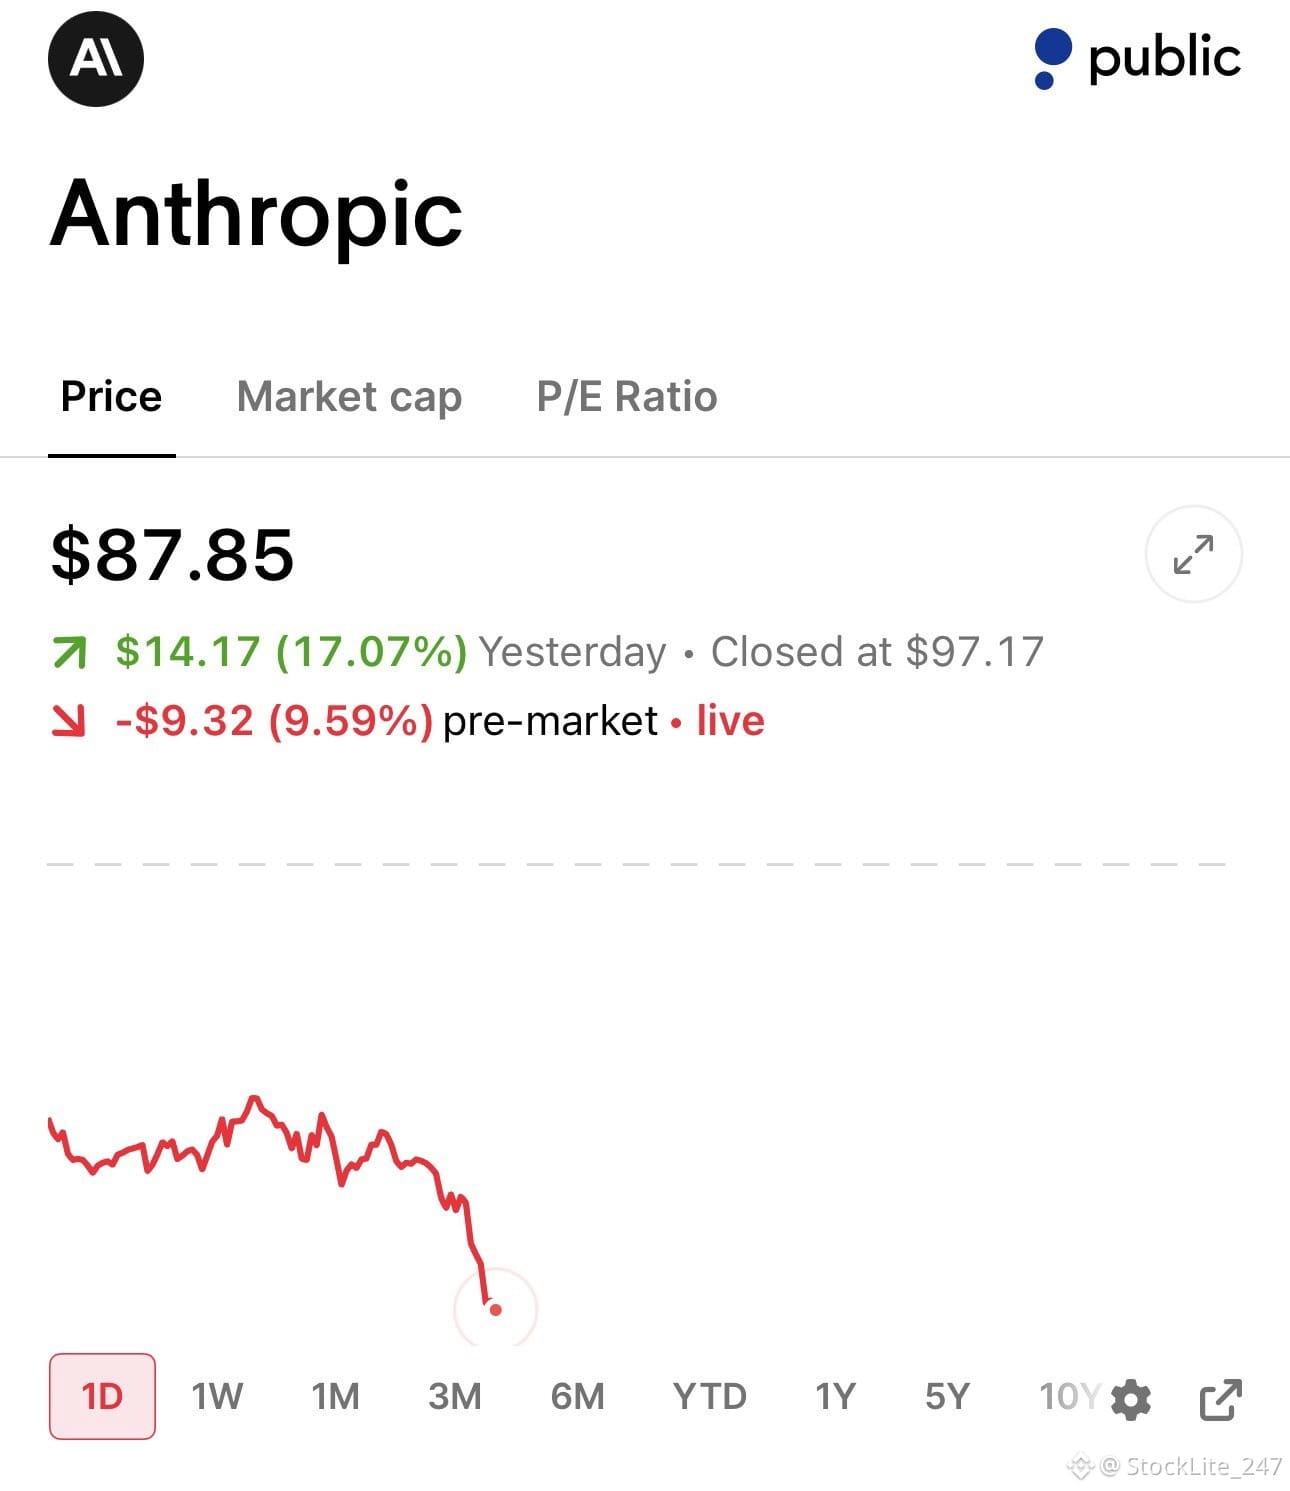
$ANTB is already in a bear market after falling over 20% from its IPO high.
It really only took one trading day.
$ANTB is already in a bear market after falling over 20% from its IPO high.
It really only took one trading day.
It really only took one trading day.
1
613
·
--
Bullish
Verified
Trump entering Iran war in February was the first domino in what turned into a brutal 2026:
• Oil spiked toward $120 as Hormuz shipping stalled
• Inflation reaccelerated and 10-year yield climbed above 5%
• Fed hiked for first time since 2023 with another hike priced for December
• Higher rates compressed growth multiples and stressed AI credit
• Economic pain fed into midterms flipping Texas and putting data center buildouts at risk
• AI fallout apparently got so bad Jensen had no choice but to have multiple affairs before resigning as $NVDA CEO
Silver lining is that 2027 has a pretty low bar to clear.
Trump entering Iran war in February was the first domino in what turned into a brutal 2026:
• Oil spiked toward $120 as Hormuz shipping stalled
• Inflation reaccelerated and 10-year yield climbed above 5%
• Fed hiked for first time since 2023 with another hike priced for December
• Higher rates compressed growth multiples and stressed AI credit
• Economic pain fed into midterms flipping Texas and putting data center buildouts at risk
• AI fallout apparently got so bad Jensen had no choice but to have multiple affairs before resigning as $NVDA CEO
Silver lining is that 2027 has a pretty low bar to clear.
• Oil spiked toward $120 as Hormuz shipping stalled
• Inflation reaccelerated and 10-year yield climbed above 5%
• Fed hiked for first time since 2023 with another hike priced for December
• Higher rates compressed growth multiples and stressed AI credit
• Economic pain fed into midterms flipping Texas and putting data center buildouts at risk
• AI fallout apparently got so bad Jensen had no choice but to have multiple affairs before resigning as $NVDA CEO
Silver lining is that 2027 has a pretty low bar to clear.
1
612
·
--
Bullish
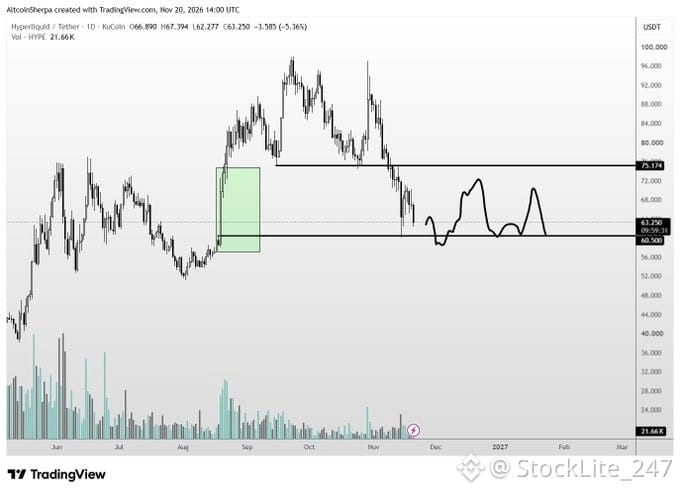
$HYPE it makes sense to me to fill out this inefficient move from before and trade in this range for a bit. It looks nasty in the short term but it's still 1 of the best companies in crypto
$HYPE it makes sense to me to fill out this inefficient move from before and trade in this range for a bit. It looks nasty in the short term but it's still 1 of the best companies in crypto
1
2.2k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BTCReboundsAbove$60KAmidWhaleDipBuying
59,234 views
296 Discussing
Abraxas Capital, Other Whales Buy the BTC Dip as Bitcoin Briefly Reclaims $60,000
Binance News
·33 Likes
·65.1k views
SolanaSets2027RoadmapToDoubleComputeCapacity
41,196 views
830 Discussing
CaliforniaNvidiaProbeExaminesPotentialCriminalViolations
11,583 views
106 Discussing