
#tpu
tpu
1,898 views
12 Discussing
Hot
Latest
·
--
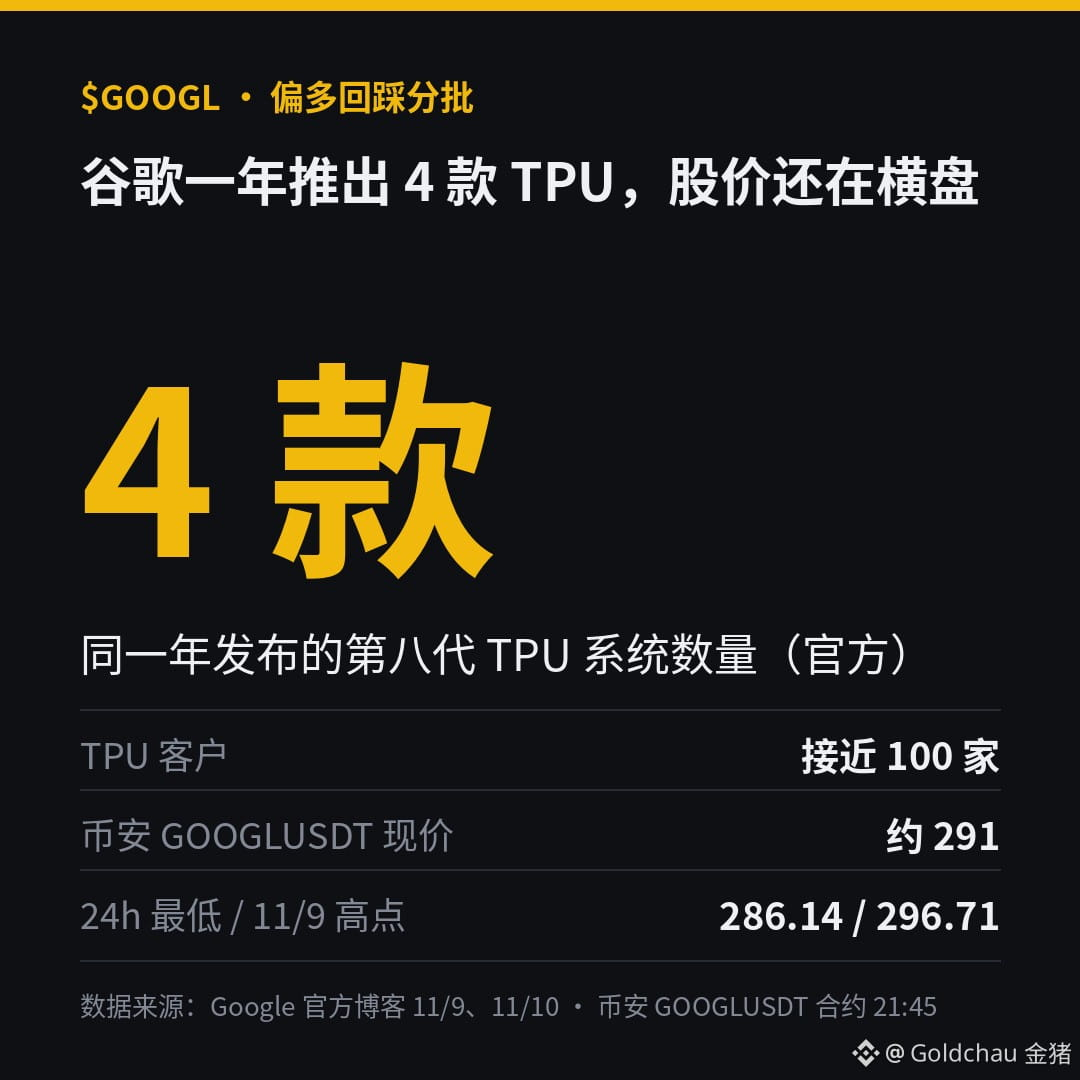
Golden Pig's take: Google just expanded its eighth-generation TPU lineup to 4 models at once, and opened its new Gemini 4 Carbon model to developers and users. $GOOGL I'm bullish, but I'll scale in only on pullbacks, not chase above 297.
Google officially announced TPU 8tx and TPU 8i Max on 11/9, making this the fourth eighth-generation TPU model released this year. The company also said it now has nearly 100 TPU customers. On 11/10, it announced the launch of Gemini 4 Carbon.
The Binance GOOGLUSDT perpetual contract is currently around 291, up about 1.3% over 24h, with a low of 286.14. The 11/9 high of 296.71 is still overhead. The contract's 24h trading volume is about 193 million U.
My plan: start with a small position in stages near 286 on a pullback; reduce first if it falls below 286, exit if it breaks below 278; add if it gets back above 297.
When major tech companies are rolling out new products at a rapid pace while their stock prices move sideways, how would you manage your $GOOGL position?
#谷歌 #美股 #TPU
$GOOGL $BTC
Source: Google official blog, Binance GOOGLUSDT perpetual contract market data. DYOR; this is not investment advice.
Golden Pig's take: Google just expanded its eighth-generation TPU lineup to 4 models at once, and opened its new Gemini 4 Carbon model to developers and users. $GOOGL I'm bullish, but I'll scale in only on pullbacks, not chase above 297.
Google officially announced TPU 8tx and TPU 8i Max on 11/9, making this the fourth eighth-generation TPU model released this year. The company also said it now has nearly 100 TPU customers. On 11/10, it announced the launch of Gemini 4 Carbon.
The Binance GOOGLUSDT perpetual contract is currently around 291, up about 1.3% over 24h, with a low of 286.14. The 11/9 high of 296.71 is still overhead. The contract's 24h trading volume is about 193 million U.
My plan: start with a small position in stages near 286 on a pullback; reduce first if it falls below 286, exit if it breaks below 278; add if it gets back above 297.
When major tech companies are rolling out new products at a rapid pace while their stock prices move sideways, how would you manage your $GOOGL position?
#谷歌 #美股 #TPU
$GOOGL $BTC
Source: Google official blog, Binance GOOGLUSDT perpetual contract market data. DYOR; this is not investment advice.
Google officially announced TPU 8tx and TPU 8i Max on 11/9, making this the fourth eighth-generation TPU model released this year. The company also said it now has nearly 100 TPU customers. On 11/10, it announced the launch of Gemini 4 Carbon.
The Binance GOOGLUSDT perpetual contract is currently around 291, up about 1.3% over 24h, with a low of 286.14. The 11/9 high of 296.71 is still overhead. The contract's 24h trading volume is about 193 million U.
My plan: start with a small position in stages near 286 on a pullback; reduce first if it falls below 286, exit if it breaks below 278; add if it gets back above 297.
When major tech companies are rolling out new products at a rapid pace while their stock prices move sideways, how would you manage your $GOOGL position?
#谷歌 #美股 #TPU
$GOOGL $BTC
Source: Google official blog, Binance GOOGLUSDT perpetual contract market data. DYOR; this is not investment advice.
1
423
·
--
Google’s space-computing test flight: Orbital TPU “talks back” for the first time
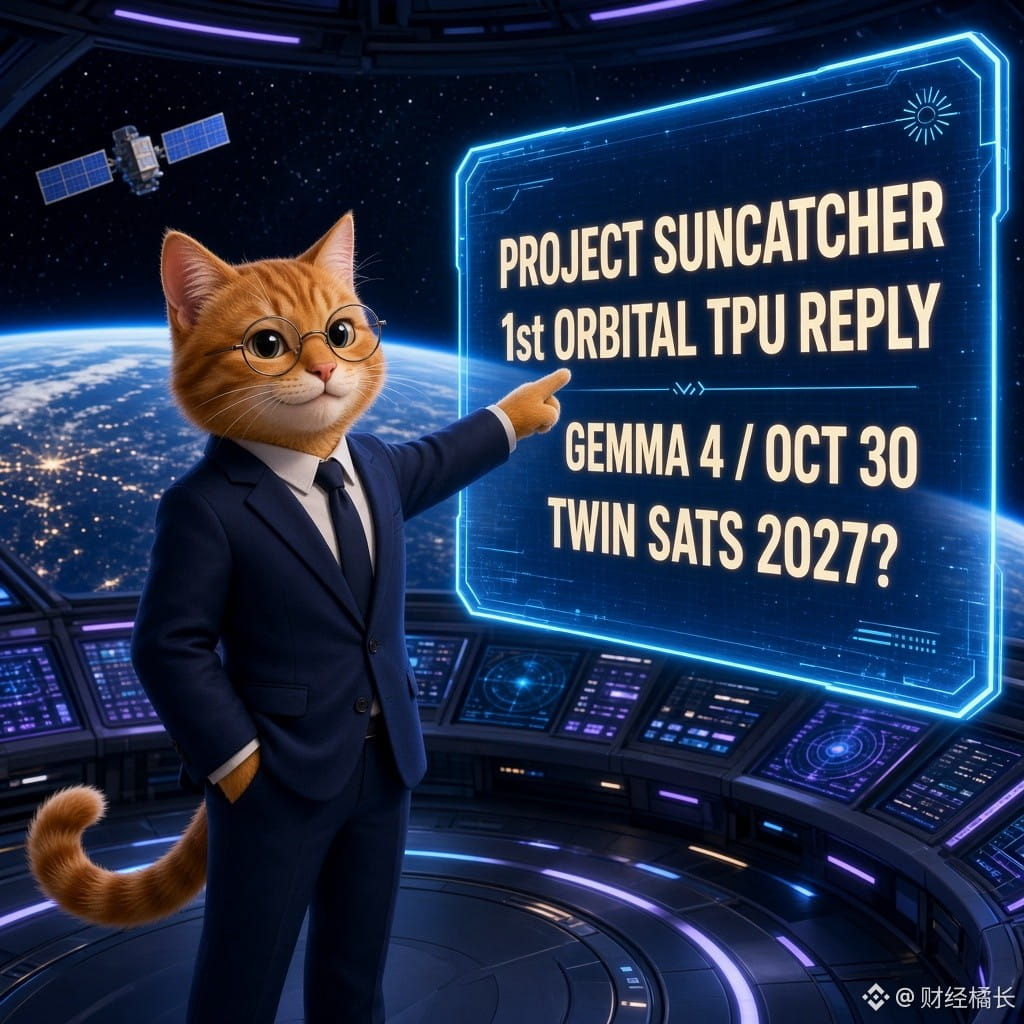
According to reports dated 10/30 from the Google blog, The Verge, and TechCrunch, the Project Suncatcher prototype satellite received its first in-orbit AI reply from a data-center-class TPU. An onboard Gemma 4 model generated a space haiku, and its downlink during a pass over Svalbard, Norway, confirmed “Hello World.” The satellite launched on 10/1 and carries four TPUs, with about 1 kW of power. It can currently run only one TPU at a time, for around 20 minutes. Next up: testing thermal stress and radiation. A two-satellite link-up is planned for 2027.
【Viewpoint】As AI on Earth runs up against power and cooling constraints, space computing is moving from concept to real-world test flights. In the short term, this remains a research milestone and doesn’t change the current data-center CapEx story. Over the medium to long term, it could reshape the narrative around “where computing power should be located.”
【Opportunities/Risks】Watch the results of radiation and thermal testing, as well as progress toward the 2027 two-satellite milestone. In trading, don’t overhype space computing as a short-term theme; on-the-ground cloud and chip plays, along with AI narratives like $FET, are still more direct. Risk-asset sentiment around $BTC can also move in tandem with tech narratives.
Which do you favor: space-computing test flights, or continued bets on terrestrial data-center CapEx?
#AI #太空算力 #Google #TPU $FET $BTC
For reference only; this is not investment advice
Google’s space-computing test flight: Orbital TPU “talks back” for the first time
According to reports dated 10/30 from the Google blog, The Verge, and TechCrunch, the Project Suncatcher prototype satellite received its first in-orbit AI reply from a data-center-class TPU. An onboard Gemma 4 model generated a space haiku, and its downlink during a pass over Svalbard, Norway, confirmed “Hello World.” The satellite launched on 10/1 and carries four TPUs, with about 1 kW of power. It can currently run only one TPU at a time, for around 20 minutes. Next up: testing thermal stress and radiation. A two-satellite link-up is planned for 2027.
【Viewpoint】As AI on Earth runs up against power and cooling constraints, space computing is moving from concept to real-world test flights. In the short term, this remains a research milestone and doesn’t change the current data-center CapEx story. Over the medium to long term, it could reshape the narrative around “where computing power should be located.”
【Opportunities/Risks】Watch the results of radiation and thermal testing, as well as progress toward the 2027 two-satellite milestone. In trading, don’t overhype space computing as a short-term theme; on-the-ground cloud and chip plays, along with AI narratives like $FET , are still more direct. Risk-asset sentiment around $BTC can also move in tandem with tech narratives.
Which do you favor: space-computing test flights, or continued bets on terrestrial data-center CapEx?
#AI #太空算力 #Google #TPU $FET $BTC
For reference only; this is not investment advice
According to reports dated 10/30 from the Google blog, The Verge, and TechCrunch, the Project Suncatcher prototype satellite received its first in-orbit AI reply from a data-center-class TPU. An onboard Gemma 4 model generated a space haiku, and its downlink during a pass over Svalbard, Norway, confirmed “Hello World.” The satellite launched on 10/1 and carries four TPUs, with about 1 kW of power. It can currently run only one TPU at a time, for around 20 minutes. Next up: testing thermal stress and radiation. A two-satellite link-up is planned for 2027.
【Viewpoint】As AI on Earth runs up against power and cooling constraints, space computing is moving from concept to real-world test flights. In the short term, this remains a research milestone and doesn’t change the current data-center CapEx story. Over the medium to long term, it could reshape the narrative around “where computing power should be located.”
【Opportunities/Risks】Watch the results of radiation and thermal testing, as well as progress toward the 2027 two-satellite milestone. In trading, don’t overhype space computing as a short-term theme; on-the-ground cloud and chip plays, along with AI narratives like $FET , are still more direct. Risk-asset sentiment around $BTC can also move in tandem with tech narratives.
Which do you favor: space-computing test flights, or continued bets on terrestrial data-center CapEx?
#AI #太空算力 #Google #TPU $FET $BTC
For reference only; this is not investment advice
210

·
--
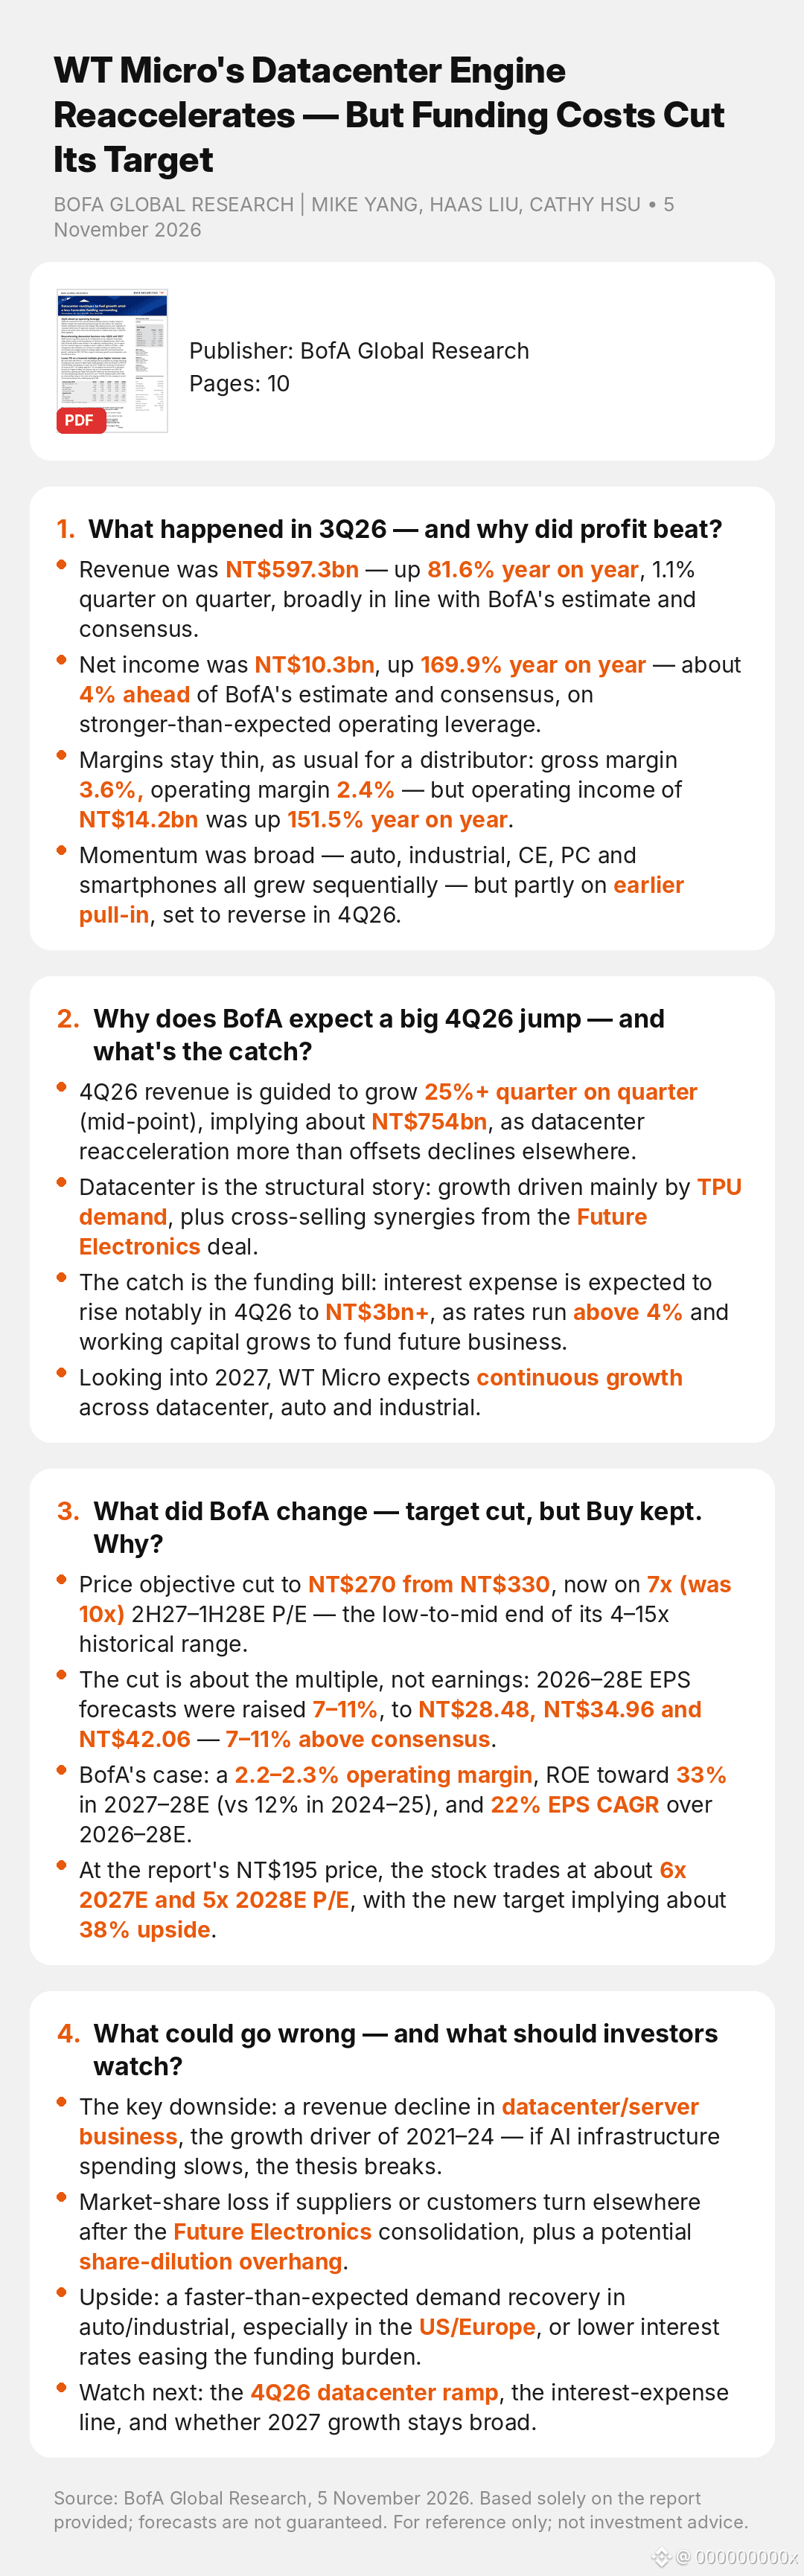
Article
WT Micro's Datacenter Engine Reaccelerates — But Funding Costs Cut Its TargetWT Micro's Datacenter Engine Reaccelerates — But Funding Costs Cut Its Target
$3036.TW
BOFA GLOBAL RESEARCH | MIKE YANG, HAAS LIU, CATHY HSU • 5 November 2026
1. What happened in 3Q26 — and why did profit beat?
• Revenue was NT$597.3bn — up 81.6% year on year, 1.1% quarter on quarter, broadly in line with BofA's estimate and consensus.
• Net income was NT$10.3bn, up 169.9% year on year — about 4% ahead of BofA's estimate and consensus, on stronger-than-expected operating leverage.
• Margins stay thin, as usual for a distributor: gross margin 3.6%, operating margin 2.4% — but operating income of NT$14.2bn was up 151.5% year on year.
• Momentum was broad — auto, industrial, CE, PC and smartphones all grew sequentially — but partly on earlier pull-in, set to reverse in 4Q26.
2. Why does BofA expect a big 4Q26 jump — and what's the catch?
• 4Q26 revenue is guided to grow 25%+ quarter on quarter (mid-point), implying about NT$754bn, as datacenter reacceleration more than offsets declines elsewhere.
• Datacenter is the structural story: growth driven mainly by TPU demand, plus cross-selling synergies from the Future Electronics deal.
• The catch is the funding bill: interest expense is expected to rise notably in 4Q26 to NT$3bn+, as rates run above 4% and working capital grows to fund future business.
• Looking into 2027, WT Micro expects continuous growth across datacenter, auto and industrial.
3. What did BofA change — target cut, but Buy kept. Why?
• Price objective cut to NT$270 from NT$330, now on 7x (was 10x) 2H27–1H28E P/E — the low-to-mid end of its 4–15x historical range.
• The cut is about the multiple, not earnings: 2026–28E EPS forecasts were raised 7–11%, to NT$28.48, NT$34.96 and NT$42.06 — 7–11% above consensus.
• BofA's case: a 2.2–2.3% operating margin, ROE toward 33% in 2027–28E (vs 12% in 2024–25), and 22% EPS CAGR over 2026–28E.
• At the report's NT$195 price, the stock trades at about 6x 2027E and 5x 2028E P/E, with the new target implying about 38% upside.
4. What could go wrong — and what should investors watch?
• The key downside: a revenue decline in datacenter/server business, the growth driver of 2021–24 — if AI infrastructure spending slows, the thesis breaks.
• Market-share loss if suppliers or customers turn elsewhere after the Future Electronics consolidation, plus a potential share-dilution overhang.
• Upside: a faster-than-expected demand recovery in auto/industrial, especially in the US/Europe, or lower interest rates easing the funding burden.
• Watch next: the 4Q26 datacenter ramp, the interest-expense line, and whether 2027 growth stays broad.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#DataCenters #Semiconductors #AI #Taiwan #TPU
Source: BofA Global Research, 5 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-6567fd40fc4e4224941a1c18332915fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
WT Micro's Datacenter Engine Reaccelerates — But Funding Costs Cut Its Target
WT Micro's Datacenter Engine Reaccelerates — But Funding Costs Cut Its Target
$3036.TW
BOFA GLOBAL RESEARCH | MIKE YANG, HAAS LIU, CATHY HSU • 5 November 2026
1. What happened in 3Q26 — and why did profit beat?
• Revenue was NT$597.3bn — up 81.6% year on year, 1.1% quarter on quarter, broadly in line with BofA's estimate and consensus.
• Net income was NT$10.3bn, up 169.9% year on year — about 4% ahead of BofA's estimate and consensus, on stronger-than-expected operating leverage.
• Margins stay thin, as usual for a distributor: gross margin 3.6%, operating margin 2.4% — but operating income of NT$14.2bn was up 151.5% year on year.
• Momentum was broad — auto, industrial, CE, PC and smartphones all grew sequentially — but partly on earlier pull-in, set to reverse in 4Q26.
2. Why does BofA expect a big 4Q26 jump — and what's the catch?
• 4Q26 revenue is guided to grow 25%+ quarter on quarter (mid-point), implying about NT$754bn, as datacenter reacceleration more than offsets declines elsewhere.
• Datacenter is the structural story: growth driven mainly by TPU demand, plus cross-selling synergies from the Future Electronics deal.
• The catch is the funding bill: interest expense is expected to rise notably in 4Q26 to NT$3bn+, as rates run above 4% and working capital grows to fund future business.
• Looking into 2027, WT Micro expects continuous growth across datacenter, auto and industrial.
3. What did BofA change — target cut, but Buy kept. Why?
• Price objective cut to NT$270 from NT$330, now on 7x (was 10x) 2H27–1H28E P/E — the low-to-mid end of its 4–15x historical range.
• The cut is about the multiple, not earnings: 2026–28E EPS forecasts were raised 7–11%, to NT$28.48, NT$34.96 and NT$42.06 — 7–11% above consensus.
• BofA's case: a 2.2–2.3% operating margin, ROE toward 33% in 2027–28E (vs 12% in 2024–25), and 22% EPS CAGR over 2026–28E.
• At the report's NT$195 price, the stock trades at about 6x 2027E and 5x 2028E P/E, with the new target implying about 38% upside.
4. What could go wrong — and what should investors watch?
• The key downside: a revenue decline in datacenter/server business, the growth driver of 2021–24 — if AI infrastructure spending slows, the thesis breaks.
• Market-share loss if suppliers or customers turn elsewhere after the Future Electronics consolidation, plus a potential share-dilution overhang.
• Upside: a faster-than-expected demand recovery in auto/industrial, especially in the US/Europe, or lower interest rates easing the funding burden.
• Watch next: the 4Q26 datacenter ramp, the interest-expense line, and whether 2027 growth stays broad.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#DataCenters #Semiconductors #AI #Taiwan #TPU
Source: BofA Global Research, 5 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-6567fd40fc4e4224941a1c18332915fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$3036.TW
BOFA GLOBAL RESEARCH | MIKE YANG, HAAS LIU, CATHY HSU • 5 November 2026
1. What happened in 3Q26 — and why did profit beat?
• Revenue was NT$597.3bn — up 81.6% year on year, 1.1% quarter on quarter, broadly in line with BofA's estimate and consensus.
• Net income was NT$10.3bn, up 169.9% year on year — about 4% ahead of BofA's estimate and consensus, on stronger-than-expected operating leverage.
• Margins stay thin, as usual for a distributor: gross margin 3.6%, operating margin 2.4% — but operating income of NT$14.2bn was up 151.5% year on year.
• Momentum was broad — auto, industrial, CE, PC and smartphones all grew sequentially — but partly on earlier pull-in, set to reverse in 4Q26.
2. Why does BofA expect a big 4Q26 jump — and what's the catch?
• 4Q26 revenue is guided to grow 25%+ quarter on quarter (mid-point), implying about NT$754bn, as datacenter reacceleration more than offsets declines elsewhere.
• Datacenter is the structural story: growth driven mainly by TPU demand, plus cross-selling synergies from the Future Electronics deal.
• The catch is the funding bill: interest expense is expected to rise notably in 4Q26 to NT$3bn+, as rates run above 4% and working capital grows to fund future business.
• Looking into 2027, WT Micro expects continuous growth across datacenter, auto and industrial.
3. What did BofA change — target cut, but Buy kept. Why?
• Price objective cut to NT$270 from NT$330, now on 7x (was 10x) 2H27–1H28E P/E — the low-to-mid end of its 4–15x historical range.
• The cut is about the multiple, not earnings: 2026–28E EPS forecasts were raised 7–11%, to NT$28.48, NT$34.96 and NT$42.06 — 7–11% above consensus.
• BofA's case: a 2.2–2.3% operating margin, ROE toward 33% in 2027–28E (vs 12% in 2024–25), and 22% EPS CAGR over 2026–28E.
• At the report's NT$195 price, the stock trades at about 6x 2027E and 5x 2028E P/E, with the new target implying about 38% upside.
4. What could go wrong — and what should investors watch?
• The key downside: a revenue decline in datacenter/server business, the growth driver of 2021–24 — if AI infrastructure spending slows, the thesis breaks.
• Market-share loss if suppliers or customers turn elsewhere after the Future Electronics consolidation, plus a potential share-dilution overhang.
• Upside: a faster-than-expected demand recovery in auto/industrial, especially in the US/Europe, or lower interest rates easing the funding burden.
• Watch next: the 4Q26 datacenter ramp, the interest-expense line, and whether 2027 growth stays broad.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#DataCenters #Semiconductors #AI #Taiwan #TPU
Source: BofA Global Research, 5 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-6567fd40fc4e4224941a1c18332915fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
47
84

·
--
$GOOG BACKSTOPS $44B IN DATA CENTER LEASES FOR TPU AI CHIPS 🦈
📌 Google’s disclosed $44 billion in third-party lease guarantees — up from $6.5B in September — reflects an institutional bet on TPU sales outpacing financial obligations. Two sources confirm executives are confident in the math, with around ten projects totaling 2.4 gigawatts of capacity still under construction. 🏦
💡 This isn’t just an AI arms race — it’s a liquidity pile for compute infrastructure that could reshape the hardware landscape and ripple into crypto AI tokens tied to decentralized inference. 💬 Will the market begin pricing this backstop into ecosystem plays, or is it already too late? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOG #AI #TPU #Institutional #Crypto
🦈 💰
$GOOG BACKSTOPS $44B IN DATA CENTER LEASES FOR TPU AI CHIPS 🦈
📌 Google’s disclosed $44 billion in third-party lease guarantees — up from $6.5B in September — reflects an institutional bet on TPU sales outpacing financial obligations. Two sources confirm executives are confident in the math, with around ten projects totaling 2.4 gigawatts of capacity still under construction. 🏦
💡 This isn’t just an AI arms race — it’s a liquidity pile for compute infrastructure that could reshape the hardware landscape and ripple into crypto AI tokens tied to decentralized inference. 💬 Will the market begin pricing this backstop into ecosystem plays, or is it already too late? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOG #AI #TPU #Institutional #Crypto
🦈 💰
📌 Google’s disclosed $44 billion in third-party lease guarantees — up from $6.5B in September — reflects an institutional bet on TPU sales outpacing financial obligations. Two sources confirm executives are confident in the math, with around ten projects totaling 2.4 gigawatts of capacity still under construction. 🏦
💡 This isn’t just an AI arms race — it’s a liquidity pile for compute infrastructure that could reshape the hardware landscape and ripple into crypto AI tokens tied to decentralized inference. 💬 Will the market begin pricing this backstop into ecosystem plays, or is it already too late? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOG #AI #TPU #Institutional #Crypto
🦈 💰
22

·
--
📰 BlockBeats Daily Report 2026-08-08 | 2 articles in total
1. After DeepMind changes leadership, Google Cloud is viewed as the biggest near-term beneficiary: TPU system orders exceed $150 billion, and cloud revenue growth in 2027 may reach around 150%.
2. Morgan Stanley maintains its “Buy/Accumulate” view on SK hynix and Samsung, with target prices implying about 74% / 65% upside. However, DRAM/NAND price increases are expected to ease quarter by quarter, with a shift to the later stage of the cycle expected in 2026Q4.
3. Driven by AI compute demand, the 2027 forecast for cloud capex growth is raised from 14% to 29%, and cloud providers’ capacity is still tight.
4. Long-term order visibility improves: SK hynix has already signed contracts with about 10 key customers, and Samsung plans to include 60–70% of production capacity in long-term agreements.
5. Risk points: CXMT (ChangXin Memory) is expected to start supplying HBM to the China market as early as 2027. DRAM gross margin is near 90%, close to its historical peak, and valuation has already started to pull back.
#BlockBeats #Web3日报 #AI算力 #存储芯片 #TPU
📰 BlockBeats Daily Report 2026-08-08 | 2 articles in total
1. After DeepMind changes leadership, Google Cloud is viewed as the biggest near-term beneficiary: TPU system orders exceed $150 billion, and cloud revenue growth in 2027 may reach around 150%.
2. Morgan Stanley maintains its “Buy/Accumulate” view on SK hynix and Samsung, with target prices implying about 74% / 65% upside. However, DRAM/NAND price increases are expected to ease quarter by quarter, with a shift to the later stage of the cycle expected in 2026Q4.
3. Driven by AI compute demand, the 2027 forecast for cloud capex growth is raised from 14% to 29%, and cloud providers’ capacity is still tight.
4. Long-term order visibility improves: SK hynix has already signed contracts with about 10 key customers, and Samsung plans to include 60–70% of production capacity in long-term agreements.
5. Risk points: CXMT (ChangXin Memory) is expected to start supplying HBM to the China market as early as 2027. DRAM gross margin is near 90%, close to its historical peak, and valuation has already started to pull back.
#BlockBeats #Web3日报 #AI算力 #存储芯片 #TPU
1. After DeepMind changes leadership, Google Cloud is viewed as the biggest near-term beneficiary: TPU system orders exceed $150 billion, and cloud revenue growth in 2027 may reach around 150%.
2. Morgan Stanley maintains its “Buy/Accumulate” view on SK hynix and Samsung, with target prices implying about 74% / 65% upside. However, DRAM/NAND price increases are expected to ease quarter by quarter, with a shift to the later stage of the cycle expected in 2026Q4.
3. Driven by AI compute demand, the 2027 forecast for cloud capex growth is raised from 14% to 29%, and cloud providers’ capacity is still tight.
4. Long-term order visibility improves: SK hynix has already signed contracts with about 10 key customers, and Samsung plans to include 60–70% of production capacity in long-term agreements.
5. Risk points: CXMT (ChangXin Memory) is expected to start supplying HBM to the China market as early as 2027. DRAM gross margin is near 90%, close to its historical peak, and valuation has already started to pull back.
#BlockBeats #Web3日报 #AI算力 #存储芯片 #TPU
103

💥 $GOOGL GOOGLE'S AI STORY JUST PIVOTED FROM DEEPMIND TO THE CLOUD MONEY ENGINE 🦈
The DeepMind shakeup isn't a retreat — it's a repositioning of the arena. Hassabis stepping back, Jeff Dean and crew spinning up Discovery Loop, Koray taking Gemini's reins — Google is moving its chips from model ego battles toward the cloud money machine. 📊
SemiAnalysis points at the real generator: GCP grew 82% last quarter, partly by selling TPU systems to external SPVs supporting players like Anthropic. With the TPU order backlog stacking, GCP's 2027 growth could crush sell-side consensus and feed straight into Alphabet's EPS. 💥
The market's AI capex repricing finally clicks — investors are hesitant on model labs burning cash, but they'll pay up for the toll booth selling compute, cloud muscle, and accelerators. 🌊
💬 Are you riding the model hype or backing the compute pipeline that monetizes it? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOGL #AIInfrastructure #GoogleCloud #TPU #TechTrades
🎯 🦈
💥 $GOOGL GOOGLE'S AI STORY JUST PIVOTED FROM DEEPMIND TO THE CLOUD MONEY ENGINE 🦈
The DeepMind shakeup isn't a retreat — it's a repositioning of the arena. Hassabis stepping back, Jeff Dean and crew spinning up Discovery Loop, Koray taking Gemini's reins — Google is moving its chips from model ego battles toward the cloud money machine. 📊
SemiAnalysis points at the real generator: GCP grew 82% last quarter, partly by selling TPU systems to external SPVs supporting players like Anthropic. With the TPU order backlog stacking, GCP's 2027 growth could crush sell-side consensus and feed straight into Alphabet's EPS. 💥
The market's AI capex repricing finally clicks — investors are hesitant on model labs burning cash, but they'll pay up for the toll booth selling compute, cloud muscle, and accelerators. 🌊
💬 Are you riding the model hype or backing the compute pipeline that monetizes it? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOGL #AIInfrastructure #GoogleCloud #TPU #TechTrades
🎯 🦈
The DeepMind shakeup isn't a retreat — it's a repositioning of the arena. Hassabis stepping back, Jeff Dean and crew spinning up Discovery Loop, Koray taking Gemini's reins — Google is moving its chips from model ego battles toward the cloud money machine. 📊
SemiAnalysis points at the real generator: GCP grew 82% last quarter, partly by selling TPU systems to external SPVs supporting players like Anthropic. With the TPU order backlog stacking, GCP's 2027 growth could crush sell-side consensus and feed straight into Alphabet's EPS. 💥
The market's AI capex repricing finally clicks — investors are hesitant on model labs burning cash, but they'll pay up for the toll booth selling compute, cloud muscle, and accelerators. 🌊
💬 Are you riding the model hype or backing the compute pipeline that monetizes it? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOGL #AIInfrastructure #GoogleCloud #TPU #TechTrades
🎯 🦈
39
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
37,498 views
208 Discussing
2
#SolanaSets2027RoadmapToDoubleComputeCapacity
21,467 views
515 Discussing
3
#CaliforniaNvidiaProbeExaminesPotentialCriminalViolations
5,725 views
71 Discussing
4
#BlackRockLaunchesHKDollarDigitalLiquidityFund
17,441 views
429 Discussing
5
#NvidiaLoses$2.7TrillionInMonthAndAHalf
62,098 views
269 Discussing
6
#GlobalStocksFaceLongestLosingStreakSince2023
498,703 views
3,160 Discussing
7
#BlackRockIBITPostsRecord$541MSingleDayOutflow
80,176 views
160 Discussing
8
#AnthropicPlungesTowardIPOPriceonDay2
270,756 views
2,098 Discussing
9
#TwentyOneCapitalAdds172.25BTC
137,820 views
1,436 Discussing
10
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
16,492 views
95 Discussing