
#aws
aws
101,380 views
397 Discussing
Hot
Latest
·
--
AWS distributed KV cache skills: lower LLM costs and latency!
Capital-tracking fans, take note! A new AWS skill is here. Distributed KV caching helps lower the cost and latency of self-hosted LLMs. Amazon ElastiCache supercharges inference speed and slashes costs! #AWS #分布式KV缓存 #LLM #CapitalTrackingFans
AWS distributed KV cache skills: lower LLM costs and latency!
Capital-tracking fans, take note! A new AWS skill is here. Distributed KV caching helps lower the cost and latency of self-hosted LLMs. Amazon ElastiCache supercharges inference speed and slashes costs! #AWS #分布式KV缓存 #LLM #CapitalTrackingFans
Capital-tracking fans, take note! A new AWS skill is here. Distributed KV caching helps lower the cost and latency of self-hosted LLMs. Amazon ElastiCache supercharges inference speed and slashes costs! #AWS #分布式KV缓存 #LLM #CapitalTrackingFans
11
·
--
Understanding AWS SageMaker HyperPod's Data Capture Feature: A Powerful Tool for Model Optimization
AWS SageMaker HyperPod adds a data capture feature that records inference data in real time, helping teams monitor data drift and optimize model performance. Track key metrics in real time and pinpoint critical areas—an essential tool for technical analysts.#AWS #SageMaker
Understanding AWS SageMaker HyperPod's Data Capture Feature: A Powerful Tool for Model Optimization
AWS SageMaker HyperPod adds a data capture feature that records inference data in real time, helping teams monitor data drift and optimize model performance. Track key metrics in real time and pinpoint critical areas—an essential tool for technical analysts.#AWS #SageMaker
AWS SageMaker HyperPod adds a data capture feature that records inference data in real time, helping teams monitor data drift and optimize model performance. Track key metrics in real time and pinpoint critical areas—an essential tool for technical analysts.#AWS #SageMaker
69
Amazon (AMZN) closed at $259.30 on Nov. 6. AWS grew 39% year over year last quarter, putting cloud back in the spotlight—but after recent tech volatility, investors still want to see AI spending translate into lasting returns.
My lean: cautiously bullish while AWS growth stays this strong.
Can AWS keep carrying Amazon higher, or will rising AI costs become the bigger story?
#AMZNB
#amazon #AWS
Amazon (AMZN) closed at $259.30 on Nov. 6. AWS grew 39% year over year last quarter, putting cloud back in the spotlight—but after recent tech volatility, investors still want to see AI spending translate into lasting returns.
My lean: cautiously bullish while AWS growth stays this strong.
Can AWS keep carrying Amazon higher, or will rising AI costs become the bigger story?
#AMZNB
#amazon #AWS
My lean: cautiously bullish while AWS growth stays this strong.
Can AWS keep carrying Amazon higher, or will rising AI costs become the bigger story?
#AMZNB
#amazon #AWS
1
105

☁️ Amazon’s AI Edge: Building Its Own Infrastructure 👍
Amazon’s control over its data-center expansion could become a major advantage as investors question the financing behind the AI boom. Unlike companies relying heavily on debt-funded neocloud providers, Amazon builds much of its own infrastructure, giving AWS greater operational control and funding flexibility.
{spot}(AMZNBUSDT)
{stock_us}(AMZN.US)
AMZN was nearly unchanged at $259.82, down just 0.02%. The bigger story is AWS growth and its ability to turn rising AI demand into sustainable revenue. Watch cloud growth, operating margins, capital expenditure and free cash flow. The real test is whether AI revenue can grow faster than infrastructure costs.
$AMZNB $AMZN $AMZN.US #CoinVahini #Amazon #AWS #AIInfrastructure
☁️ Amazon’s AI Edge: Building Its Own Infrastructure 👍
Amazon’s control over its data-center expansion could become a major advantage as investors question the financing behind the AI boom. Unlike companies relying heavily on debt-funded neocloud providers, Amazon builds much of its own infrastructure, giving AWS greater operational control and funding flexibility.
AMZN was nearly unchanged at $259.82, down just 0.02%. The bigger story is AWS growth and its ability to turn rising AI demand into sustainable revenue. Watch cloud growth, operating margins, capital expenditure and free cash flow. The real test is whether AI revenue can grow faster than infrastructure costs.
$AMZNB $AMZN $AMZN.US #CoinVahini #Amazon #AWS #AIInfrastructure
Amazon’s control over its data-center expansion could become a major advantage as investors question the financing behind the AI boom. Unlike companies relying heavily on debt-funded neocloud providers, Amazon builds much of its own infrastructure, giving AWS greater operational control and funding flexibility.
AMZN was nearly unchanged at $259.82, down just 0.02%. The bigger story is AWS growth and its ability to turn rising AI demand into sustainable revenue. Watch cloud growth, operating margins, capital expenditure and free cash flow. The real test is whether AI revenue can grow faster than infrastructure costs.
$AMZNB $AMZN $AMZN.US #CoinVahini #Amazon #AWS #AIInfrastructure
AMZNUS-2.41%
AMZNB+2.38%
76
·
--
AWS Deep Insight unlocks a new perspective on production
For the fund-tracking crowd, AWS launches the Deep Insight multi-agent system to help you stay on top of production challenges. Combining Anthropic technology with AWS Cloud, it automatically analyzes data to deliver deeper insights. Choose from self-hosted, web, or managed AgentCore deployment options for a flexible fit.#资金追踪 #智能生产 #AWS
AWS Deep Insight unlocks a new perspective on production
For the fund-tracking crowd, AWS launches the Deep Insight multi-agent system to help you stay on top of production challenges. Combining Anthropic technology with AWS Cloud, it automatically analyzes data to deliver deeper insights. Choose from self-hosted, web, or managed AgentCore deployment options for a flexible fit.#资金追踪 #智能生产 #AWS
For the fund-tracking crowd, AWS launches the Deep Insight multi-agent system to help you stay on top of production challenges. Combining Anthropic technology with AWS Cloud, it automatically analyzes data to deliver deeper insights. Choose from self-hosted, web, or managed AgentCore deployment options for a flexible fit.#资金追踪 #智能生产 #AWS
157
·
--
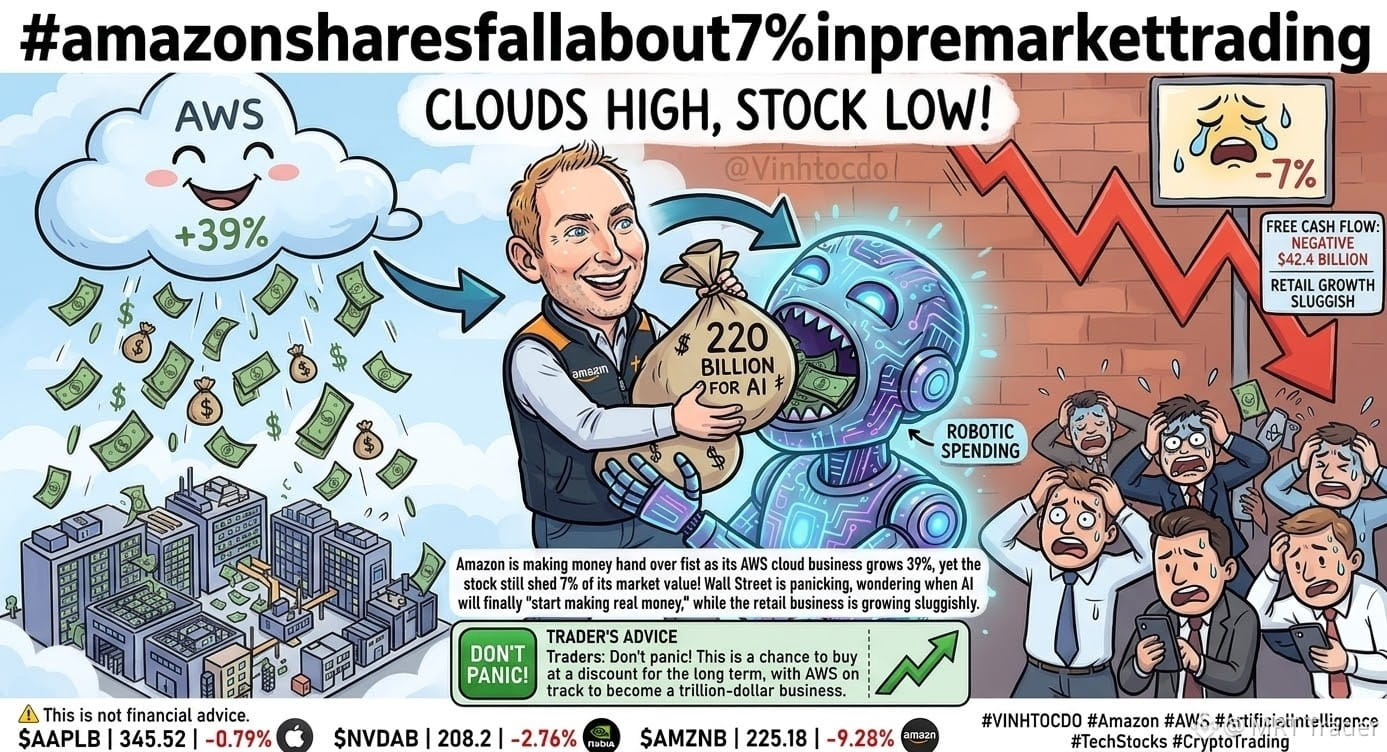
Amazon slips ~7% pre-market despite strong AWS growth 📉
AWS revenue grew 39%, yet $AMZNB still dropped about 7% in pre-market trading.
The reason is spending. Amazon is pouring roughly $220B into AI, and free cash flow has swung to about -$42.4B. Investors are asking when that AI spend turns into real returns, while the retail side is growing slowly.
Some traders see the dip as a long-term discount, with AWS on track to be a trillion-dollar business. Others will want proof that the spending pays off first. Either way, size your positions carefully. ⚠️ Not financial advice.
Trade here 👉 $AMZNB $NVDAB $AAPLB
#Amazon #AWS #AI #TechStocks
Amazon slips ~7% pre-market despite strong AWS growth 📉
AWS revenue grew 39%, yet $AMZNB still dropped about 7% in pre-market trading.
The reason is spending. Amazon is pouring roughly $220B into AI, and free cash flow has swung to about -$42.4B. Investors are asking when that AI spend turns into real returns, while the retail side is growing slowly.
Some traders see the dip as a long-term discount, with AWS on track to be a trillion-dollar business. Others will want proof that the spending pays off first. Either way, size your positions carefully. ⚠️ Not financial advice.
Trade here 👉 $AMZNB $NVDAB $AAPLB
#Amazon #AWS #AI #TechStocks
AWS revenue grew 39%, yet $AMZNB still dropped about 7% in pre-market trading.
The reason is spending. Amazon is pouring roughly $220B into AI, and free cash flow has swung to about -$42.4B. Investors are asking when that AI spend turns into real returns, while the retail side is growing slowly.
Some traders see the dip as a long-term discount, with AWS on track to be a trillion-dollar business. Others will want proof that the spending pays off first. Either way, size your positions carefully. ⚠️ Not financial advice.
Trade here 👉 $AMZNB $NVDAB $AAPLB
#Amazon #AWS #AI #TechStocks
2
23
·
--
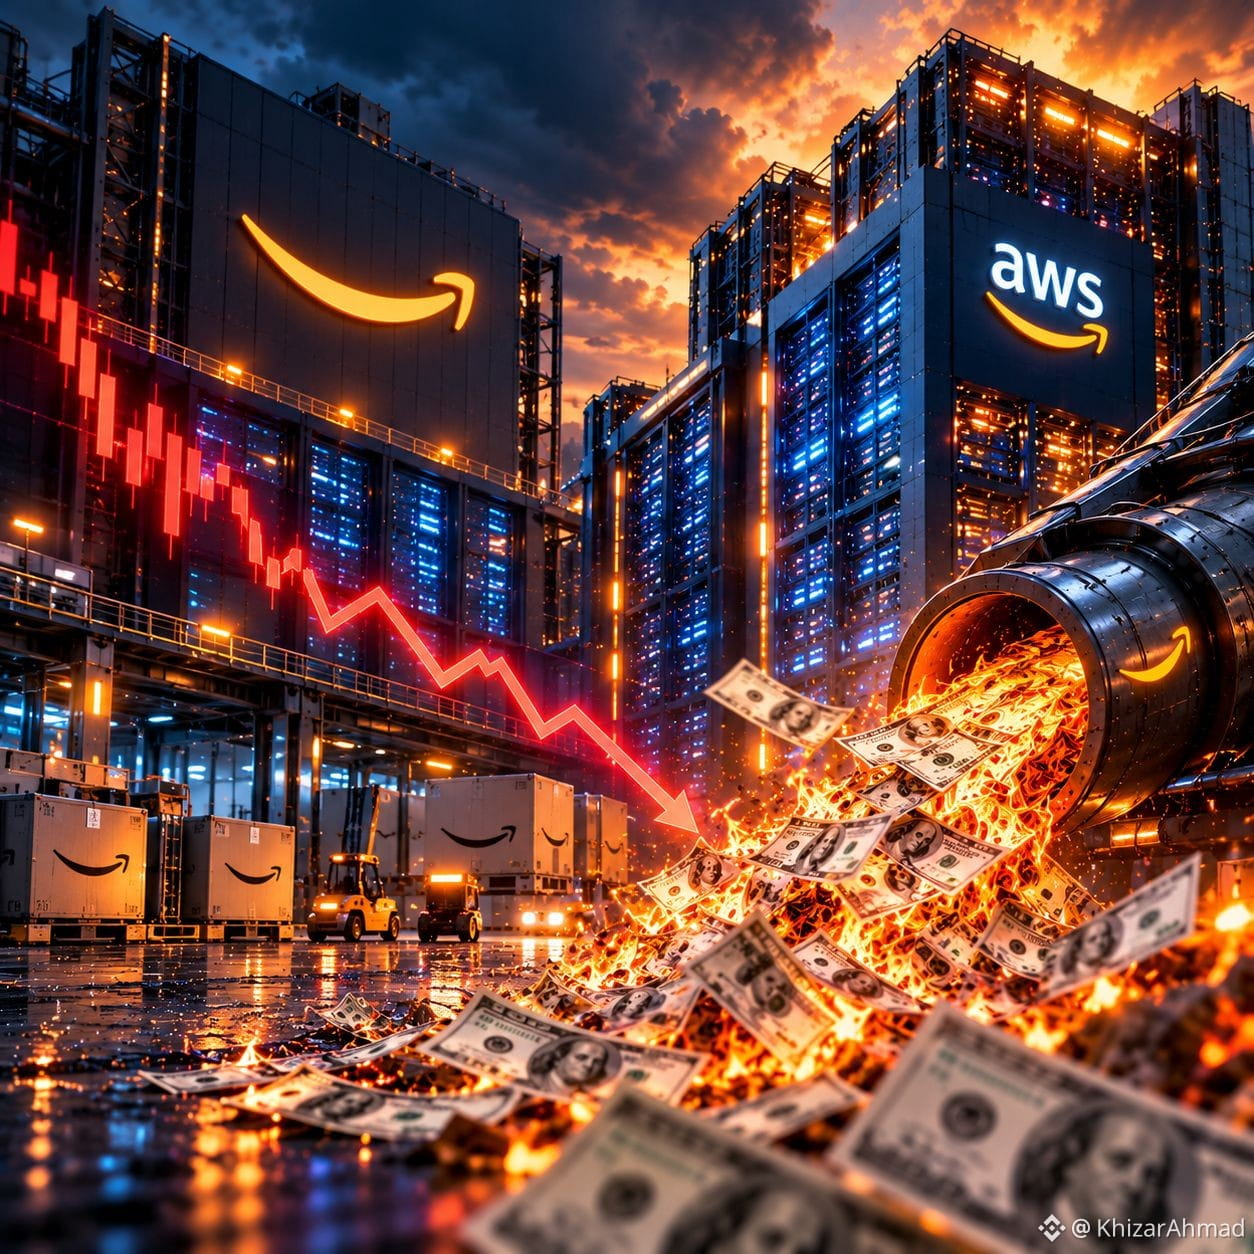
🚨 Amazon's AI Spending Hits a Record!
Amazon's free cash flow dropped to -$42.4 billion over the 12 months ending September 2026 as the company ramps up AI infrastructure investments.
📉 Q3 capital spending: ~$77B
🚀 AWS revenue: ~$46B (+39%)
💰 Planned 2026 spending: ~$220B
Despite strong cloud growth, massive AI investments are putting pressure on cash flow.
🤔 Will Amazon's AI investments pay off in the long run?
Source: Yahoo Finance | Oct. 30, 2026
{spot}(AMZNBUSDT)
#amazon #Aİ #AWS #TechNews
🚨 Amazon's AI Spending Hits a Record!
Amazon's free cash flow dropped to -$42.4 billion over the 12 months ending September 2026 as the company ramps up AI infrastructure investments.
📉 Q3 capital spending: ~$77B
🚀 AWS revenue: ~$46B (+39%)
💰 Planned 2026 spending: ~$220B
Despite strong cloud growth, massive AI investments are putting pressure on cash flow.
🤔 Will Amazon's AI investments pay off in the long run?
Source: Yahoo Finance | Oct. 30, 2026
#amazon #Aİ #AWS #TechNews
Amazon's free cash flow dropped to -$42.4 billion over the 12 months ending September 2026 as the company ramps up AI infrastructure investments.
📉 Q3 capital spending: ~$77B
🚀 AWS revenue: ~$46B (+39%)
💰 Planned 2026 spending: ~$220B
Despite strong cloud growth, massive AI investments are putting pressure on cash flow.
🤔 Will Amazon's AI investments pay off in the long run?
Source: Yahoo Finance | Oct. 30, 2026
#amazon #Aİ #AWS #TechNews
83
·
--
Amazon falls 6% after hours: cloud is strong, but overall results miss expectationsAmazon's report is a bit of a mixed bag.
Revenue was about $201.9 billion, and earnings per share were $1.89—both fell short of Wall Street expectations. Shares dropped more than 6% after hours.
AWS was especially strong. Revenue was about $46 billion, up 39.3% year over year—the fastest growth in nearly five years—with an annualized run rate of around $184 billion. Operating income was about $17.8 billion, with a margin close to 39%. AI-related revenue is still growing at a triple-digit rate.
Cloud is accelerating, but the overall results fell short, and Amazon is still sticking to its full-year capital spending plan of $220 billion. Free cash flow over the past twelve months was about negative $42.4 billion, driven by spending on AI infrastructure.
Fourth-quarter revenue guidance is $240 billion to $247 billion. The market heard that and sold off first. Operating income is projected to reach a record range, but investors are asking: can profits keep up with the pace of spending?
Amazon falls 6% after hours: cloud is strong, but overall results miss expectations
Amazon's report is a bit of a mixed bag.
Revenue was about $201.9 billion, and earnings per share were $1.89—both fell short of Wall Street expectations. Shares dropped more than 6% after hours.
AWS was especially strong. Revenue was about $46 billion, up 39.3% year over year—the fastest growth in nearly five years—with an annualized run rate of around $184 billion. Operating income was about $17.8 billion, with a margin close to 39%. AI-related revenue is still growing at a triple-digit rate.
Cloud is accelerating, but the overall results fell short, and Amazon is still sticking to its full-year capital spending plan of $220 billion. Free cash flow over the past twelve months was about negative $42.4 billion, driven by spending on AI infrastructure.
Fourth-quarter revenue guidance is $240 billion to $247 billion. The market heard that and sold off first. Operating income is projected to reach a record range, but investors are asking: can profits keep up with the pace of spending?
Revenue was about $201.9 billion, and earnings per share were $1.89—both fell short of Wall Street expectations. Shares dropped more than 6% after hours.
AWS was especially strong. Revenue was about $46 billion, up 39.3% year over year—the fastest growth in nearly five years—with an annualized run rate of around $184 billion. Operating income was about $17.8 billion, with a margin close to 39%. AI-related revenue is still growing at a triple-digit rate.
Cloud is accelerating, but the overall results fell short, and Amazon is still sticking to its full-year capital spending plan of $220 billion. Free cash flow over the past twelve months was about negative $42.4 billion, driven by spending on AI infrastructure.
Fourth-quarter revenue guidance is $240 billion to $247 billion. The market heard that and sold off first. Operating income is projected to reach a record range, but investors are asking: can profits keep up with the pace of spending?
15
Amazon’s earnings report is a real split-personality situation: AWS surged 39% to $46 billion, its fastest growth in five years, and the cheering hadn’t even died down yet; meanwhile, EPS came in at just $1.89, missing the $1.97 estimate, and revenue of $201.9 billion also fell a little short. The stock promptly plunged 7.3% after hours. Cloud bulls: We’re absolutely crushing it! Retail bulls: Don’t look at me—I’m dragging everyone down. Shareholders: Let’s start by emptying our wallets. With a $220 billion AI infrastructure bill staring us in the face, is this genuinely expensive or worth it? Pick a side in the comments: A, 39% cloud growth is reason enough to be confident—buy the dip without thinking; B, free cash flow has burned down to negative $42.4 billion, so don’t try to catch a falling knife yet.
$BTC $ETH $SOL
#亚马逊 #财报 #AWS
Amazon’s earnings report is a real split-personality situation: AWS surged 39% to $46 billion, its fastest growth in five years, and the cheering hadn’t even died down yet; meanwhile, EPS came in at just $1.89, missing the $1.97 estimate, and revenue of $201.9 billion also fell a little short. The stock promptly plunged 7.3% after hours. Cloud bulls: We’re absolutely crushing it! Retail bulls: Don’t look at me—I’m dragging everyone down. Shareholders: Let’s start by emptying our wallets. With a $220 billion AI infrastructure bill staring us in the face, is this genuinely expensive or worth it? Pick a side in the comments: A, 39% cloud growth is reason enough to be confident—buy the dip without thinking; B, free cash flow has burned down to negative $42.4 billion, so don’t try to catch a falling knife yet.
$BTC $ETH $SOL
#亚马逊 #财报 #AWS
$BTC $ETH $SOL
#亚马逊 #财报 #AWS
43
A counterintuitive question: Cloud is sold out, so what could make Amazon’s stock fail to rise tonight? AWS grew 37% last quarter, its fastest pace in 18 quarters. Tonight, the market wants 38%—about $45.6 billion—which means growth has to accelerate again. Revenue is expected to hit $202 billion, with EPS at $1.96, both right at the top of the company’s guidance range of $197 billion to $202 billion. The CEO said outright that cloud capacity for 2026 and 2027 is basically sold out, and even $220 billion in capital spending won’t be enough. The options market has already priced in a 6.6% to 7.2% move—which basically says tomorrow night it’s either a big jump or a big drop, with no middle ground. Pick a side in the comments: A, AWS tops 38% and the stock takes off; B, soft guidance sends it down 7% first. Which side are you betting on? $BTC $ETH $SOL #亚马逊 #财报 #AWS
A counterintuitive question: Cloud is sold out, so what could make Amazon’s stock fail to rise tonight? AWS grew 37% last quarter, its fastest pace in 18 quarters. Tonight, the market wants 38%—about $45.6 billion—which means growth has to accelerate again. Revenue is expected to hit $202 billion, with EPS at $1.96, both right at the top of the company’s guidance range of $197 billion to $202 billion. The CEO said outright that cloud capacity for 2026 and 2027 is basically sold out, and even $220 billion in capital spending won’t be enough. The options market has already priced in a 6.6% to 7.2% move—which basically says tomorrow night it’s either a big jump or a big drop, with no middle ground. Pick a side in the comments: A, AWS tops 38% and the stock takes off; B, soft guidance sends it down 7% first. Which side are you betting on? $BTC $ETH $SOL #亚马逊 #财报 #AWS
6
·
--
Amazon Q3 earnings tonight: watching AWS growth and $220B in AI spending
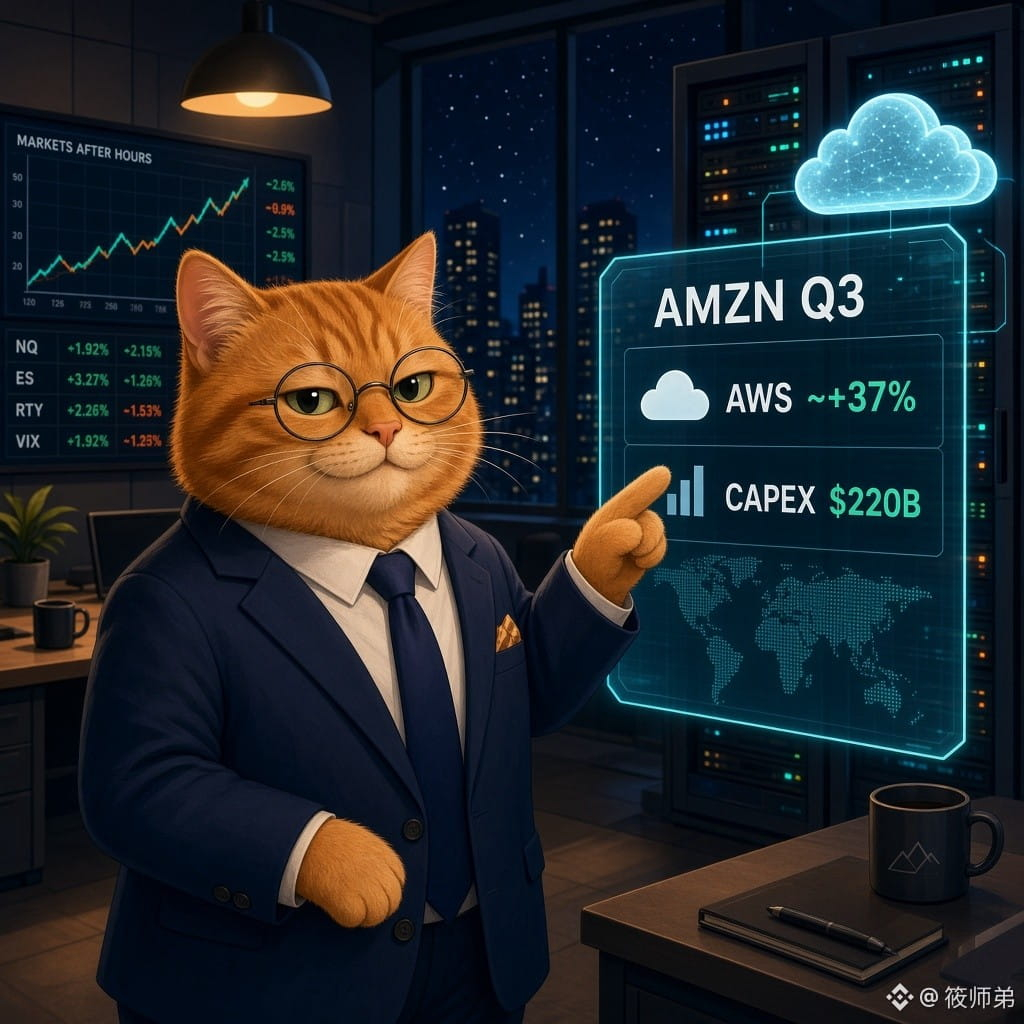
Reported after the market close on Oct. 29 ET (around early the following morning in Beijing). Zacks consensus estimates revenue of about $202.1 billion (+12%) and EPS of about $2.01; the company’s guidance is revenue of $197–202 billion and operating income of $22.5–26.5 billion (Yahoo Finance/Zacks).
AWS consensus is about $45.4 billion (+about 37.5%). In Q2, it grew 37% to $42.2 billion, its fastest growth in 18 quarters; AWS backlog is about $496 billion (Zacks). BofA sees AWS growth potentially reaching about 40%, with operating income of about $26.4 billion, slightly above consensus (Yahoo).
Full-year capex is about $220 billion (partly due to higher memory costs). Investors are focused on FCF and AI returns (Yahoo/GeekWire).
【View】
The third report in Big Tech’s cloud week: Microsoft and Google have just reported, and Amazon will show whether AI compute capacity is still selling out, and whether Trainium/Bedrock can handle orders from OpenAI/Anthropic. If growth accelerates again but capex doesn’t come down, the stock’s reaction will hinge on “the growth story vs. the cash-flow story.”
【Opportunities/Risks】
Opportunity: Further upward revisions to AWS guidance/backlog, and details on multi-gigawatt Trainium contracts, would benefit the compute, storage, and liquid-cooling supply chain.
Risk: Weak retail performance and oil prices weigh on Q4 guidance; another capex increase could pressure FCF. If AWS growth comes in below about 37% or guidance is soft, the AI infrastructure narrative could come under renewed pressure. Watch for short-term correlation with $BTC if risk appetite retreats.
Which worries you more: “Amazon beats expectations on AWS but ramps up capex again,” or “growth slows but cash flow improves”?
#亚马逊 #AWS #AI财报 #Crypto Markets
$BTC $RENDER
For informational purposes only; not investment advice.
Amazon Q3 earnings tonight: watching AWS growth and $220B in AI spending
Reported after the market close on Oct. 29 ET (around early the following morning in Beijing). Zacks consensus estimates revenue of about $202.1 billion (+12%) and EPS of about $2.01; the company’s guidance is revenue of $197–202 billion and operating income of $22.5–26.5 billion (Yahoo Finance/Zacks).
AWS consensus is about $45.4 billion (+about 37.5%). In Q2, it grew 37% to $42.2 billion, its fastest growth in 18 quarters; AWS backlog is about $496 billion (Zacks). BofA sees AWS growth potentially reaching about 40%, with operating income of about $26.4 billion, slightly above consensus (Yahoo).
Full-year capex is about $220 billion (partly due to higher memory costs). Investors are focused on FCF and AI returns (Yahoo/GeekWire).
【View】
The third report in Big Tech’s cloud week: Microsoft and Google have just reported, and Amazon will show whether AI compute capacity is still selling out, and whether Trainium/Bedrock can handle orders from OpenAI/Anthropic. If growth accelerates again but capex doesn’t come down, the stock’s reaction will hinge on “the growth story vs. the cash-flow story.”
【Opportunities/Risks】
Opportunity: Further upward revisions to AWS guidance/backlog, and details on multi-gigawatt Trainium contracts, would benefit the compute, storage, and liquid-cooling supply chain.
Risk: Weak retail performance and oil prices weigh on Q4 guidance; another capex increase could pressure FCF. If AWS growth comes in below about 37% or guidance is soft, the AI infrastructure narrative could come under renewed pressure. Watch for short-term correlation with $BTC if risk appetite retreats.
Which worries you more: “Amazon beats expectations on AWS but ramps up capex again,” or “growth slows but cash flow improves”?
#亚马逊 #AWS #AI财报 #Crypto Markets
$BTC $RENDER
For informational purposes only; not investment advice.
Reported after the market close on Oct. 29 ET (around early the following morning in Beijing). Zacks consensus estimates revenue of about $202.1 billion (+12%) and EPS of about $2.01; the company’s guidance is revenue of $197–202 billion and operating income of $22.5–26.5 billion (Yahoo Finance/Zacks).
AWS consensus is about $45.4 billion (+about 37.5%). In Q2, it grew 37% to $42.2 billion, its fastest growth in 18 quarters; AWS backlog is about $496 billion (Zacks). BofA sees AWS growth potentially reaching about 40%, with operating income of about $26.4 billion, slightly above consensus (Yahoo).
Full-year capex is about $220 billion (partly due to higher memory costs). Investors are focused on FCF and AI returns (Yahoo/GeekWire).
【View】
The third report in Big Tech’s cloud week: Microsoft and Google have just reported, and Amazon will show whether AI compute capacity is still selling out, and whether Trainium/Bedrock can handle orders from OpenAI/Anthropic. If growth accelerates again but capex doesn’t come down, the stock’s reaction will hinge on “the growth story vs. the cash-flow story.”
【Opportunities/Risks】
Opportunity: Further upward revisions to AWS guidance/backlog, and details on multi-gigawatt Trainium contracts, would benefit the compute, storage, and liquid-cooling supply chain.
Risk: Weak retail performance and oil prices weigh on Q4 guidance; another capex increase could pressure FCF. If AWS growth comes in below about 37% or guidance is soft, the AI infrastructure narrative could come under renewed pressure. Watch for short-term correlation with $BTC if risk appetite retreats.
Which worries you more: “Amazon beats expectations on AWS but ramps up capex again,” or “growth slows but cash flow improves”?
#亚马逊 #AWS #AI财报 #Crypto Markets
$BTC $RENDER
For informational purposes only; not investment advice.
395

·
--
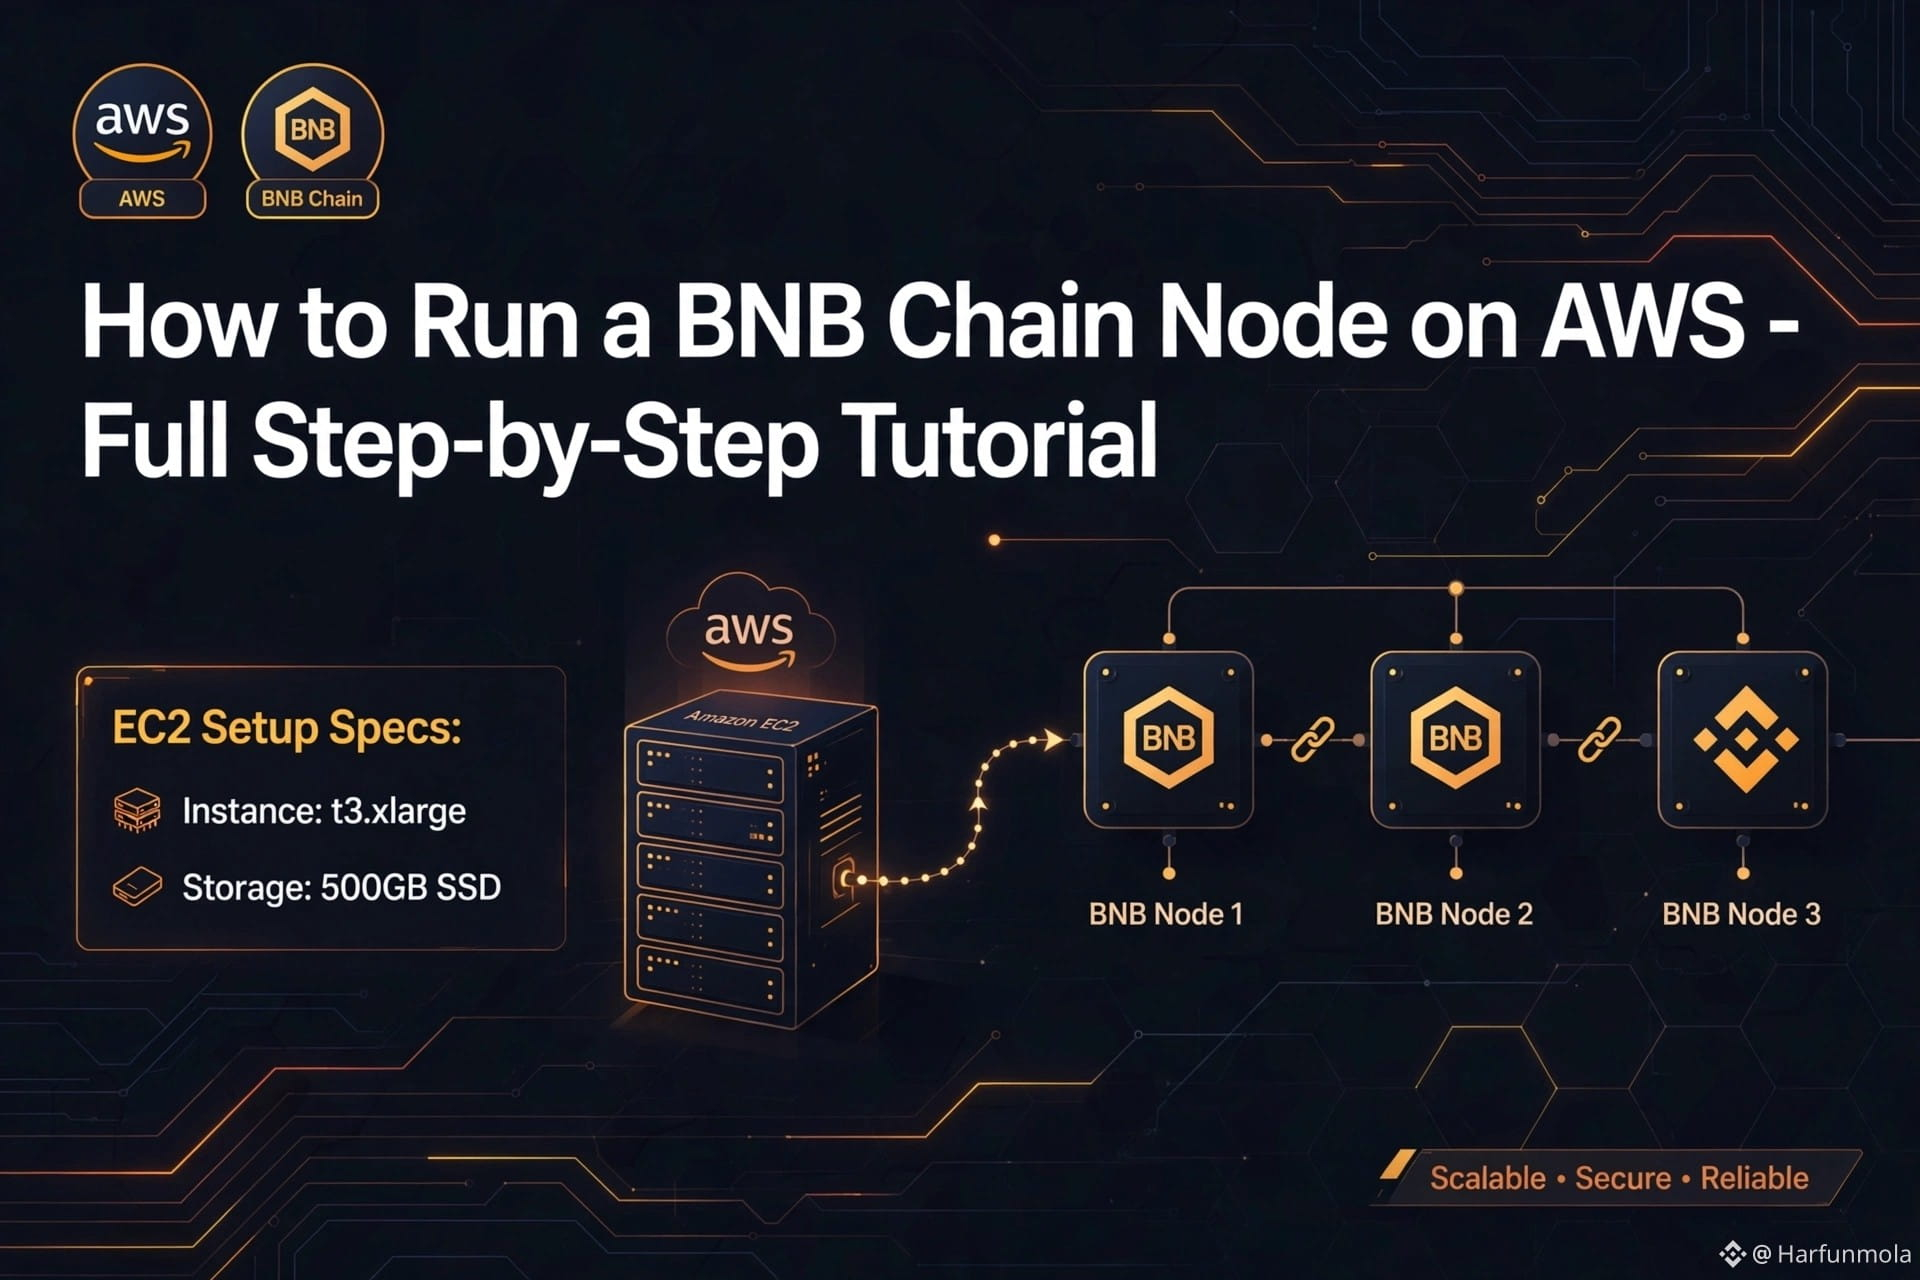
I couldn't attach the image. Want me to make it again?
*Copy karne ke liye text:*
🚀 *How to Run a BNB Chain Node on AWS - Full Step-by-Step Tutorial* $BNB
I've just deployed my own BNB Chain BSC Full Node on AWS and here's the complete guide for you!
*What you will learn:*
✅ EC2 Setup (Recommended: http://t3.xlarge, 500GB+ SSD)
✅ Install Dependencies & BSC Client (geth)
✅ Sync from Snapshot - Fast Sync
✅ Configure RPC & Peer Settings
✅ Monitoring & Auto-restart with systemd
✅ Cost optimization tips on AWS
AWS makes it super easy - high availability, secure, and scalable. Perfect for developers building on $BNB Chain, validators, and data indexing.
Full tutorial thread coming in comments! Drop a ❤️ if you want the GitHub repo + AWS CloudFormation template.
Let's BUILD on BNB Chain! 🔶
#BNBChain #AWS
I couldn't attach the image. Want me to make it again?
*Copy karne ke liye text:*
🚀 *How to Run a BNB Chain Node on AWS - Full Step-by-Step Tutorial* $BNB
I've just deployed my own BNB Chain BSC Full Node on AWS and here's the complete guide for you!
*What you will learn:*
✅ EC2 Setup (Recommended: http://t3.xlarge, 500GB+ SSD)
✅ Install Dependencies & BSC Client (geth)
✅ Sync from Snapshot - Fast Sync
✅ Configure RPC & Peer Settings
✅ Monitoring & Auto-restart with systemd
✅ Cost optimization tips on AWS
AWS makes it super easy - high availability, secure, and scalable. Perfect for developers building on $BNB Chain, validators, and data indexing.
Full tutorial thread coming in comments! Drop a ❤️ if you want the GitHub repo + AWS CloudFormation template.
Let's BUILD on BNB Chain! 🔶
#BNBChain #AWS
*Copy karne ke liye text:*
🚀 *How to Run a BNB Chain Node on AWS - Full Step-by-Step Tutorial* $BNB
I've just deployed my own BNB Chain BSC Full Node on AWS and here's the complete guide for you!
*What you will learn:*
✅ EC2 Setup (Recommended: http://t3.xlarge, 500GB+ SSD)
✅ Install Dependencies & BSC Client (geth)
✅ Sync from Snapshot - Fast Sync
✅ Configure RPC & Peer Settings
✅ Monitoring & Auto-restart with systemd
✅ Cost optimization tips on AWS
AWS makes it super easy - high availability, secure, and scalable. Perfect for developers building on $BNB Chain, validators, and data indexing.
Full tutorial thread coming in comments! Drop a ❤️ if you want the GitHub repo + AWS CloudFormation template.
Let's BUILD on BNB Chain! 🔶
#BNBChain #AWS
1
1
91
·
--
The eve of Amazon’s AMZN earnings: The stock hasn’t fallen much, but the test is tougher than Google’s.
First, where things stand: At the close of U.S. trading on October 26, Amazon (AMZN) was at $249.09, up 0.44% for the day, with an intraday range of $247.23 to $250.79. Don’t be fooled by that small daily gain: the stock is still below its 50-day moving average of about $255, but holding above its 200-day moving average of about $243. Its 52-week range is $196 to $287.20, leaving the current price about 13% below its high—a classic pre-earnings position caught in the middle, neither up nor down.
Earnings are just around the corner: Amazon will report its third-quarter results after the U.S. market closes on October 29 (early morning on October 30 Beijing time). The market expects earnings per share of about $1.96 and revenue of about $202.2 billion, up roughly 12% from about $180.2 billion in the same period last year. The company’s own guidance is for sales of $197 billion to $202 billion and operating income of $22.5 billion to $26.5 billion. Expectations are basically hugging the top of the guidance range, leaving little room for error.
Three things to watch, in order of importance: First, can AWS sustain its high growth? Last quarter, AWS revenue was $42.2 billion, up 37% year over year—its fastest growth in 18 quarters—with a backlog of about $496 billion. The market expects growth to cool to the 30%–35% range in the third quarter; a dip below that range could easily trigger selling. Second, capital spending: The 2026 forecast has already been raised from $200 billion to $220 billion, and spending in the second half is expected to reach about $61 billion per quarter. Free cash flow is already slightly negative, so any further increase would be a negative. Third, e-commerce itself: Third-quarter growth will be weighed down by Prime Day shifting into the second quarter, by about 4 percentage points. Slower headline growth doesn’t necessarily mean the business is deteriorating. Advertising was a bright spot last quarter, growing 26% to $19.8 billion.
There’s another distortion that’s easy to overlook: Last quarter’s earnings per share of $5.75 included about $53.4 billion in paper gains on Amazon’s Anthropic stake. Treating that as operating profit would seriously overstate the company’s earning power, so on earnings night, look at the underlying operating performance excluding those gains.
The options market is pricing in a post-earnings move of about 7%, while Amazon’s reactions after its previous two earnings reports were a gain of about 10.9% in July and a drop of about 13.5% in February—both larger than implied volatility. In other words, betting on direction on earnings night isn’t a great wager for retail investors.
My view: Amazon’s three engines—e-commerce, AWS, and advertising—are all still running, but the market is now asking just one question: When will that $220 billion in spending turn into free cash flow? So I’m not betting on direction on the eve of earnings. If AWS holds above 30% growth, spending doesn’t exceed expectations, and operating income guidance isn’t weak, a pullback could be an opportunity to watch. If AWS slows significantly or spending is ramped up again, don’t rush to catch a falling knife if the stock breaks below the 200-day moving average area.
This is personal research and not investment advice. Will you hold through earnings, or wait for the dust to settle before deciding?
$AMZN #Amazon #亚马逊 #美股财报 #AWS
The eve of Amazon’s AMZN earnings: The stock hasn’t fallen much, but the test is tougher than Google’s.
First, where things stand: At the close of U.S. trading on October 26, Amazon (AMZN) was at $249.09, up 0.44% for the day, with an intraday range of $247.23 to $250.79. Don’t be fooled by that small daily gain: the stock is still below its 50-day moving average of about $255, but holding above its 200-day moving average of about $243. Its 52-week range is $196 to $287.20, leaving the current price about 13% below its high—a classic pre-earnings position caught in the middle, neither up nor down.
Earnings are just around the corner: Amazon will report its third-quarter results after the U.S. market closes on October 29 (early morning on October 30 Beijing time). The market expects earnings per share of about $1.96 and revenue of about $202.2 billion, up roughly 12% from about $180.2 billion in the same period last year. The company’s own guidance is for sales of $197 billion to $202 billion and operating income of $22.5 billion to $26.5 billion. Expectations are basically hugging the top of the guidance range, leaving little room for error.
Three things to watch, in order of importance: First, can AWS sustain its high growth? Last quarter, AWS revenue was $42.2 billion, up 37% year over year—its fastest growth in 18 quarters—with a backlog of about $496 billion. The market expects growth to cool to the 30%–35% range in the third quarter; a dip below that range could easily trigger selling. Second, capital spending: The 2026 forecast has already been raised from $200 billion to $220 billion, and spending in the second half is expected to reach about $61 billion per quarter. Free cash flow is already slightly negative, so any further increase would be a negative. Third, e-commerce itself: Third-quarter growth will be weighed down by Prime Day shifting into the second quarter, by about 4 percentage points. Slower headline growth doesn’t necessarily mean the business is deteriorating. Advertising was a bright spot last quarter, growing 26% to $19.8 billion.
There’s another distortion that’s easy to overlook: Last quarter’s earnings per share of $5.75 included about $53.4 billion in paper gains on Amazon’s Anthropic stake. Treating that as operating profit would seriously overstate the company’s earning power, so on earnings night, look at the underlying operating performance excluding those gains.
The options market is pricing in a post-earnings move of about 7%, while Amazon’s reactions after its previous two earnings reports were a gain of about 10.9% in July and a drop of about 13.5% in February—both larger than implied volatility. In other words, betting on direction on earnings night isn’t a great wager for retail investors.
My view: Amazon’s three engines—e-commerce, AWS, and advertising—are all still running, but the market is now asking just one question: When will that $220 billion in spending turn into free cash flow? So I’m not betting on direction on the eve of earnings. If AWS holds above 30% growth, spending doesn’t exceed expectations, and operating income guidance isn’t weak, a pullback could be an opportunity to watch. If AWS slows significantly or spending is ramped up again, don’t rush to catch a falling knife if the stock breaks below the 200-day moving average area.
This is personal research and not investment advice. Will you hold through earnings, or wait for the dust to settle before deciding?
$AMZN #Amazon #亚马逊 #美股财报 #AWS
First, where things stand: At the close of U.S. trading on October 26, Amazon (AMZN) was at $249.09, up 0.44% for the day, with an intraday range of $247.23 to $250.79. Don’t be fooled by that small daily gain: the stock is still below its 50-day moving average of about $255, but holding above its 200-day moving average of about $243. Its 52-week range is $196 to $287.20, leaving the current price about 13% below its high—a classic pre-earnings position caught in the middle, neither up nor down.
Earnings are just around the corner: Amazon will report its third-quarter results after the U.S. market closes on October 29 (early morning on October 30 Beijing time). The market expects earnings per share of about $1.96 and revenue of about $202.2 billion, up roughly 12% from about $180.2 billion in the same period last year. The company’s own guidance is for sales of $197 billion to $202 billion and operating income of $22.5 billion to $26.5 billion. Expectations are basically hugging the top of the guidance range, leaving little room for error.
Three things to watch, in order of importance: First, can AWS sustain its high growth? Last quarter, AWS revenue was $42.2 billion, up 37% year over year—its fastest growth in 18 quarters—with a backlog of about $496 billion. The market expects growth to cool to the 30%–35% range in the third quarter; a dip below that range could easily trigger selling. Second, capital spending: The 2026 forecast has already been raised from $200 billion to $220 billion, and spending in the second half is expected to reach about $61 billion per quarter. Free cash flow is already slightly negative, so any further increase would be a negative. Third, e-commerce itself: Third-quarter growth will be weighed down by Prime Day shifting into the second quarter, by about 4 percentage points. Slower headline growth doesn’t necessarily mean the business is deteriorating. Advertising was a bright spot last quarter, growing 26% to $19.8 billion.
There’s another distortion that’s easy to overlook: Last quarter’s earnings per share of $5.75 included about $53.4 billion in paper gains on Amazon’s Anthropic stake. Treating that as operating profit would seriously overstate the company’s earning power, so on earnings night, look at the underlying operating performance excluding those gains.
The options market is pricing in a post-earnings move of about 7%, while Amazon’s reactions after its previous two earnings reports were a gain of about 10.9% in July and a drop of about 13.5% in February—both larger than implied volatility. In other words, betting on direction on earnings night isn’t a great wager for retail investors.
My view: Amazon’s three engines—e-commerce, AWS, and advertising—are all still running, but the market is now asking just one question: When will that $220 billion in spending turn into free cash flow? So I’m not betting on direction on the eve of earnings. If AWS holds above 30% growth, spending doesn’t exceed expectations, and operating income guidance isn’t weak, a pullback could be an opportunity to watch. If AWS slows significantly or spending is ramped up again, don’t rush to catch a falling knife if the stock breaks below the 200-day moving average area.
This is personal research and not investment advice. Will you hold through earnings, or wait for the dust to settle before deciding?
$AMZN #Amazon #亚马逊 #美股财报 #AWS
67
Amazon CEO Andy Jassy said during an interview with a16z that AWS’s computing capacity for 2026 is already sold out, 2027 is basically fully booked, and a substantial portion of 2028 is already committed. The company is spending about $220 billion on capital expenditures this year, and his exact words were: “There will still be a tremendous amount of unmet demand.” Even more staggering: its in-house Trainium chips have secured over $225 billion in future orders. AWS reported second-quarter revenue of $42.2 billion, up 37% year over year, or $169 billion annualized. But here’s the other side: free cash flow was negative $7.6 billion over the past 12 months, and Deutsche Bank has raised its 2027 capex forecast to about $330 billion. If $220 billion can’t buy enough capacity, is this a genuine shortage or has the spending frenzy gone too far? Pick a side in the comments: A) It’s a real shortage—orders booked through 2028 prove it; B) When the financials turn, this kind of spend-at-all-costs narrative will be the first bubble to burst.
$BTC $ETH $SOL
#亚马逊 #AWS #AI computing power
Amazon CEO Andy Jassy said during an interview with a16z that AWS’s computing capacity for 2026 is already sold out, 2027 is basically fully booked, and a substantial portion of 2028 is already committed. The company is spending about $220 billion on capital expenditures this year, and his exact words were: “There will still be a tremendous amount of unmet demand.” Even more staggering: its in-house Trainium chips have secured over $225 billion in future orders. AWS reported second-quarter revenue of $42.2 billion, up 37% year over year, or $169 billion annualized. But here’s the other side: free cash flow was negative $7.6 billion over the past 12 months, and Deutsche Bank has raised its 2027 capex forecast to about $330 billion. If $220 billion can’t buy enough capacity, is this a genuine shortage or has the spending frenzy gone too far? Pick a side in the comments: A) It’s a real shortage—orders booked through 2028 prove it; B) When the financials turn, this kind of spend-at-all-costs narrative will be the first bubble to burst.
$BTC $ETH $SOL
#亚马逊 #AWS #AI computing power
$BTC $ETH $SOL
#亚马逊 #AWS #AI computing power
43
·
--
🚀 AMAZON (AMZN): Can AWS and AI Drive the Next Growth Wave?
$AMZNB
{spot}(AMZNBUSDT)
Amazon is more than an online shopping giant. Its cloud business and AI investments are becoming increasingly important to its future.
🔹 AWS Growth: Amazon Web Services remains a key business to watch as companies expand their cloud infrastructure.
🔹 AI Investment: Amazon is investing in AI technology and infrastructure to compete in the rapidly growing AI market.
🔹 Earnings Spotlight: Investors will be watching revenue growth, operating profit, AWS performance, and capital spending.
🔹 Big Question: Can Amazon turn its massive AI investments into stronger long-term profits?
🔹 Key Risks: Rising costs, intense competition, and weaker-than-expected guidance could pressure the stock.
📊 My Take: Amazon has multiple growth opportunities, but investors should focus on financial results rather than hype alone.
⚠️ Earnings announcements can trigger sharp price movements in either direction. Always assess the risks before investing.
#Amazon #AMZN #AWS #artificialintelligence #stockmarket
Disclaimer: This post is for educational purposes only and is not financial advice. Always do your own research (DYOR).
🚀 AMAZON (AMZN): Can AWS and AI Drive the Next Growth Wave?
$AMZNB
Amazon is more than an online shopping giant. Its cloud business and AI investments are becoming increasingly important to its future.
🔹 AWS Growth: Amazon Web Services remains a key business to watch as companies expand their cloud infrastructure.
🔹 AI Investment: Amazon is investing in AI technology and infrastructure to compete in the rapidly growing AI market.
🔹 Earnings Spotlight: Investors will be watching revenue growth, operating profit, AWS performance, and capital spending.
🔹 Big Question: Can Amazon turn its massive AI investments into stronger long-term profits?
🔹 Key Risks: Rising costs, intense competition, and weaker-than-expected guidance could pressure the stock.
📊 My Take: Amazon has multiple growth opportunities, but investors should focus on financial results rather than hype alone.
⚠️ Earnings announcements can trigger sharp price movements in either direction. Always assess the risks before investing.
#Amazon #AMZN #AWS #artificialintelligence #stockmarket
Disclaimer: This post is for educational purposes only and is not financial advice. Always do your own research (DYOR).
$AMZNB
Amazon is more than an online shopping giant. Its cloud business and AI investments are becoming increasingly important to its future.
🔹 AWS Growth: Amazon Web Services remains a key business to watch as companies expand their cloud infrastructure.
🔹 AI Investment: Amazon is investing in AI technology and infrastructure to compete in the rapidly growing AI market.
🔹 Earnings Spotlight: Investors will be watching revenue growth, operating profit, AWS performance, and capital spending.
🔹 Big Question: Can Amazon turn its massive AI investments into stronger long-term profits?
🔹 Key Risks: Rising costs, intense competition, and weaker-than-expected guidance could pressure the stock.
📊 My Take: Amazon has multiple growth opportunities, but investors should focus on financial results rather than hype alone.
⚠️ Earnings announcements can trigger sharp price movements in either direction. Always assess the risks before investing.
#Amazon #AMZN #AWS #artificialintelligence #stockmarket
Disclaimer: This post is for educational purposes only and is not financial advice. Always do your own research (DYOR).
61

AWS Cloud Services Outlook for 2027: Capacity Fully Booked Through 2028
Amazon CEO Andy Jassy revealed that a surge in demand for AI infrastructure has fully booked AWS cloud computing capacity through 2027, with no spare capacity expected in 2028 either. Technical analysts say this is worth watching, as it could signal a new wave of growth potential in the cloud computing market.#AWS #CloudComputing
AWS Cloud Services Outlook for 2027: Capacity Fully Booked Through 2028
Amazon CEO Andy Jassy revealed that a surge in demand for AI infrastructure has fully booked AWS cloud computing capacity through 2027, with no spare capacity expected in 2028 either. Technical analysts say this is worth watching, as it could signal a new wave of growth potential in the cloud computing market.#AWS #CloudComputing
Amazon CEO Andy Jassy revealed that a surge in demand for AI infrastructure has fully booked AWS cloud computing capacity through 2027, with no spare capacity expected in 2028 either. Technical analysts say this is worth watching, as it could signal a new wave of growth potential in the cloud computing market.#AWS #CloudComputing
16
·
--
AWS Deep Insight Unlocks a New Perspective on Production
For those tracking funding, AWS has launched the Deep Insight multi-agent system to help you keep a close eye on production challenges. Combining Anthropic technology with AWS cloud, it automatically analyzes data for deeper insights. Three deployment options—self-hosted, web, and managed AgentCore—flexibly adapt to different needs. #资金追踪 #智能生产 #AWS
AWS Deep Insight Unlocks a New Perspective on Production
For those tracking funding, AWS has launched the Deep Insight multi-agent system to help you keep a close eye on production challenges. Combining Anthropic technology with AWS cloud, it automatically analyzes data for deeper insights. Three deployment options—self-hosted, web, and managed AgentCore—flexibly adapt to different needs. #资金追踪 #智能生产 #AWS
For those tracking funding, AWS has launched the Deep Insight multi-agent system to help you keep a close eye on production challenges. Combining Anthropic technology with AWS cloud, it automatically analyzes data for deeper insights. Three deployment options—self-hosted, web, and managed AgentCore—flexibly adapt to different needs. #资金追踪 #智能生产 #AWS
33
🤖🔥 AI infrastructure is heating up. Railway raises $100M to challenge AWS, cutting costs by 50% and building its own data centers. This competitive pressure could impact tech sector valuations. 🚀 #AWS #AI #ArtificialIntelligence #AINews #CryptoverseNews
Full story: https://cryptoversenews.eu/ai/railway-secures-100-million-to-challenge-aws-with-ai-native/
🤖🔥 AI infrastructure is heating up. Railway raises $100M to challenge AWS, cutting costs by 50% and building its own data centers. This competitive pressure could impact tech sector valuations. 🚀 #AWS #AI #ArtificialIntelligence #AINews #CryptoverseNews
Full story: https://cryptoversenews.eu/ai/railway-secures-100-million-to-challenge-aws-with-ai-native/
Full story: https://cryptoversenews.eu/ai/railway-secures-100-million-to-challenge-aws-with-ai-native/
92
·
--
$AMZN 的云业务负责人 Matt Garman 昨天甩出一份承诺,姿态很硬。
未来五年,他掌管的部门会往数据中心所在的社区投 10 亿美元,钱怎么用由当地自己定:教育、职业培训、能源账单、水资源保护都能填进去。配套动作是放弃跟地方政府签保密协议,改成开放日让居民进来看。
他把国内这轮反弹归到外部,点名全国正在审议的 100 多项暂停令,说美国输不起这场竞赛。环保组织 Stand.Earth 当场反驳,说这份承诺回避了公司在德州新建的那座电厂,预计每年 3300 万吨空气污染,用电量相当于 190 万户家庭。
一边加注表态,一边被追着算旧账。10 亿美元对上一整年 2200 亿美元的资本开支,比例落在两百二十分之一附近。
#AMZN #AWS
$AMZN 的云业务负责人 Matt Garman 昨天甩出一份承诺,姿态很硬。
未来五年,他掌管的部门会往数据中心所在的社区投 10 亿美元,钱怎么用由当地自己定:教育、职业培训、能源账单、水资源保护都能填进去。配套动作是放弃跟地方政府签保密协议,改成开放日让居民进来看。
他把国内这轮反弹归到外部,点名全国正在审议的 100 多项暂停令,说美国输不起这场竞赛。环保组织 Stand.Earth 当场反驳,说这份承诺回避了公司在德州新建的那座电厂,预计每年 3300 万吨空气污染,用电量相当于 190 万户家庭。
一边加注表态,一边被追着算旧账。10 亿美元对上一整年 2200 亿美元的资本开支,比例落在两百二十分之一附近。
#AMZN #AWS
未来五年,他掌管的部门会往数据中心所在的社区投 10 亿美元,钱怎么用由当地自己定:教育、职业培训、能源账单、水资源保护都能填进去。配套动作是放弃跟地方政府签保密协议,改成开放日让居民进来看。
他把国内这轮反弹归到外部,点名全国正在审议的 100 多项暂停令,说美国输不起这场竞赛。环保组织 Stand.Earth 当场反驳,说这份承诺回避了公司在德州新建的那座电厂,预计每年 3300 万吨空气污染,用电量相当于 190 万户家庭。
一边加注表态,一边被追着算旧账。10 亿美元对上一整年 2200 亿美元的资本开支,比例落在两百二十分之一附近。
#AMZN #AWS
91

⚠️ Amazon fixes a major billing error in AWS that threatens crypto companies!
Amazon revealed it has resolved a software bug in its AWS cloud service, where the billing system displayed inaccurate estimates reaching billions of dollars for customers. This issue raises questions about how much crypto companies rely on the tech giant's cloud infrastructure and the potential risks involved.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ OTHER
#AWS #Amazon #CloudComputing #CryptoInfrastructure #TechNews
🔗 Source: https://cryptobriefing.com/aws-billing-bug-crypto-infrastructure-risk/
⚠️ Amazon fixes a major billing error in AWS that threatens crypto companies!
Amazon revealed it has resolved a software bug in its AWS cloud service, where the billing system displayed inaccurate estimates reaching billions of dollars for customers. This issue raises questions about how much crypto companies rely on the tech giant's cloud infrastructure and the potential risks involved.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ OTHER
#AWS #Amazon #CloudComputing #CryptoInfrastructure #TechNews
🔗 Source: https://cryptobriefing.com/aws-billing-bug-crypto-infrastructure-risk/
Amazon revealed it has resolved a software bug in its AWS cloud service, where the billing system displayed inaccurate estimates reaching billions of dollars for customers. This issue raises questions about how much crypto companies rely on the tech giant's cloud infrastructure and the potential risks involved.
━━━━━━━━━━━━━━
📊 Impact: 📈 High
🏷️ OTHER
#AWS #Amazon #CloudComputing #CryptoInfrastructure #TechNews
🔗 Source: https://cryptobriefing.com/aws-billing-bug-crypto-infrastructure-risk/
23
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#NvidiaLoses$2.7TrillionInMonthAndAHalf
16,477 views
113 Discussing
2
#CanBTCReboundAfterFallingBelow60K?
732,977 views
2,934 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
265,205 views
1,969 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
30,570 views
88 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
134,831 views
1,193 Discussing
6
#TwentyOneCapitalAdds172.25BTC
61,462 views
650 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
7,591 views
50 Discussing
8
#BNBDropsBelow540USDTWith8.46%DailyDecline
74,156 views
640 Discussing
9
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
2,490 views
22 Discussing
10
#BitMineFaces$10.1BUnrealizedETHLoss
5,188 views
28 Discussing