
#backtesting
backtesting
30,733 views
2,114 Discussing
Hot
Latest
·
--
Backtesting methodologies help traders evaluate strategy performance. This is done by simulating trades on historical data. For example, a strategy is at 80% success rate on $BTC data from 2020. Forward-testing frameworks take this a step further by testing on new, unseen data. This helps confirm if a strategy is sitting at a high success rate. Traders use both methods to refine their approach, often using $ETH and $LTC data. By combining backtesting and forward-testing, traders can gain advanced insights into their strategy's effectiveness. Trading strategies can be improved with a success rate of 70% or higher. tradingstrategies #backtesting #cryptotrading
Backtesting methodologies help traders evaluate strategy performance. This is done by simulating trades on historical data. For example, a strategy is at 80% success rate on $BTC data from 2020. Forward-testing frameworks take this a step further by testing on new, unseen data. This helps confirm if a strategy is sitting at a high success rate. Traders use both methods to refine their approach, often using $ETH and $LTC data. By combining backtesting and forward-testing, traders can gain advanced insights into their strategy's effectiveness. Trading strategies can be improved with a success rate of 70% or higher. tradingstrategies #backtesting #cryptotrading
94

·
--
7 versions of my bot, running side by side
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
7 versions of my bot, running side by side
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
My futures bot (testnet funds) has a "shadow lab": alternative rule sets trade the same market on paper, each starting from 5,000 USDT. After 30 days, here is the table:
• Channel breakout 55/20: +1.3%, max drawdown −5.0%, 16 trades, 19% winners
• EMA 20/50 cross: +1.2%, max drawdown −3.0%, 8 trades, 12% winners
• RSI 30/70 pullback: +0.8%, max drawdown −0.2%, 1 trade
• Shorts only: +0.7%, max drawdown −0.5%, 2 trades still open
• Longs only: −0.5%, 1 trade
• Current rules without news mode: −0.9%, 4 trades, 0 winners
• No $BTC filter: −2.1%, 7 trades, 0 winners
What I take from it: not much yet. The two leaders are up thanks to open positions and a few winners; their average trade is still negative (−0.52R and −0.85R). Most variants have fewer than 10 closed trades, and my own rule is to compare only after 20–30 trades each.
One thing is already visible: removing the BTC trend filter made results worse, 7 trades and not a single winner.
How many trades do you need before you trust a paper or backtest result?
#TradingBot #Backtesting #Testnet
1
99

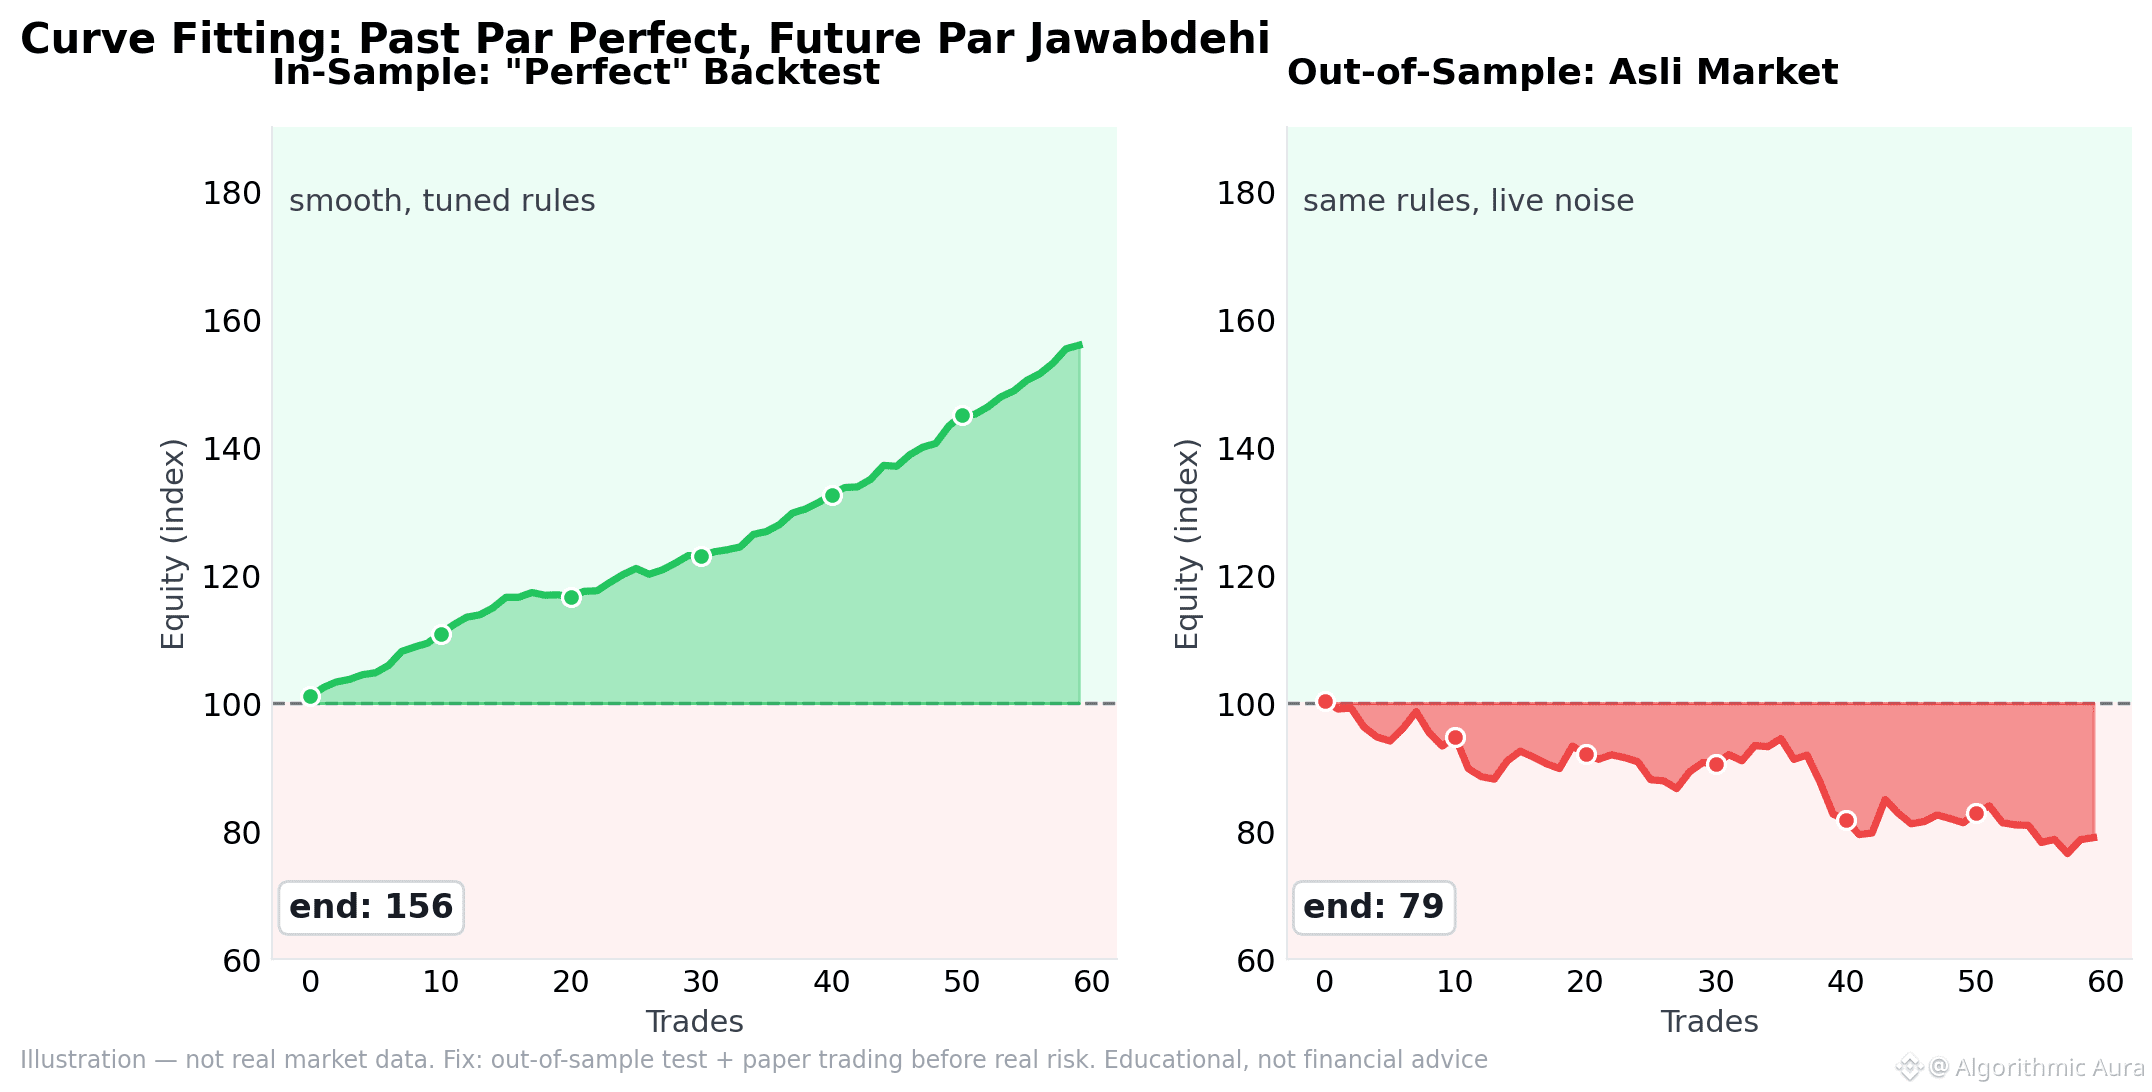
🧪 One chart: the most common backtesting trap — curve fitting.
Left: smooth upward in-sample results (rules tuned to the past). Right: the same rules out-of-sample — live noise, a different story.
1️⃣ Easy to fit: add 15 conditions and the past looks perfect
2️⃣ But that’s not a strategy, it’s memorization — future data won’t match that shape
3️⃣ Fix: out-of-sample testing, then paper trading
4️⃣ Sample size: 20 trades is not statistics
A backtest gives you a candidate, not certainty. Illustration — not real data.
$BTC #CryptoEducation #Backtesting #TradingStrategy
🧪 One chart: the most common backtesting trap — curve fitting.
Left: smooth upward in-sample results (rules tuned to the past). Right: the same rules out-of-sample — live noise, a different story.
1️⃣ Easy to fit: add 15 conditions and the past looks perfect
2️⃣ But that’s not a strategy, it’s memorization — future data won’t match that shape
3️⃣ Fix: out-of-sample testing, then paper trading
4️⃣ Sample size: 20 trades is not statistics
A backtest gives you a candidate, not certainty. Illustration — not real data.
$BTC #CryptoEducation #Backtesting #TradingStrategy
Left: smooth upward in-sample results (rules tuned to the past). Right: the same rules out-of-sample — live noise, a different story.
1️⃣ Easy to fit: add 15 conditions and the past looks perfect
2️⃣ But that’s not a strategy, it’s memorization — future data won’t match that shape
3️⃣ Fix: out-of-sample testing, then paper trading
4️⃣ Sample size: 20 trades is not statistics
A backtest gives you a candidate, not certainty. Illustration — not real data.
$BTC #CryptoEducation #Backtesting #TradingStrategy
5
🧪 Backtesting — testing the past, but the traps are still the same.
1️⃣ Benefit: a rough estimate of expectancy, without feelings
2️⃣ Trap 1 — curve fitting: if you tune it perfectly to the past, it won’t recognize the future; 15 conditions = not a strategy, just memorization
3️⃣ Trap 2 — small sample: 20 trades aren’t enough for statistics
4️⃣ Trap 3 — survivorship bias: leaving out data from dead coins and testing only the winners
5️⃣ Fix: out-of-sample testing + paper trading — does it still work today? The past won’t tell you
A backtest gives you a candidate, not certainty. The one who understands the difference wins the long race.
$BTC #CryptoEducation #TradingStrategy #Backtesting
🧪 Backtesting — testing the past, but the traps are still the same.
1️⃣ Benefit: a rough estimate of expectancy, without feelings
2️⃣ Trap 1 — curve fitting: if you tune it perfectly to the past, it won’t recognize the future; 15 conditions = not a strategy, just memorization
3️⃣ Trap 2 — small sample: 20 trades aren’t enough for statistics
4️⃣ Trap 3 — survivorship bias: leaving out data from dead coins and testing only the winners
5️⃣ Fix: out-of-sample testing + paper trading — does it still work today? The past won’t tell you
A backtest gives you a candidate, not certainty. The one who understands the difference wins the long race.
$BTC #CryptoEducation #TradingStrategy #Backtesting
1️⃣ Benefit: a rough estimate of expectancy, without feelings
2️⃣ Trap 1 — curve fitting: if you tune it perfectly to the past, it won’t recognize the future; 15 conditions = not a strategy, just memorization
3️⃣ Trap 2 — small sample: 20 trades aren’t enough for statistics
4️⃣ Trap 3 — survivorship bias: leaving out data from dead coins and testing only the winners
5️⃣ Fix: out-of-sample testing + paper trading — does it still work today? The past won’t tell you
A backtest gives you a candidate, not certainty. The one who understands the difference wins the long race.
$BTC #CryptoEducation #TradingStrategy #Backtesting
9
·
--
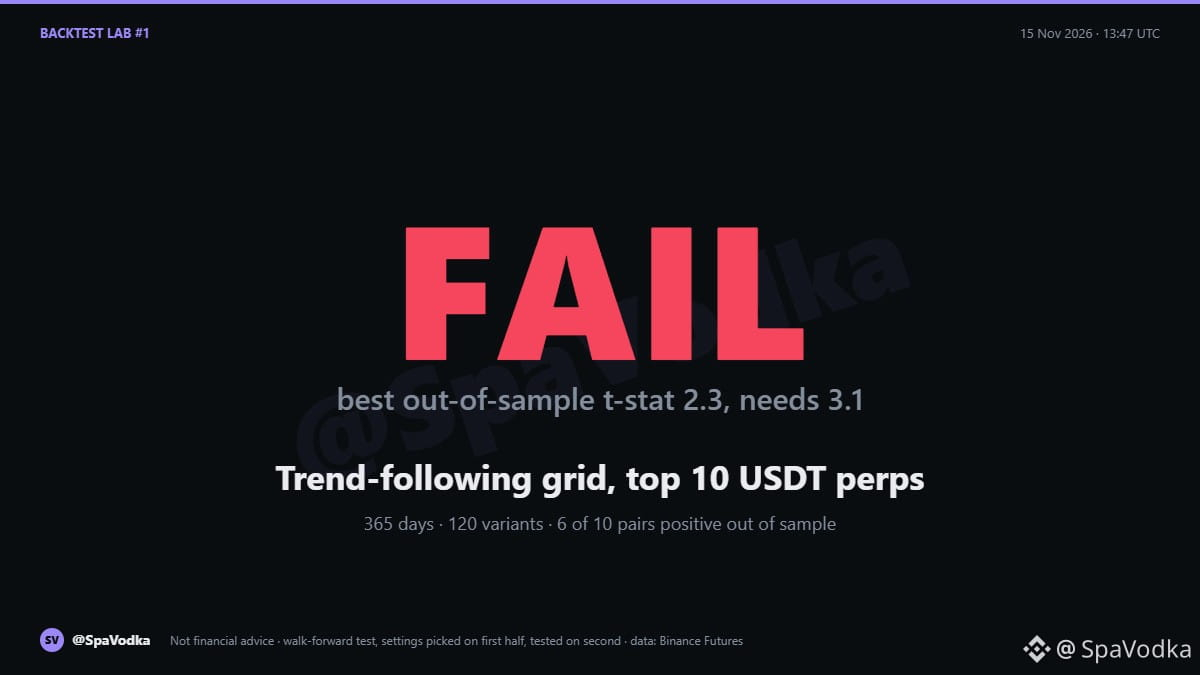
$NEAR made the most money out of sample, and the strategy still failed.
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
{future}(NEARUSDT)
$NEAR made the most money out of sample, and the strategy still failed.
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
Backtest Lab #1: does a grid that follows the trend actually work?
The idea: run a futures grid, but pick its direction from the daily trend. Long grid when price is above MA20 and MA7 is above MA25, short grid when both are below, neutral when MA7 and MA25 are within 3% of each other. Seven day runs, 3x, stop 1.5% outside the range, Binance fees included.
Data: top 10 USDT perps by volume, 365 days of 15m candles. Settings picked on the first half of the year only (12 variants per pair, 120 in total), then tested on the second half that the model never saw.
Result on unseen data: 6 of 10 pairs stayed positive. The best t-stat was 2.3 (SOL and NEAR). After trying 120 variants, a real edge needs at least 3.1. NEAR hit its stop in 38% of weekly runs. HYPE went from profit in training to a loss out of sample.
Verdict: FAIL. Positive numbers here are what you get by trying 120 versions and keeping the best one, not proof of an edge.
What I do with it: not trading it. Same verdict as my first run on 4 Nov, fresh data did not change it.
Next on the list: unlock windows, alt minus BTC beta, extreme funding reversals. Which one should I test next?
Not financial advice.
#Backtesting #tradingStrategy #gridtrading
253
🧪 Test your strategy on a demo first — that’s the benefit of paper trading.
1️⃣ Real market data, fake money — test rules without financial risk
2️⃣ Backtesting: run rules on historical data — wins, losses, max drawdown
3️⃣ Forward testing: check your discipline in live conditions
Why: BTC bounced from $74.8K to $77K today — a strategy for choppy days can only be verified with real data, not feelings.
After 30–50 paper trades, the pattern becomes clear: do the rules give you a real edge, or are your decisions mood-based?
Mistakes are cheap in a demo, expensive live. Test first, then trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
🧪 Test your strategy on a demo first — that’s the benefit of paper trading.
1️⃣ Real market data, fake money — test rules without financial risk
2️⃣ Backtesting: run rules on historical data — wins, losses, max drawdown
3️⃣ Forward testing: check your discipline in live conditions
Why: BTC bounced from $74.8K to $77K today — a strategy for choppy days can only be verified with real data, not feelings.
After 30–50 paper trades, the pattern becomes clear: do the rules give you a real edge, or are your decisions mood-based?
Mistakes are cheap in a demo, expensive live. Test first, then trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
1️⃣ Real market data, fake money — test rules without financial risk
2️⃣ Backtesting: run rules on historical data — wins, losses, max drawdown
3️⃣ Forward testing: check your discipline in live conditions
Why: BTC bounced from $74.8K to $77K today — a strategy for choppy days can only be verified with real data, not feelings.
After 30–50 paper trades, the pattern becomes clear: do the rules give you a real edge, or are your decisions mood-based?
Mistakes are cheap in a demo, expensive live. Test first, then trust. 🔬
$BTC
#PaperTrading #Backtesting #CryptoEducation
·
--
I tested 144 trading strategies on BTC, ETH and SOL. Here's what happened 🧪
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC, $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
I tested 144 trading strategies on BTC, ETH and SOL. Here's what happened 🧪
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC , $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
I built a bot on my phone (Termux) and backtested it on 1 year of hourly data from MEXC, with fees included and 10x leverage.
The setup:
• 70% of the data for training, 30% kept hidden for testing
• EMA crossovers and breakouts, with and without a trend filter
• ATR-based stops and different risk/reward ratios
The results:
• Only 22 of 144 combinations were profitable on the unseen data
• The "best" strategy in training LOST 61% on the test period
• Max drawdowns were over 100% at 10x leverage, which means a wiped account
• Simply holding $BTC , $ETH or $SOL returned about +18-20% in the same period, with no leverage
What I learned:
1. A strategy that looks great on past data often fails on new data (overfitting)
2. High leverage makes most edges disappear
3. Beating the market is much harder than it looks
I'm not trading real money with this. Next I'm testing slower timeframes and lower leverage, and I'll share the results either way.
Not financial advice. Past performance doesn't predict future results.
#BinanceSquare #crypto #Backtesting #TradingBots101 $BTC $ETH
148
·
--
Backtesting is a crucial step in evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy based on moving averages can be backtested on $BTC data from the past year. Forward-testing frameworks take it a step further by testing a strategy on new, unseen data. This helps to validate the strategy's performance. A strategy sitting at 80% success rate in backtesting may not perform as well in forward testing. For instance, a strategy that performed well on $ETH data may struggle with $BTC data. Understanding these methodologies is key to successful trading. Trading strategies and advanced analytics require careful evaluation. tradingstrategies #backtesting #cryptotrading
Backtesting is a crucial step in evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy based on moving averages can be backtested on $BTC data from the past year. Forward-testing frameworks take it a step further by testing a strategy on new, unseen data. This helps to validate the strategy's performance. A strategy sitting at 80% success rate in backtesting may not perform as well in forward testing. For instance, a strategy that performed well on $ETH data may struggle with $BTC data. Understanding these methodologies is key to successful trading. Trading strategies and advanced analytics require careful evaluation. tradingstrategies #backtesting #cryptotrading
24
When historical data doesn’t guarantee the future
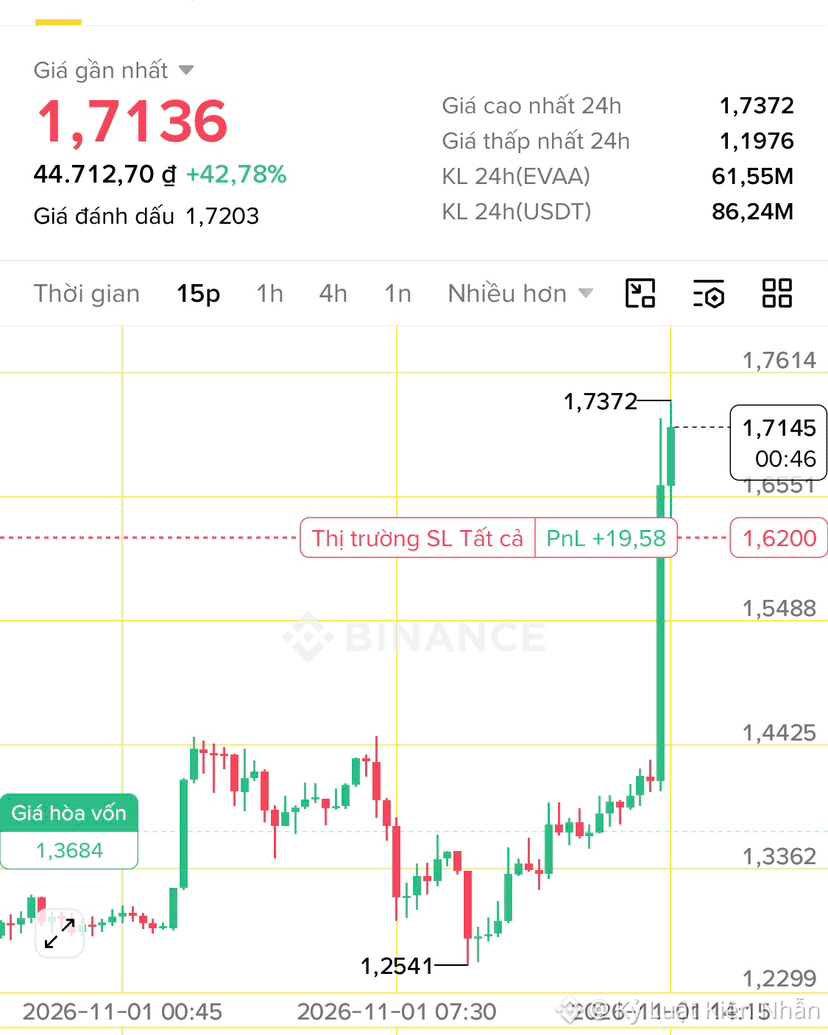
I once saw a strategy perform well on historical data and expected it to keep working.
But when market conditions changed, the actual results no longer matched what I had imagined.
My takeaway is that historical data is very useful for research, but it can’t guarantee the results of future trades.
$ETH $EVAA
Do you regularly re-evaluate your strategy when the market changes? Let’s discuss!
#Backtesting
When historical data doesn’t guarantee the future
I once saw a strategy perform well on historical data and expected it to keep working.
But when market conditions changed, the actual results no longer matched what I had imagined.
My takeaway is that historical data is very useful for research, but it can’t guarantee the results of future trades.
$ETH $EVAA
Do you regularly re-evaluate your strategy when the market changes? Let’s discuss!
#Backtesting
I once saw a strategy perform well on historical data and expected it to keep working.
But when market conditions changed, the actual results no longer matched what I had imagined.
My takeaway is that historical data is very useful for research, but it can’t guarantee the results of future trades.
$ETH $EVAA
Do you regularly re-evaluate your strategy when the market changes? Let’s discuss!
#Backtesting
1
1
228
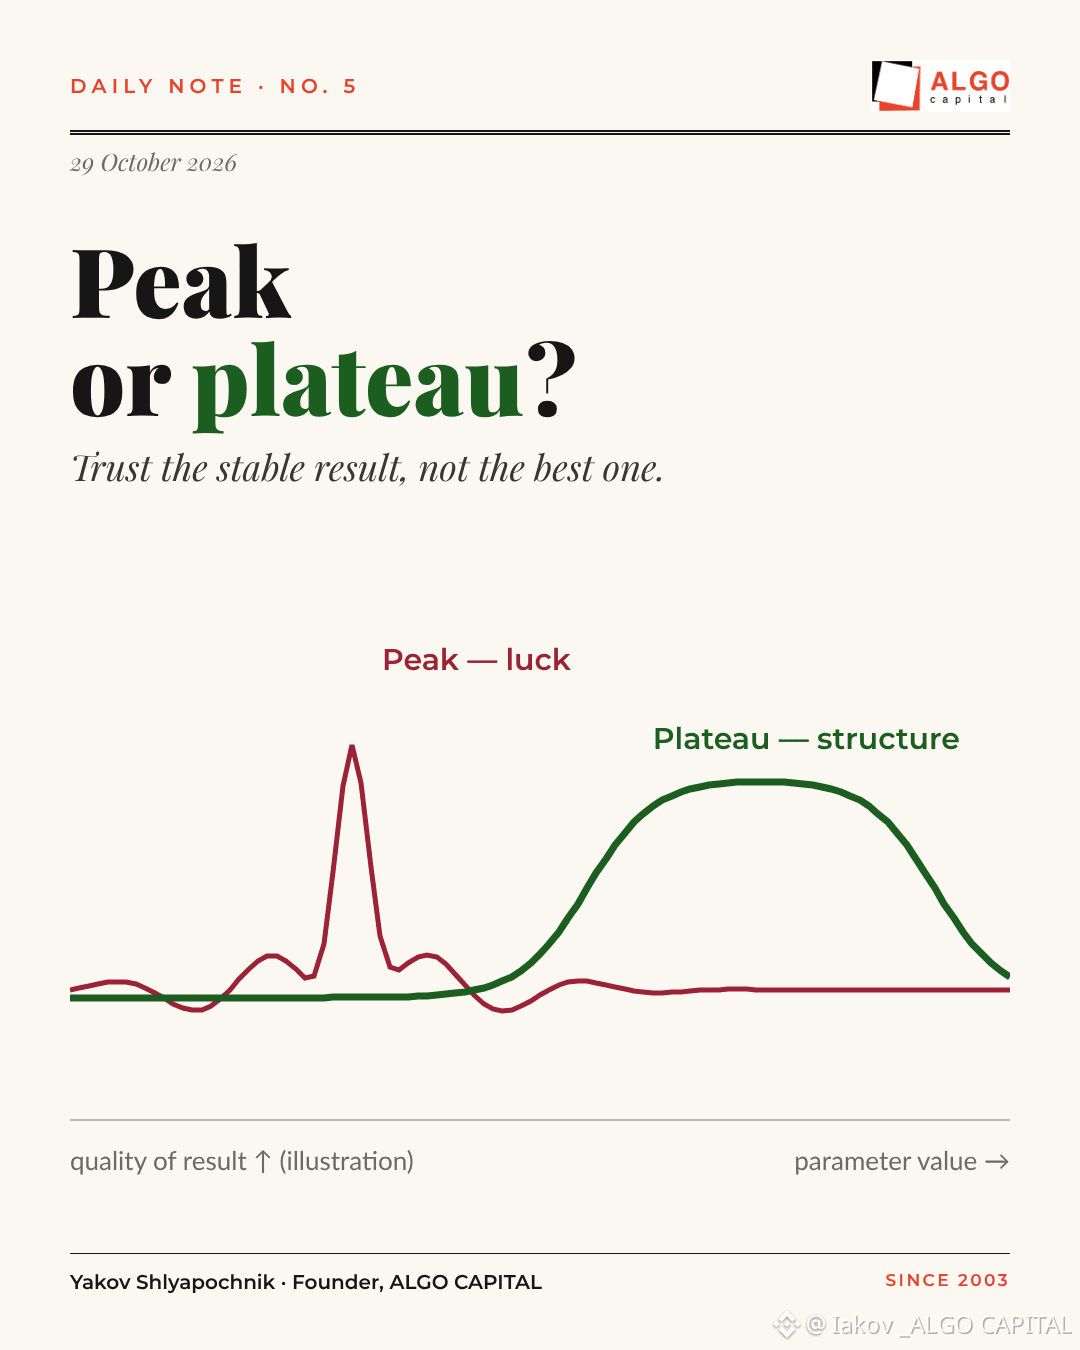
The most dangerous object in finance is a beautiful backtest.
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
The most dangerous object in finance is a beautiful backtest.
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
With enough parameters you can fit any history. The curve goes up and to the right — and tells you nothing about the future.
Three rules we use against self-deception:
1️⃣ Plateau, not peak. We choose parameters in the middle of a wide stable area, not at the single best point. A peak is luck; a plateau is structure.
2️⃣ Random in-sample and out-of-sample months, different for every test — so the hard months cannot hide.
3️⃣ Live trading is the only final judge. A backtest is a hypothesis; a real account is evidence.
If you remember one thing: be suspicious of the best result, trust the stable one.
#backtesting #quant #crypto
78
·
--
Backtesting is key to evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy using $BTC and $ETH can be backtested on data from the last year to see if it would have been profitable. Forward-testing frameworks take this a step further by testing the strategy on new, unseen data. This helps to confirm if the strategy is still effective when the market is sitting at current levels. Using a combination of backtesting and forward-testing can help traders refine their strategies and make more informed decisions. Trading with $BTC can be challenging but with the right approach it can be rewarding. tradingstrategies #backtesting #cryptotrading
Backtesting is key to evaluating trading strategies. It involves testing a strategy on historical data to see how it would have performed. For example, a strategy using $BTC and $ETH can be backtested on data from the last year to see if it would have been profitable. Forward-testing frameworks take this a step further by testing the strategy on new, unseen data. This helps to confirm if the strategy is still effective when the market is sitting at current levels. Using a combination of backtesting and forward-testing can help traders refine their strategies and make more informed decisions. Trading with $BTC can be challenging but with the right approach it can be rewarding. tradingstrategies #backtesting #cryptotrading
19
“You don’t want to backtest? Someone has done the homework for you.”
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
“You don’t want to backtest? Someone has done the homework for you.”
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
Backtesting may be time consuming and tiring, but it reveals your strategy’s win rate, risk-to-reward ratio, maximum drawndown, and whether you can trust it with real money.
I’ve tested my trading strategy across 1,000+ trades—focusing on maximizing returns with proper risk management.
Don’t want to do the research yourself?
You can build your own edge—or follow someone who already has.
You’re welcome to copy me, but remember: everyone has different risk appetite & stress tolerance. P.S. past performance doesn’t guarantee future results.
Trade smart and copy me.
#CryptoTrading #Backtesting #RiskManagement #CopyTrading
1
1
221
Article
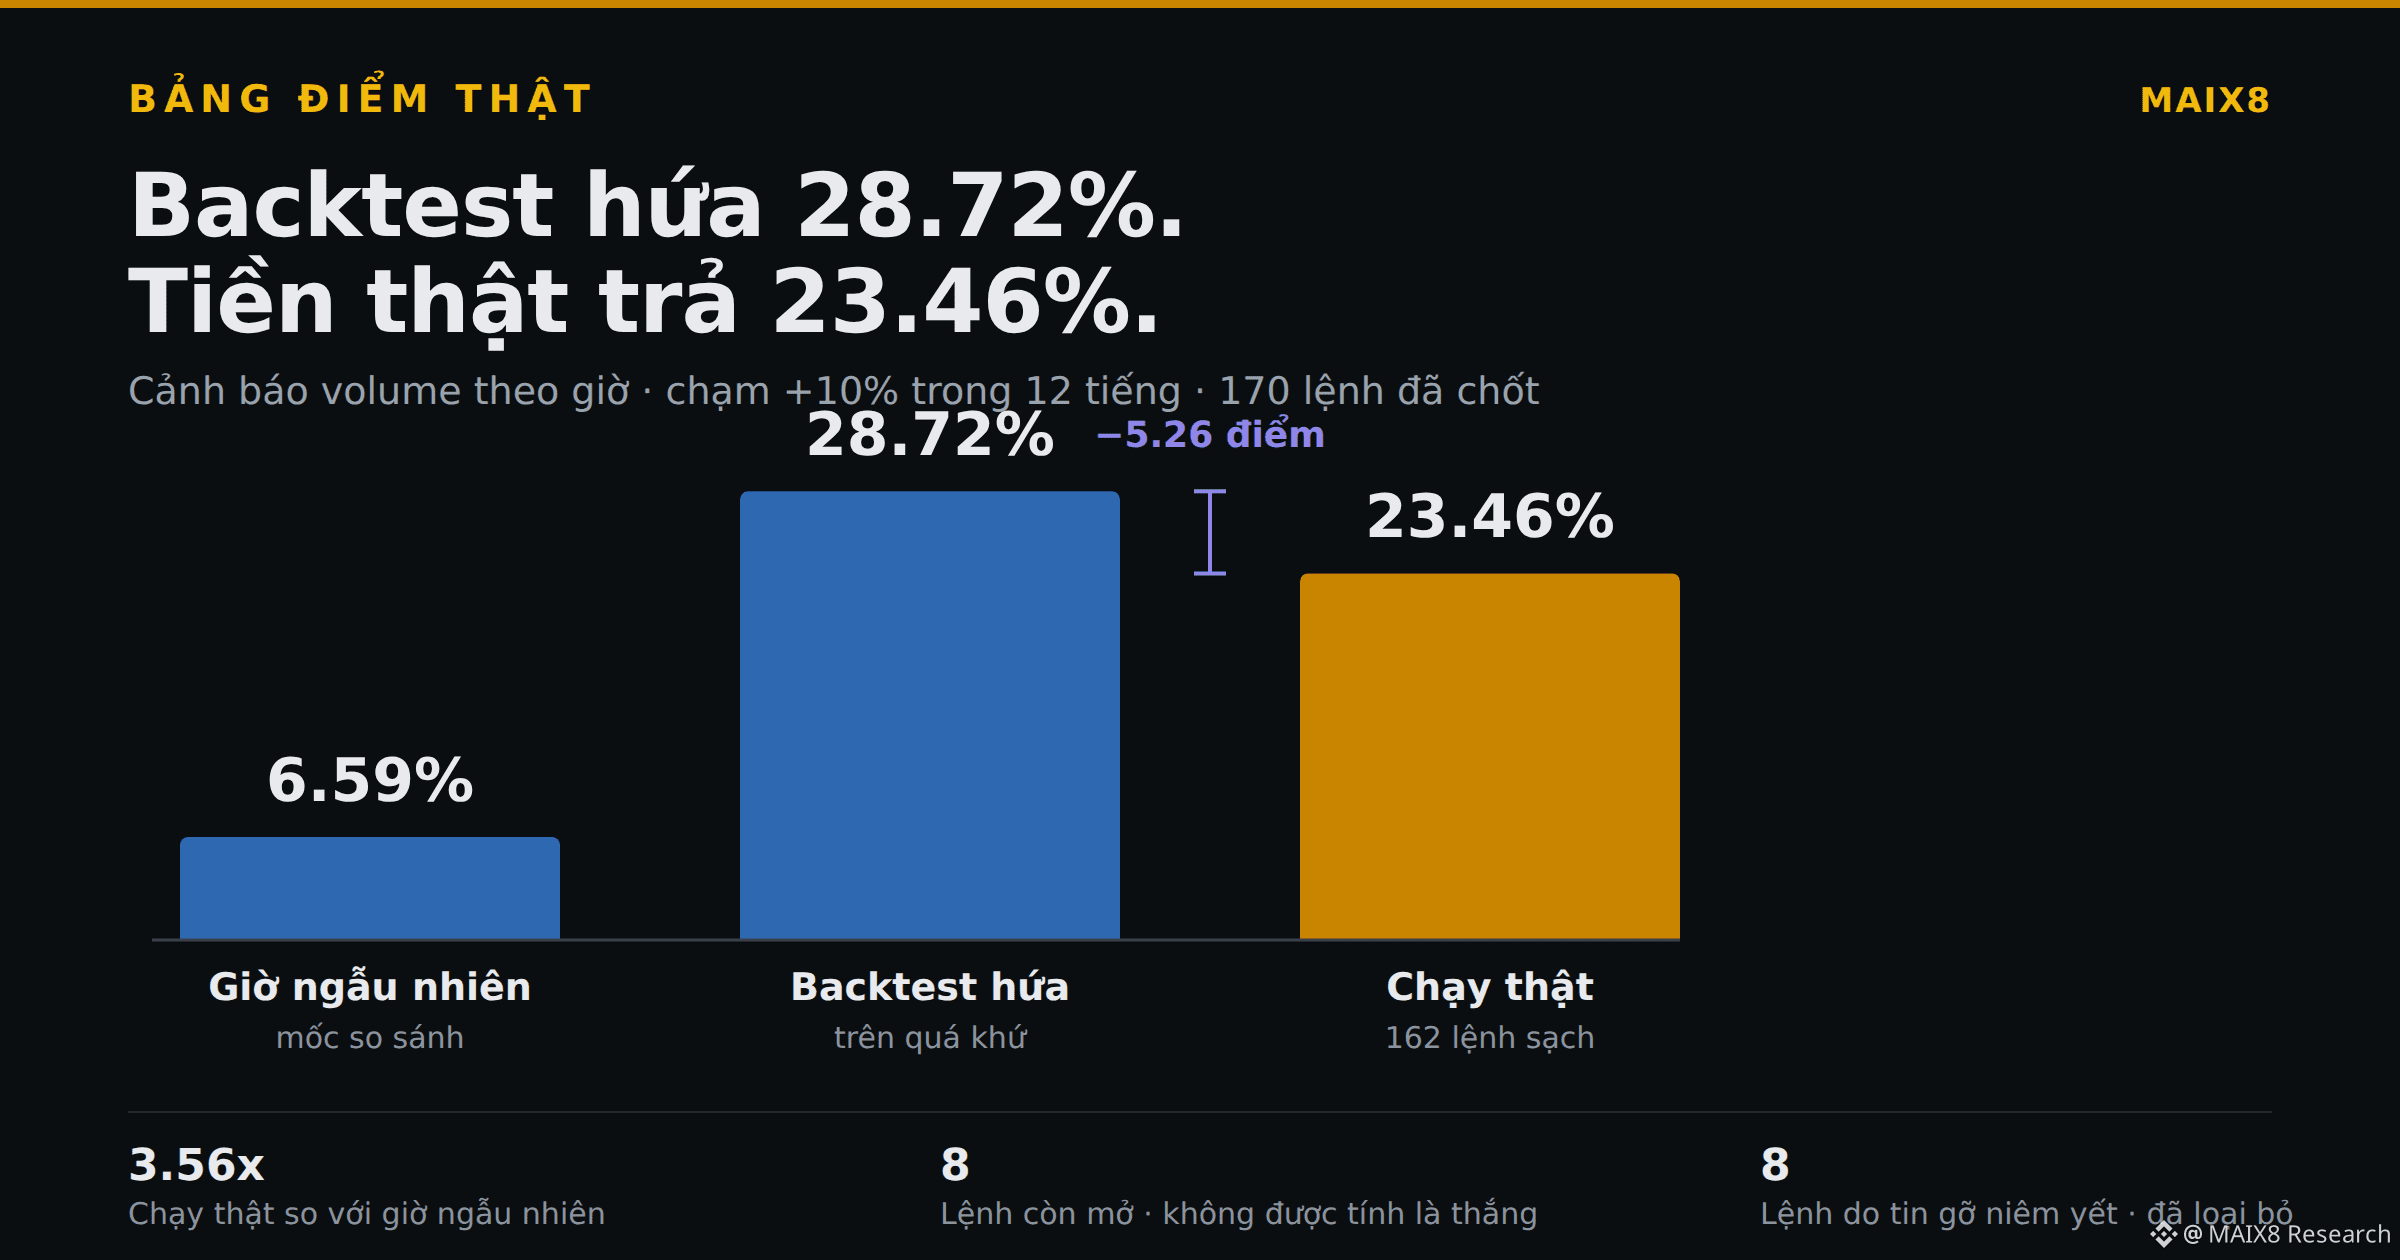
Backtest Promised 28.72%. Runs with Real Money Returns 23.46%.The backtest promised my hourly volume alerts would hit +10% within 12 hours—28.72% of the time.
The machine has been running for real. 170 alerts closed the window. Score:
**23.46%** on 162 clean orders.
Lower than the backtest by 5.26 points. Just as in every backtest: the real trade performs worse than the “paper” one.
But still **3.56 times** better than a random hour (6.59%). The edge is real, just smaller than the advertisement’s claim.
Three things that come with that number.
**One.** 8 warnings are still open and **are not counted**. A position not finished within the time window isn’t a win.
Backtest Promised 28.72%. Runs with Real Money Returns 23.46%.
The backtest promised my hourly volume alerts would hit +10% within 12 hours—28.72% of the time.
The machine has been running for real. 170 alerts closed the window. Score:
**23.46%** on 162 clean orders.
Lower than the backtest by 5.26 points. Just as in every backtest: the real trade performs worse than the “paper” one.
But still **3.56 times** better than a random hour (6.59%). The edge is real, just smaller than the advertisement’s claim.
Three things that come with that number.
**One.** 8 warnings are still open and **are not counted**. A position not finished within the time window isn’t a win.
The machine has been running for real. 170 alerts closed the window. Score:
**23.46%** on 162 clean orders.
Lower than the backtest by 5.26 points. Just as in every backtest: the real trade performs worse than the “paper” one.
But still **3.56 times** better than a random hour (6.59%). The edge is real, just smaller than the advertisement’s claim.
Three things that come with that number.
**One.** 8 warnings are still open and **are not counted**. A position not finished within the time window isn’t a win.
118
·
--
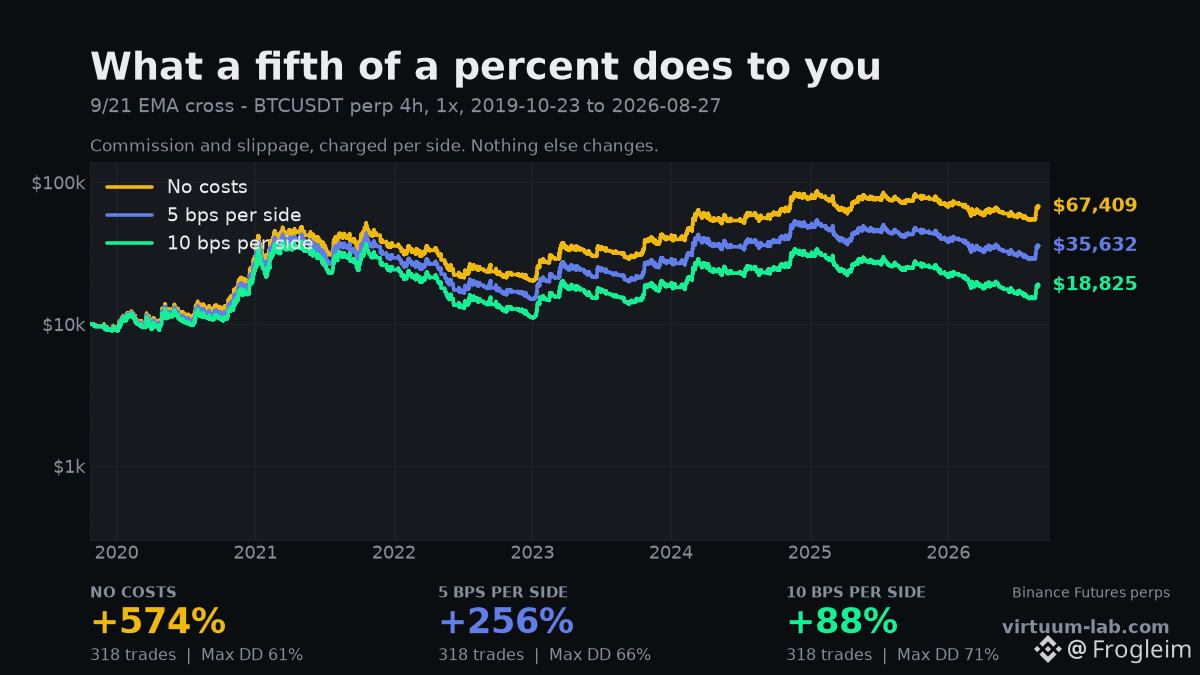
0.1% a trade cost this strategy 486 points.
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
0.1% a trade cost this strategy 486 points.
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
9/21 EMA cross on BTCUSDT perp, 4 hour bars, 1x, 2019-10-23 to today. 318 trades. The strategy never changes — only what each trade costs.
No costs at all: +574%
5 bps per side: +256%
10 bps per side: +88%
10 bps is 0.1%. It is roughly what you actually pay as a taker once spread and slippage are counted, and it turns a spectacular backtest into an ordinary one.
The reason it bites this hard is 318 trades. Cost is charged per trade, so it scales with activity while your edge does not. A slow strategy can ignore fees. A strategy that trades every few days cannot — it is paying rent 318 times.
This is why the most common backtesting mistake isn't a bad indicator. It's a zero in the fee box. Every high-frequency strategy looks brilliant at 0 bps.
If your backtester doesn't charge commission and slippage per side, it isn't testing your strategy. It's testing a fantasy version that trades for free.
Charge yourself what your exchange charges you 👉 https://virtuum-lab.com
#BTC #TradingFees #Backtesting
151
·
--
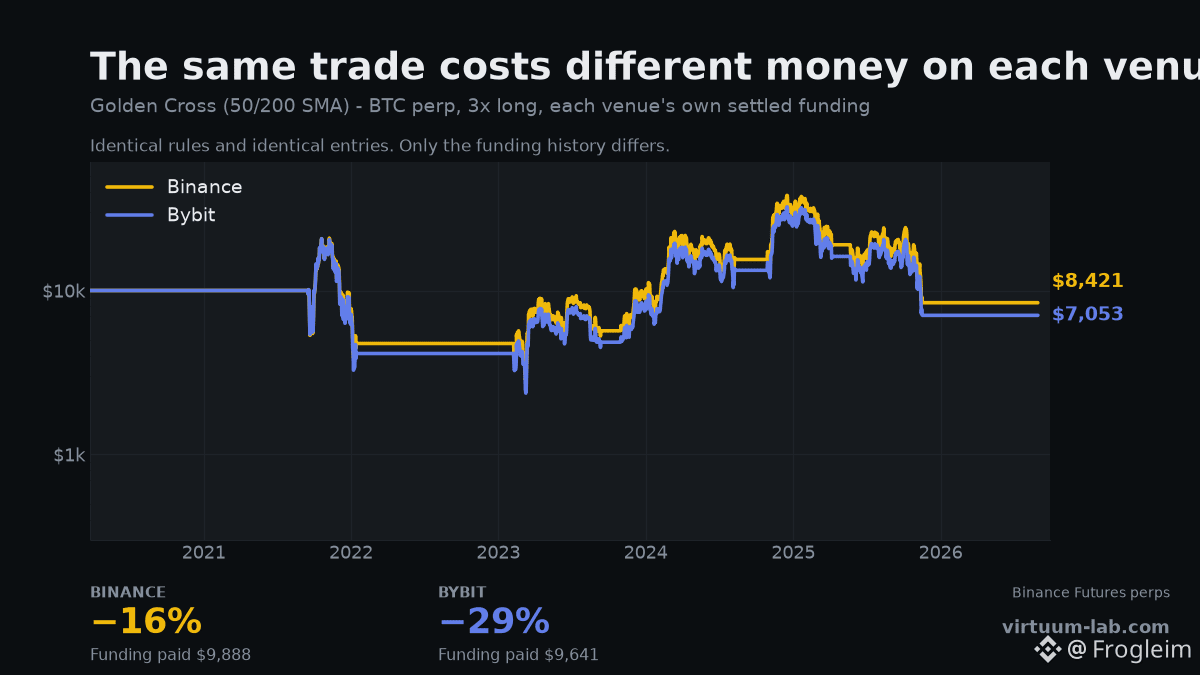
Same strategy. Same pair. Same five trades, on the same days. Two exchanges, 14 points apart.
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Same strategy. Same pair. Same five trades, on the same days. Two exchanges, 14 points apart.
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
Golden Cross, 50/200 SMA, 3x long BTCUSDT perp, 2020-03-25 to today, each venue charged its own settled funding.
Binance: −16% — $9,888 of funding paid
Bybit: −29% — $9,641 of funding paid
The entries and exits are identical. Same signal dates, all 5 of them. And the funding bills are within a few hundred dollars of each other, so that isn't the explanation either.
The gap is the candles. Every exchange prints its own price, and a rule that reads "close above the 200 SMA" reads a slightly different close on each one. Same rule, different prints, different fills — and 14 points of difference by the end.
Which means a backtest is only as real as the venue it was run on. If you tested on one exchange's data and traded on another's, you tested a strategy you did not deploy.
It also puts a floor on precision. If two honest data sources disagree by 14 points on the same rules, no backtest result is accurate to the decimal place, and anyone quoting you one is selling something.
Pick the exchange you actually trade on 👉 https://virtuum-lab.com
#BTC #Binance #Bybit #Backtesting
140
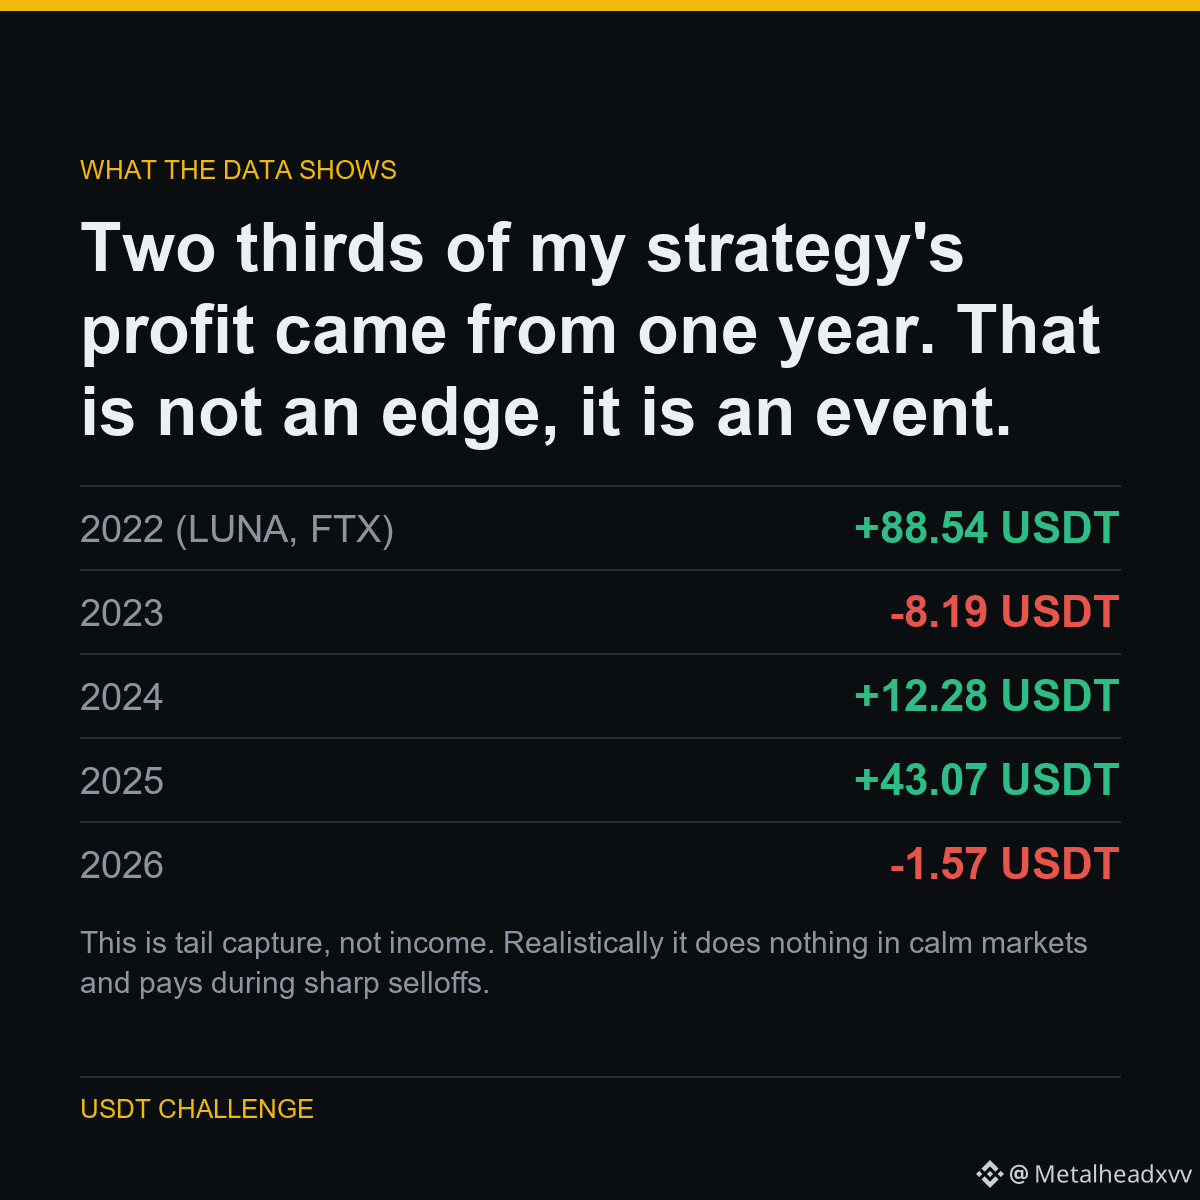
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Here is what that came from.
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
This is tail capture, not income. Realistically it does nothing in calm markets and pays during sharp selloffs. Expecting it to earn every month is how people quit a strategy right before it works.
Here is what that came from.
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
Here is what that came from.
Two thirds of my strategy's profit came from one year. That is not an edge, it is an event.
The headline number was +134.12 USDT from short breakouts. Then I split it by year.
2022 - the year of the LUNA collapse and the FTX failure - produced 88.54 of it. Strip that year out and four years of trading returned 45.59 USDT, most of it from 2025.
2026 so far is flat.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
60

·
--
Article
TRADING IS LIKE A MUSTANG: IT'S BORN IN A LABIn my confessions as a rookie trader, today I want to tell you why trading without a system is like driving blind...
I must confess that when I started in this game, one of the hardest things for me was remembering that an RSI of 70 meant overbought and 30 meant oversold. Something so 'basic' created a terrifying void in my mind. And no, it wasn't due to a lack of intelligence; it's just that trading with dyslexia and dyscalculia forces you to live in a universe where numbers and directions sometimes turn into a dead-end tunnel.
TRADING IS LIKE A MUSTANG: IT'S BORN IN A LAB
In my confessions as a rookie trader, today I want to tell you why trading without a system is like driving blind...
I must confess that when I started in this game, one of the hardest things for me was remembering that an RSI of 70 meant overbought and 30 meant oversold. Something so 'basic' created a terrifying void in my mind. And no, it wasn't due to a lack of intelligence; it's just that trading with dyslexia and dyscalculia forces you to live in a universe where numbers and directions sometimes turn into a dead-end tunnel.
I must confess that when I started in this game, one of the hardest things for me was remembering that an RSI of 70 meant overbought and 30 meant oversold. Something so 'basic' created a terrifying void in my mind. And no, it wasn't due to a lack of intelligence; it's just that trading with dyslexia and dyscalculia forces you to live in a universe where numbers and directions sometimes turn into a dead-end tunnel.
1
650
·
--
Bullish
We believe crypto should feel less like a casino.
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
We believe crypto should feel less like a casino.
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
And more like a well-tested system for sustainable growth.
That's why CryptoGates exists:
→ Build strategies — don't guess them
→ Backtest on real historical data — don't assume
→ Predict & optimize — don't hope
→ Automate with discipline — don't react
Earning without stress.
Participating without obsession.
Growing without gambling.
No signup. No credit card. Just build.👇
$BTC $BNB #Backtesting
135
·
--
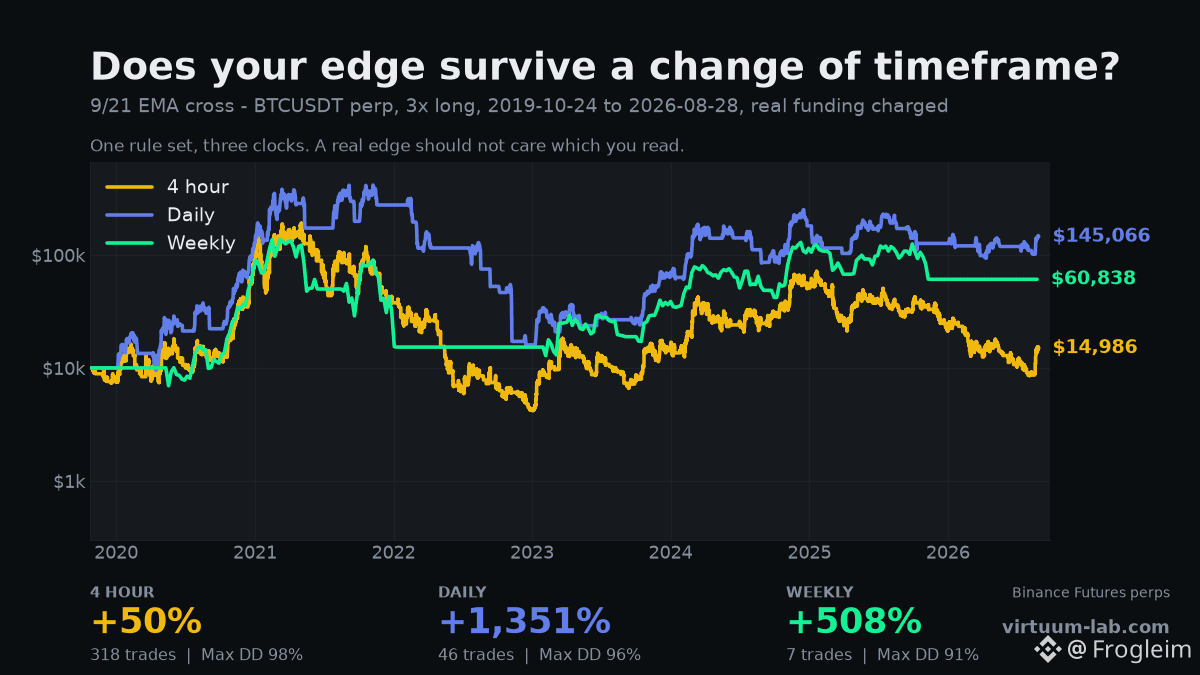
Same rule. Three clocks. 1,301 points apart.
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
Same rule. Three clocks. 1,301 points apart.
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
9/21 EMA cross, 3x long BTCUSDT perp, real Binance funding, same window on all three so nothing gets a head start.
4 hour: +50% — 318 trades, max drawdown 98%
Daily: +1,351% — 46 trades, max drawdown 96%
Weekly: +508% — 7 trades, max drawdown 91%
Nobody chose a timeframe for a reason. You picked the one your chart opened on.
The 4 hour version trades 318 times and hands almost all of it back — every crossing costs fees, slippage and funding, and on a fast clock most crossings are noise. The weekly version takes 7 trades in 41 years and keeps more of what it makes.
The uncomfortable read: if a strategy only works on one timeframe, the timeframe is doing the work, not the strategy. A real edge degrades gracefully when you change the clock. This one doesn't — it swings by 1,301 points.
Before you trust a backtest, run it on the timeframe either side of the one you like.
Change the clock and see what survives 👉 https://virtuum-lab.com
#BTC #TradingStrategy #Backtesting
124
A strategy can look flawless on daily candles and still get rekt live.
Why?
Daily data smooths over intraday wicks and fake breakouts your bot never got tested against.
CG backtests DCA, Grid, and Rebalance bots on 1-min OHLCV data - no shortcuts.
Stress test yours...
#Bitcoin #CryptoTrading #Backtesting
A strategy can look flawless on daily candles and still get rekt live.
Why?
Daily data smooths over intraday wicks and fake breakouts your bot never got tested against.
CG backtests DCA, Grid, and Rebalance bots on 1-min OHLCV data - no shortcuts.
Stress test yours...
#Bitcoin #CryptoTrading #Backtesting
Why?
Daily data smooths over intraday wicks and fake breakouts your bot never got tested against.
CG backtests DCA, Grid, and Rebalance bots on 1-min OHLCV data - no shortcuts.
Stress test yours...
#Bitcoin #CryptoTrading #Backtesting
79
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanBTCReboundAfterFallingBelow60K?
369,886 views
1,555 Discussing
2
#GlobalStocksFaceLongestLosingStreakSince2023
123,905 views
1,098 Discussing
3
#BlackRockIBITPostsRecord$541MSingleDayOutflow
721 views
17 Discussing
4
#AnthropicPlungesTowardIPOPriceonDay2
59,580 views
598 Discussing
5
#TwentyOneCapitalAdds172.25BTC
12,105 views
162 Discussing
6
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
1,017 views
14 Discussing
7
#BNBDropsBelow540USDTWith8.46%DailyDecline
32,808 views
278 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
1,079 views
14 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
2,028 views
18 Discussing
10
#StrategyReports$35BNetReserves
2,046 views
18 Discussing